
- Ronny Mor
- •
- 6 Min Read
- •
- 53 seconds ago
Key Points
- Spot gold fell roughly 1% to $3,840.52 per troy ounce on Monday, November 16—its lowest level since October 2025—extending last week’s 4.65% slide in December COMEX futures.
- Surging 10-year U.S. Treasury yields near 5.15% and a U.S. Dollar Index peak of 103.43 have raised the opportunity cost of holding non-yielding bullion after sticky October inflation prints.
- For international allocators and Israeli institutional desks, Western ETF redemptions are colliding with Asian physical dip-buying and sustained central bank reserve accumulation.
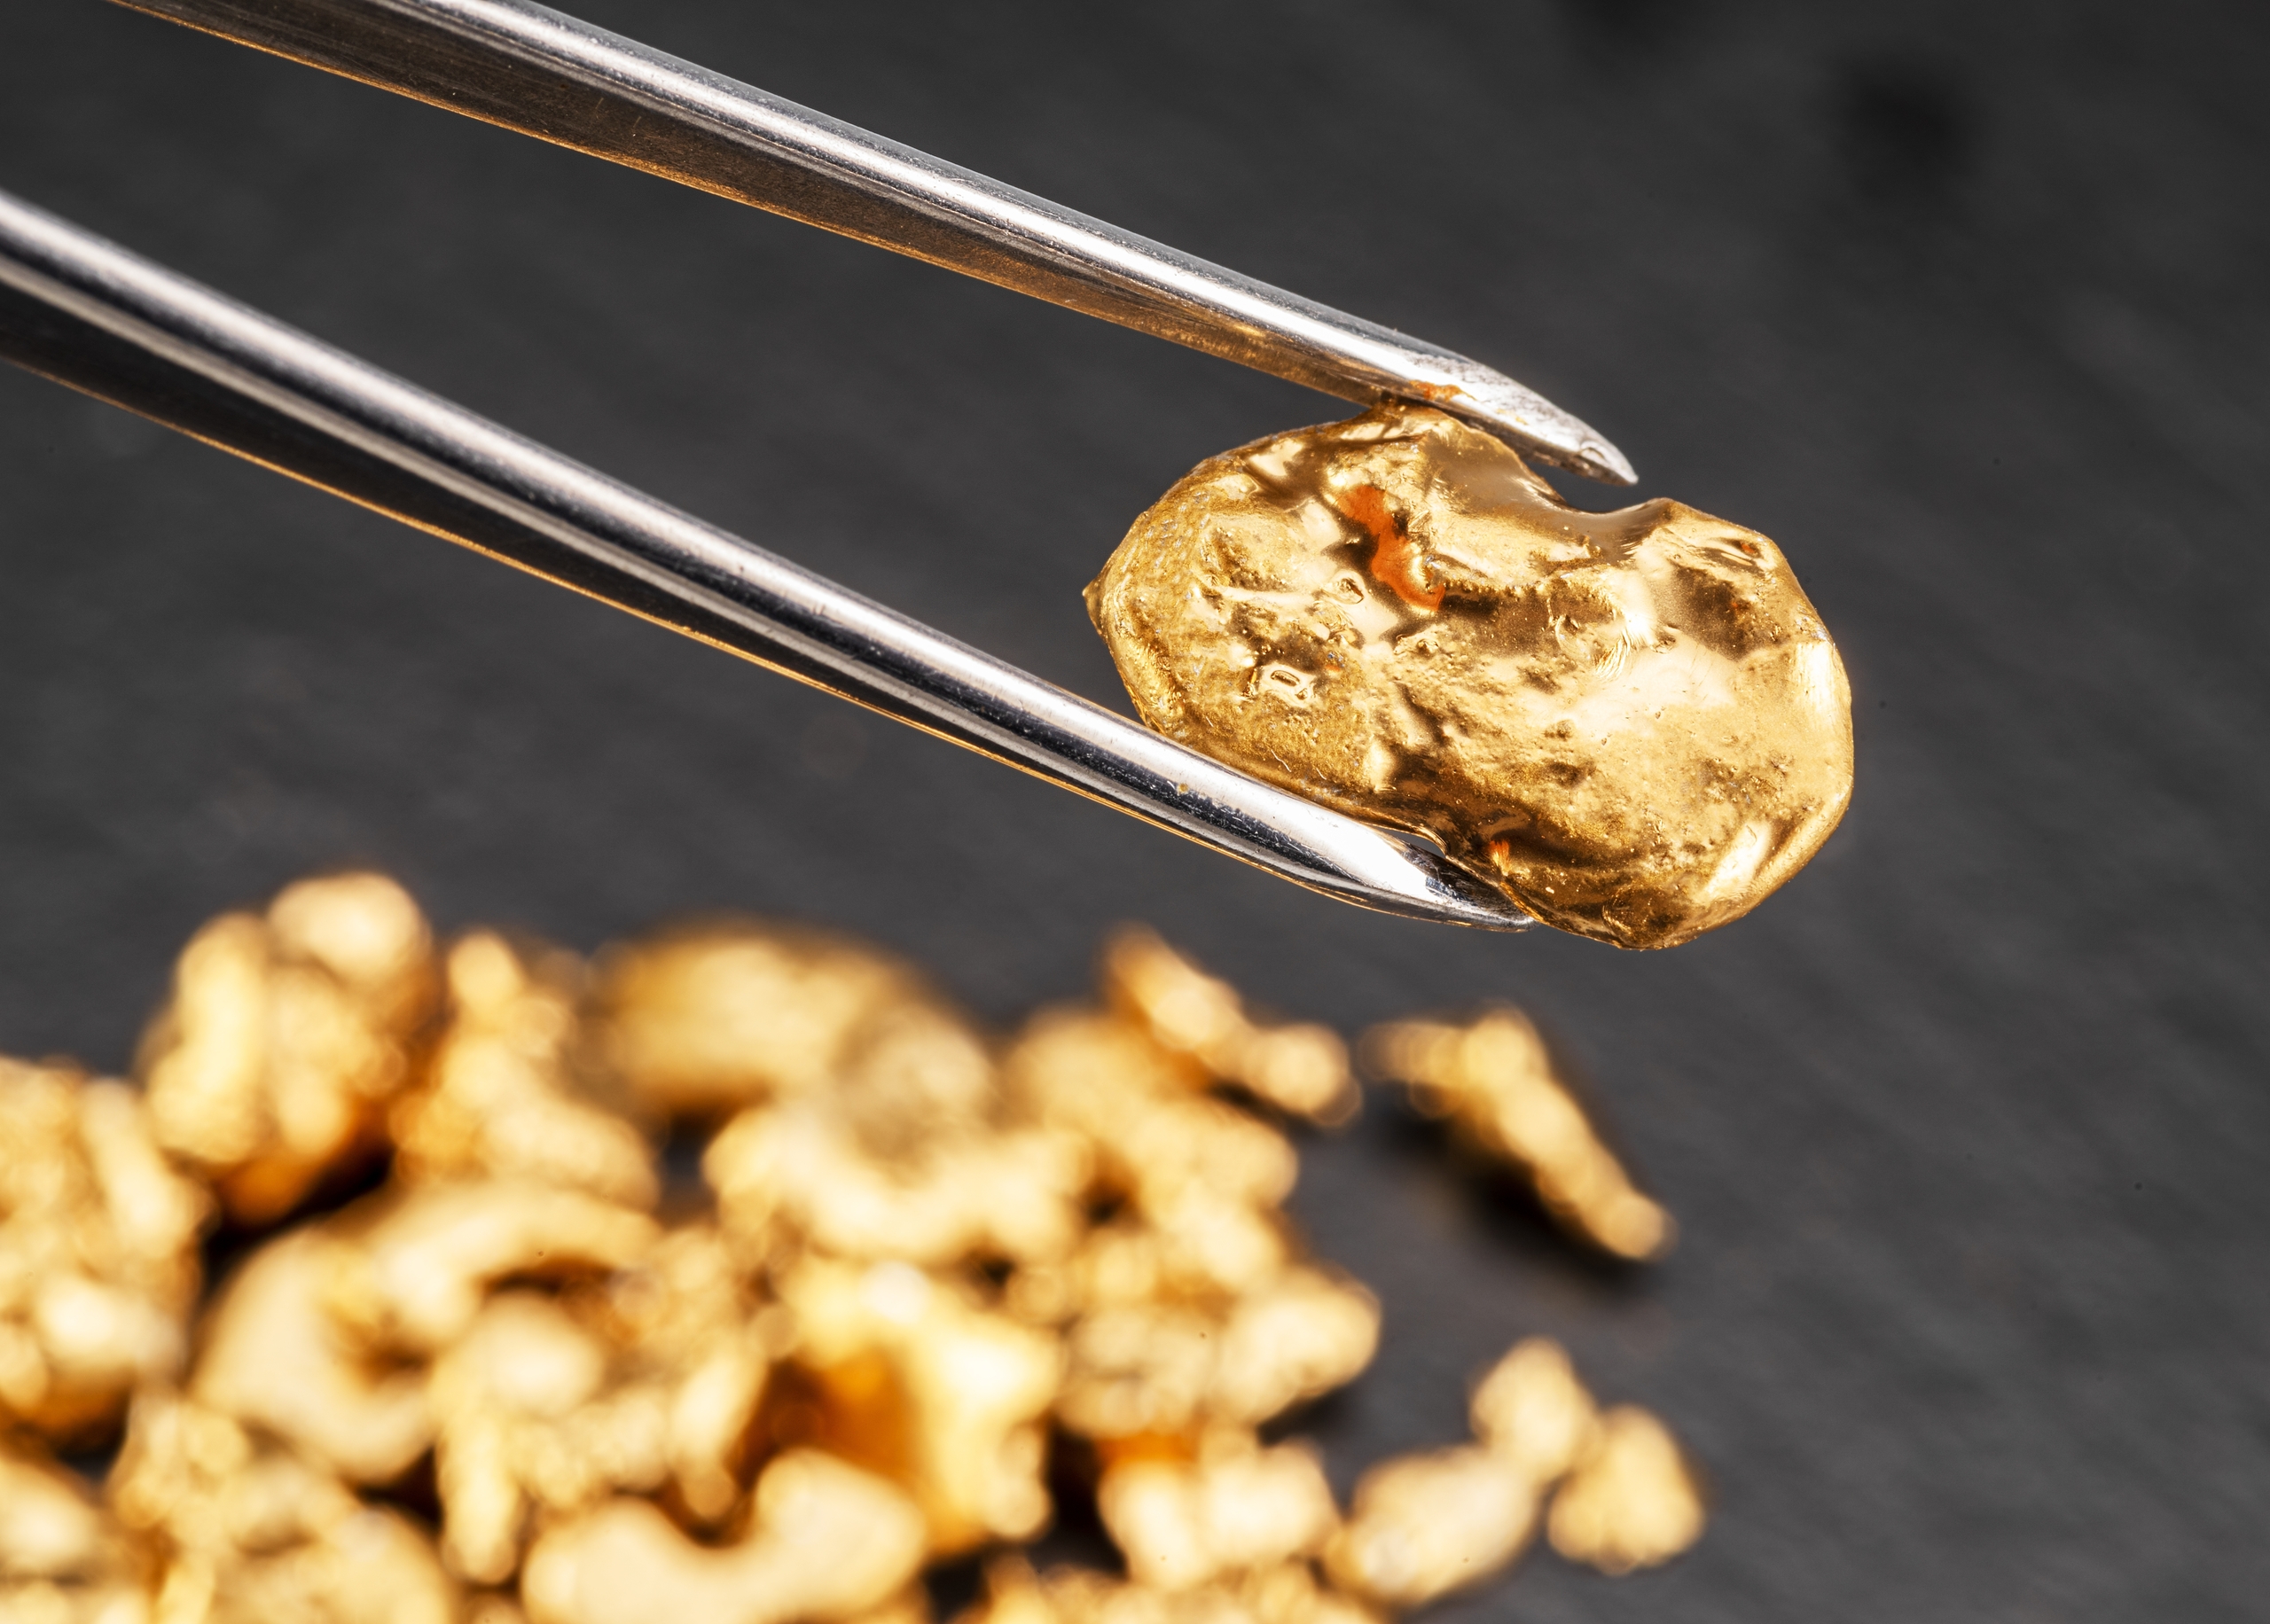
Spot gold struggled to mount a recovery on Monday, November 16, 2026, sliding roughly 1% to $3,840.52 per troy ounce—its lowest mark since October 2025—as a 19-month high in the U.S. dollar and surging Treasury yields overwhelmed safe-haven demand. Following last week’s 4.65% drop in December COMEX futures, bullion remains pinned near multi-month lows as sticky U.S. inflation reinforces expectations for a December Federal Reserve rate hike.
Real-Rate Shock and Dollar Rally Fuel Western ETF Outflows
The primary weight on precious metals stems from an acute repricing across U.S. fixed-income and foreign-exchange markets. Hotter-than-forecast October consumer and producer inflation data—including a 6.5% annual rise in producer prices—propelled the benchmark 10-year U.S. Treasury yield to 5.15% after a 29.5-basis-point weekly surge, while pushing the U.S. Dollar Index to 103.43. With money markets pricing in near-certainty of a rate increase at next month’s Federal Open Market Committee meeting, the opportunity cost of holding non-yielding bullion has climbed sharply.
This real-rate shock has triggered substantial liquidations among North American exchange-traded fund investors, who can capture over 5% in risk-free sovereign debt while benefiting from domestic currency appreciation. The SPDR Gold Shares ETF (GLD) declined 4.58% last week amid accelerating mid-month redemptions, pulling gold down more than 7% year-to-date and erasing its November 9 rebound toward $4,149. Even intermittent geopolitical friction in the Middle East—including tensions in the Strait of Hormuz—has failed to sustain safe-haven inflows, as energy-driven inflation risks reinforce hawkish monetary expectations rather than monetary easing.
Regional Flow Divergence and Portfolio Context for Israeli Desks
Despite heavy institutional selling during North American trading hours, physical demand across Asia and official-sector reserve purchases continue to cushion downside momentum. Intraday trading patterns show Asian buyers consistently stepping in on dips ahead of year-end festival demand, even as U.S. desks sell into rallies. Simultaneously, sovereign central banks have maintained steady bullion accumulation to diversify foreign-exchange reserves over the medium term.
For Israeli institutional pension managers and multi-asset desks on the Tel Aviv Stock Exchange (TASE), gold’s pullback illustrates the dominance of U.S. real interest rates over traditional inflation-hedge narratives. With the New Israeli Shekel (NIS) trading steadily near 3.17 per dollar, local institutional allocators face lower currency-adjusted volatility than unhedged dollar holders, yet high domestic yields on government bonds (Shahar) and inflation-linked notes (Galil) continue to offer more attractive carry than non-yielding commodities.
Outlook: $3,800 Technical Support, Fed Minutes, and Seasonal Flows
Moving through mid-November, market participants will watch closely whether spot gold can defend immediate technical support around $3,855–$3,870 or faces a deeper test of the $3,800 psychological floor. Key macro catalysts this week include U.S. retail sales data, commentary from Federal Reserve Chair Kevin Warsh, and Wednesday’s release of the FOMC meeting minutes. While historically favorable November-to-January seasonal jewelry and portfolio flows could aid stabilization, a sustained recovery above the $3,920–$3,950 resistance zone will likely require a peak in Treasury yields and a pause in dollar appreciation.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- sagi habasov
- •
- 7 Min Read
- •
- ago 5 hours
SKN | Gold Hits One-Year Low as Strong Dollar and Treasury Yields Intensify Pressure
Gold has entered a more challenging phase as higher U.S. Treasury yields, a stronger dollar and expectations for tighter
- ago 5 hours
- •
- 7 Min Read
Gold has entered a more challenging phase as higher U.S. Treasury yields, a stronger dollar and expectations for tighter

- orshu
- •
- 7 Min Read
- •
- ago 2 days
SKN | Can Trump Reduce China’s Critical Minerals Advantage Before Talks With Xi?
President Donald Trump enters talks with Chinese President Xi Jinping this week with a central element of his trade
- ago 2 days
- •
- 7 Min Read
President Donald Trump enters talks with Chinese President Xi Jinping this week with a central element of his trade

- Lior mor
- •
- 6 Min Read
- •
- ago 3 days
SKN | Global Oil Market Set to Return to Surplus as Gulf Exports Recover
The global oil market is showing signs of returning to surplus as Middle Eastern producers restore exports disrupted by
- ago 3 days
- •
- 6 Min Read
The global oil market is showing signs of returning to surplus as Middle Eastern producers restore exports disrupted by
- orshu
- •
- 8 Min Read
- •
- ago 5 days
SKN | China and Poland Accelerate Gold Accumulation as Central Bank Demand Reshapes the Global Market
Central banks in China and Poland are continuing to expand their gold reserves, reinforcing the role of official-sector demand
- ago 5 days
- •
- 8 Min Read
Central banks in China and Poland are continuing to expand their gold reserves, reinforcing the role of official-sector demand