
- Ronny Mor
- •
- 7 Min Read
- •
- 17 seconds ago
Key Points
- Singapore’s central bank manages the Singapore dollar against a trade-weighted basket of currencies rather than setting a domestic policy interest rate.
- The Monetary Authority of Singapore (MAS) adjusts the slope, midpoint and width of an exchange-rate policy band to influence inflation.
- The framework reflects Singapore’s reliance on trade and imports, while domestic interest rates remain heavily influenced by global financial conditions.
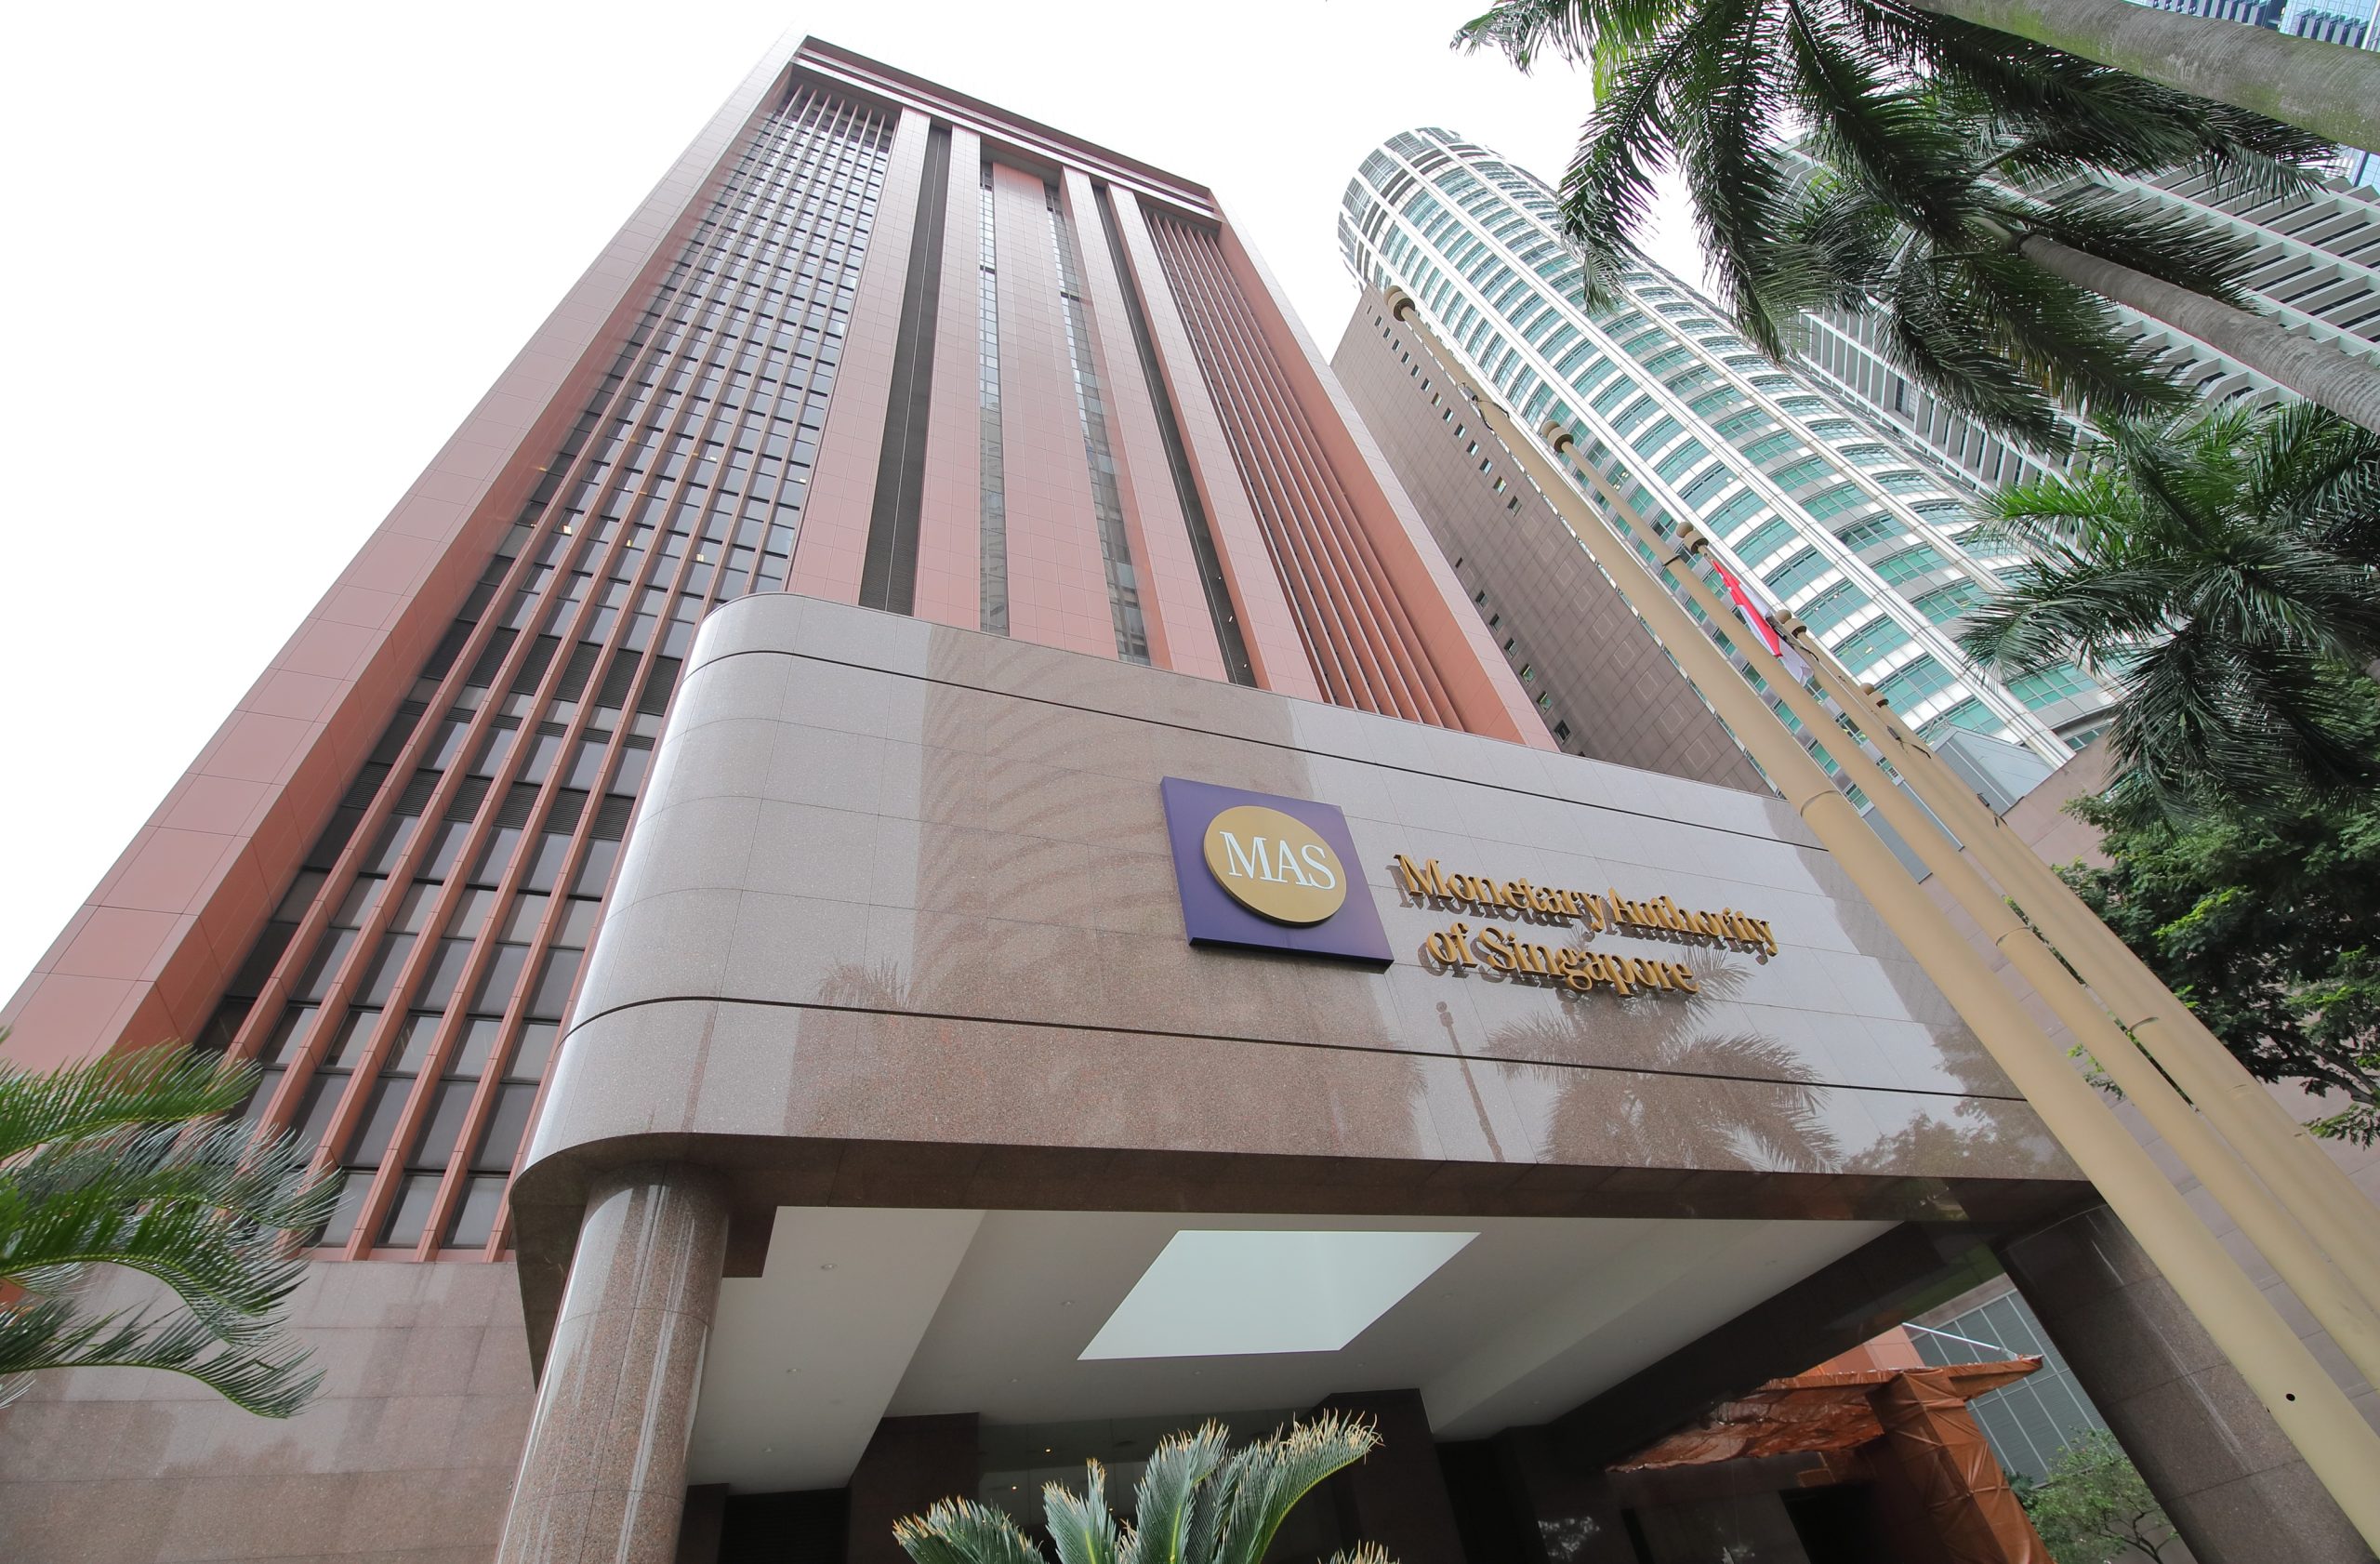
Most central banks use interest rates as their main tool for controlling inflation, but Singapore takes a different approach. Since 1981, the Monetary Authority of Singapore has conducted monetary policy primarily by managing the exchange rate of the Singapore dollar, reflecting the city-state’s deep integration into global trade. The system is particularly relevant as central banks worldwide weigh inflation risks against economic growth and shifting energy prices.
Why Singapore Uses the Exchange Rate Instead of Interest Rates
Singapore’s economic structure helps explain its unusual policy. The combined value of exports and imports of goods and services exceeds three times the country’s GDP, while about 40 cents of every dollar spent domestically goes toward imports. Currency movements therefore have a direct influence on the cost of food, energy, raw materials and other imported products.
A stronger Singapore dollar makes foreign goods cheaper in local-currency terms, helping contain imported inflation. A weaker currency can have the opposite effect by raising import costs. MAS therefore considers the exchange rate a more effective instrument for managing domestic price pressures than targeting interest rates alone. Its primary objective is medium-term price stability that supports sustainable economic growth.
How the S$NEER Policy Band Works
The central bank does not peg the Singapore dollar to a single currency or hold it at one fixed exchange rate. Instead, it manages the Singapore dollar nominal effective exchange rate, known as the S$NEER. This index measures the currency against a basket of trading partners’ currencies, weighted according to their importance to Singapore’s trade.
MAS allows the index to fluctuate within a policy band and adjusts three parameters. The **slope** determines the rate at which the band allows the currency to appreciate or depreciate over time. The **midpoint** can be shifted to strengthen or weaken the currency immediately, while the **width** determines how much the exchange rate can fluctuate within the band.
A steeper appreciating slope generally represents tighter monetary policy because it supports a stronger currency and helps restrain imported inflation. A flatter slope reduces the pace of appreciation, providing a form of policy easing. MAS reviews the settings regularly in response to economic conditions and the inflation outlook.
What the Framework Means for Markets and Investors
Singapore’s approach does not mean that domestic interest rates are fixed or irrelevant. With capital moving freely across borders, local rates are heavily influenced by global interest rates and expectations for the Singapore dollar. As a result, MAS cannot independently target both the exchange rate and a domestic interest rate that diverges substantially from international conditions.
On October 14, 2026, MAS left its policy settings unchanged, despite expectations of further tightening among analysts surveyed by Reuters. The central bank maintained the prevailing appreciation rate, midpoint and width of the band. Singapore’s economy had expanded 5.4% year over year in the third quarter, while core inflation stood at 2.2% in August. MAS narrowed its forecast for core inflation to 1.5%–2% and projected headline inflation of 2%.
Going forward, markets will monitor imported energy and food costs, global interest rates, economic growth and the pace of inflation. For international investors, understanding Singapore’s exchange-rate framework is essential when assessing the Singapore dollar, local borrowing conditions and the country’s response to external economic shocks. The key question is whether currency appreciation will continue to contain inflation without placing excessive pressure on growth and trade competitiveness.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- Lior mor
- •
- 6 Min Read
- •
- ago 3 hours
SKN | Saudi Arabia Drives OPEC+ Production Higher Despite Iran War Disruptions
OPEC+ sharply increased oil production in September despite continued disruption to shipments through the Strait of Hormuz caused by
- ago 3 hours
- •
- 6 Min Read
OPEC+ sharply increased oil production in September despite continued disruption to shipments through the Strait of Hormuz caused by

- Arik Arkadi Sluzki
- •
- 7 Min Read
- •
- ago 3 hours
SKN | Fed’s Williams Sees No Need for 2027 Rate Hike as Inflation Gradually Cools
New York Federal Reserve President John Williams said he currently sees no need for additional interest-rate increases in 2027,
- ago 3 hours
- •
- 7 Min Read
New York Federal Reserve President John Williams said he currently sees no need for additional interest-rate increases in 2027,
- omer bar
- •
- 7 Min Read
- •
- ago 3 hours
SKN | PIMCO Warns U.S. Treasury Yields May Have Further Room to Rise as Fed Tightening Could Continue
U.S. Treasury yields may not have reached their peak, with the Federal Reserve potentially having room for one or
- ago 3 hours
- •
- 7 Min Read
U.S. Treasury yields may not have reached their peak, with the Federal Reserve potentially having room for one or
- omer bar
- •
- 6 Min Read
- •
- ago 4 hours
SKN | Labor Quality Tops U.S. Small-Business Concerns for Third Straight Month as Inflation Remains a Challenge
Labor Quality Remains the Biggest Challenge The quality of available labor was identified as the single most important problem by
- ago 4 hours
- •
- 6 Min Read
Labor Quality Remains the Biggest Challenge The quality of available labor was identified as the single most important problem by