




- omer bar
- •
- 7 Min Read
- •
- 1 minute ago


Key Points
- The U.S. dollar climbed to its highest level since July 29 as markets increased expectations for another Federal Reserve rate hike.
- Odds of an October Fed rate increase rose to about 70% after stronger economic data and hawkish comments from Fed officials.
- The S&P Global U.S. Composite PMI accelerated to 58.4 in September from 56.0 in August, while higher oil prices added another potential source of inflation pressure.
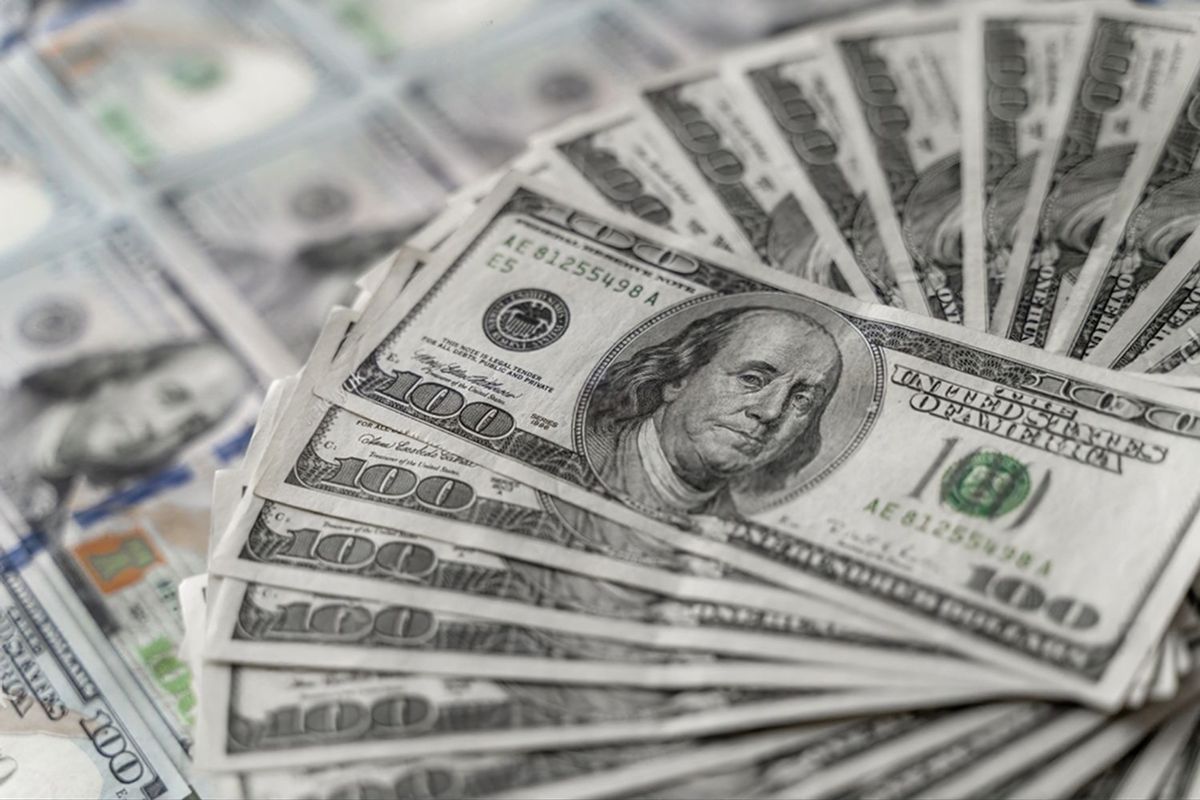
The U.S. dollar advanced to a nearly two-month high on Wednesday as investors reassessed the Federal Reserve’s interest-rate path following stronger economic data and renewed inflation concerns. The move came as markets increasingly priced the possibility of another rate increase in October, while higher oil prices linked to uncertainty around Iran diplomacy added another potential source of price pressure.
Fed Expectations Give the Dollar Fresh Momentum
The dollar’s latest advance reflects a significant shift in expectations following the Federal Reserve’s quarter-percentage-point rate increase last week, which lifted the federal funds target range to 3.75% to 4.00%. Several Fed officials have since indicated that additional tightening could be necessary if inflation fails to moderate sufficiently.
Fed Governor Michael Barr said Wednesday that the central bank would likely need to deliver further rate increases after what he described as an important step to recalibrate short-term borrowing costs. St. Louis Fed President Alberto Musalem also said earlier in the week that additional hikes were likely needed to address persistent inflation.
Interest-rate expectations are particularly important for foreign exchange markets because higher U.S. rates can increase the relative return available on dollar-denominated assets. The latest repricing has therefore provided renewed support for the currency after a period in which investors had questioned the dollar’s longer-term direction.
U.S. Economic Data Reinforce Inflation Concerns
The latest business survey provided another reason for markets to reassess monetary policy. The S&P Global U.S. Composite PMI rose to 58.4 in September from 56.0 in August, reaching its highest level since July 2021. New orders also climbed to their strongest level since March 2022, indicating that demand remains resilient across manufacturing and services.
At the same time, the survey showed that businesses were facing higher costs. The measure of input prices reached its highest level in nearly four years, while supplier delivery times lengthened sharply and work backlogs reached their highest level since May 2022. The combination of strong demand and rising costs complicates the Fed’s effort to return inflation to its 2% target.
The resilience of the economy also reduces the immediate pressure on policymakers to respond to weaker employment conditions. Instead, the latest data reinforce the argument among some Fed officials that inflation remains the more pressing policy concern.
Oil Adds a Geopolitical Inflation Risk
The dollar’s move higher occurred alongside a renewed increase in oil prices after comments from Iran cast doubt on progress toward diplomatic resolution of the Middle East conflict. Earlier hopes of progress had helped push crude prices lower, but those gains reversed as markets reassessed the likelihood of a near-term agreement.
Higher energy prices matter for currency markets because they can reinforce inflation expectations and complicate central-bank policy decisions. For the Federal Reserve, a persistent oil shock could make it more difficult to distinguish temporary supply-driven inflation from broader price pressures.
Yen and Euro Show Different Pressures
The dollar’s strength was particularly visible against the Japanese yen, which weakened about 0.6% to 158.32 per dollar. The move kept intervention concerns in focus after the Bank of Japan raised its policy rate to a 31-year high last week but provided limited reassurance that further increases would follow quickly. The euro also weakened, falling about 0.52% to $1.1386.
Markets will now focus on whether stronger U.S. activity and elevated energy prices translate into persistent inflation. October rate expectations, Treasury yields, oil prices and incoming U.S. inflation data will remain central to the dollar’s trajectory. A continued shift toward tighter Fed policy could provide further support for the currency, while signs of easing inflation or weakening demand could reverse some of the recent repricing.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- orshu
- •
- 7 Min Read
- •
- ago 56 seconds
SKN | ECB Sees Limited Wage Pressure Despite Surging Inflation, Keeping Rate Outlook in Focus
The European Central Bank is seeing limited evidence that this year's sharp energy-price shock is translating into significantly higher
- ago 56 seconds
- •
- 7 Min Read
The European Central Bank is seeing limited evidence that this year's sharp energy-price shock is translating into significantly higher

- Ronny Mor
- •
- 7 Min Read
- •
- ago 2 minutes
SKN | Inflation Pressures Raise Prospect of Another Fed Rate Hike Ahead of U.S. Elections
Rising inflation pressures and resilient U.S. economic activity are increasing the prospect of another Federal Reserve rate increase just
- ago 2 minutes
- •
- 7 Min Read
Rising inflation pressures and resilient U.S. economic activity are increasing the prospect of another Federal Reserve rate increase just
- omer bar
- •
- 6 Min Read
- •
- ago 11 minutes
SKN | U.S. 30-Year Treasury Yield Surges Above 5.4% as Bond Market Comes Under Renewed Pressure
Long-Term Treasury Yields Are Moving Higher The 30-year Treasury market experienced a significant selloff during the September 23 session. The
- ago 11 minutes
- •
- 6 Min Read
Long-Term Treasury Yields Are Moving Higher The 30-year Treasury market experienced a significant selloff during the September 23 session. The

- Arik Arkadi Sluzki
- •
- 7 Min Read
- •
- ago 53 minutes
SKN | Is 6% the New Threshold for U.S. Treasury Market Stress?
The 5% level on the benchmark U.S. 10-year Treasury yield was once regarded as a major psychological barrier for
- ago 53 minutes
- •
- 7 Min Read
The 5% level on the benchmark U.S. 10-year Treasury yield was once regarded as a major psychological barrier for
