




- orshu
- •
- 9 Min Read
- •
- 7 hours ago


Key Points
- Hong Kong’s Hang Seng Index advances 1.46%, South Korea’s KOSPI gains 0.51%, and India’s S&P BSE Sensex rises 0.42% to lead early session gainers.
- Mainland China’s SSE Composite Index drops 1.44%, while Japan’s Nikkei 225 declines 0.33% and Australia’s S&P/ASX 200 retreats 0.35%.
- The PHLX Yen inches up 0.06%, while the Australian Dollar Currency Index slips 0.03% and APAC Private Equity sheds 0.27%, alongside a market closure in the Philippines for All Souls' Day.
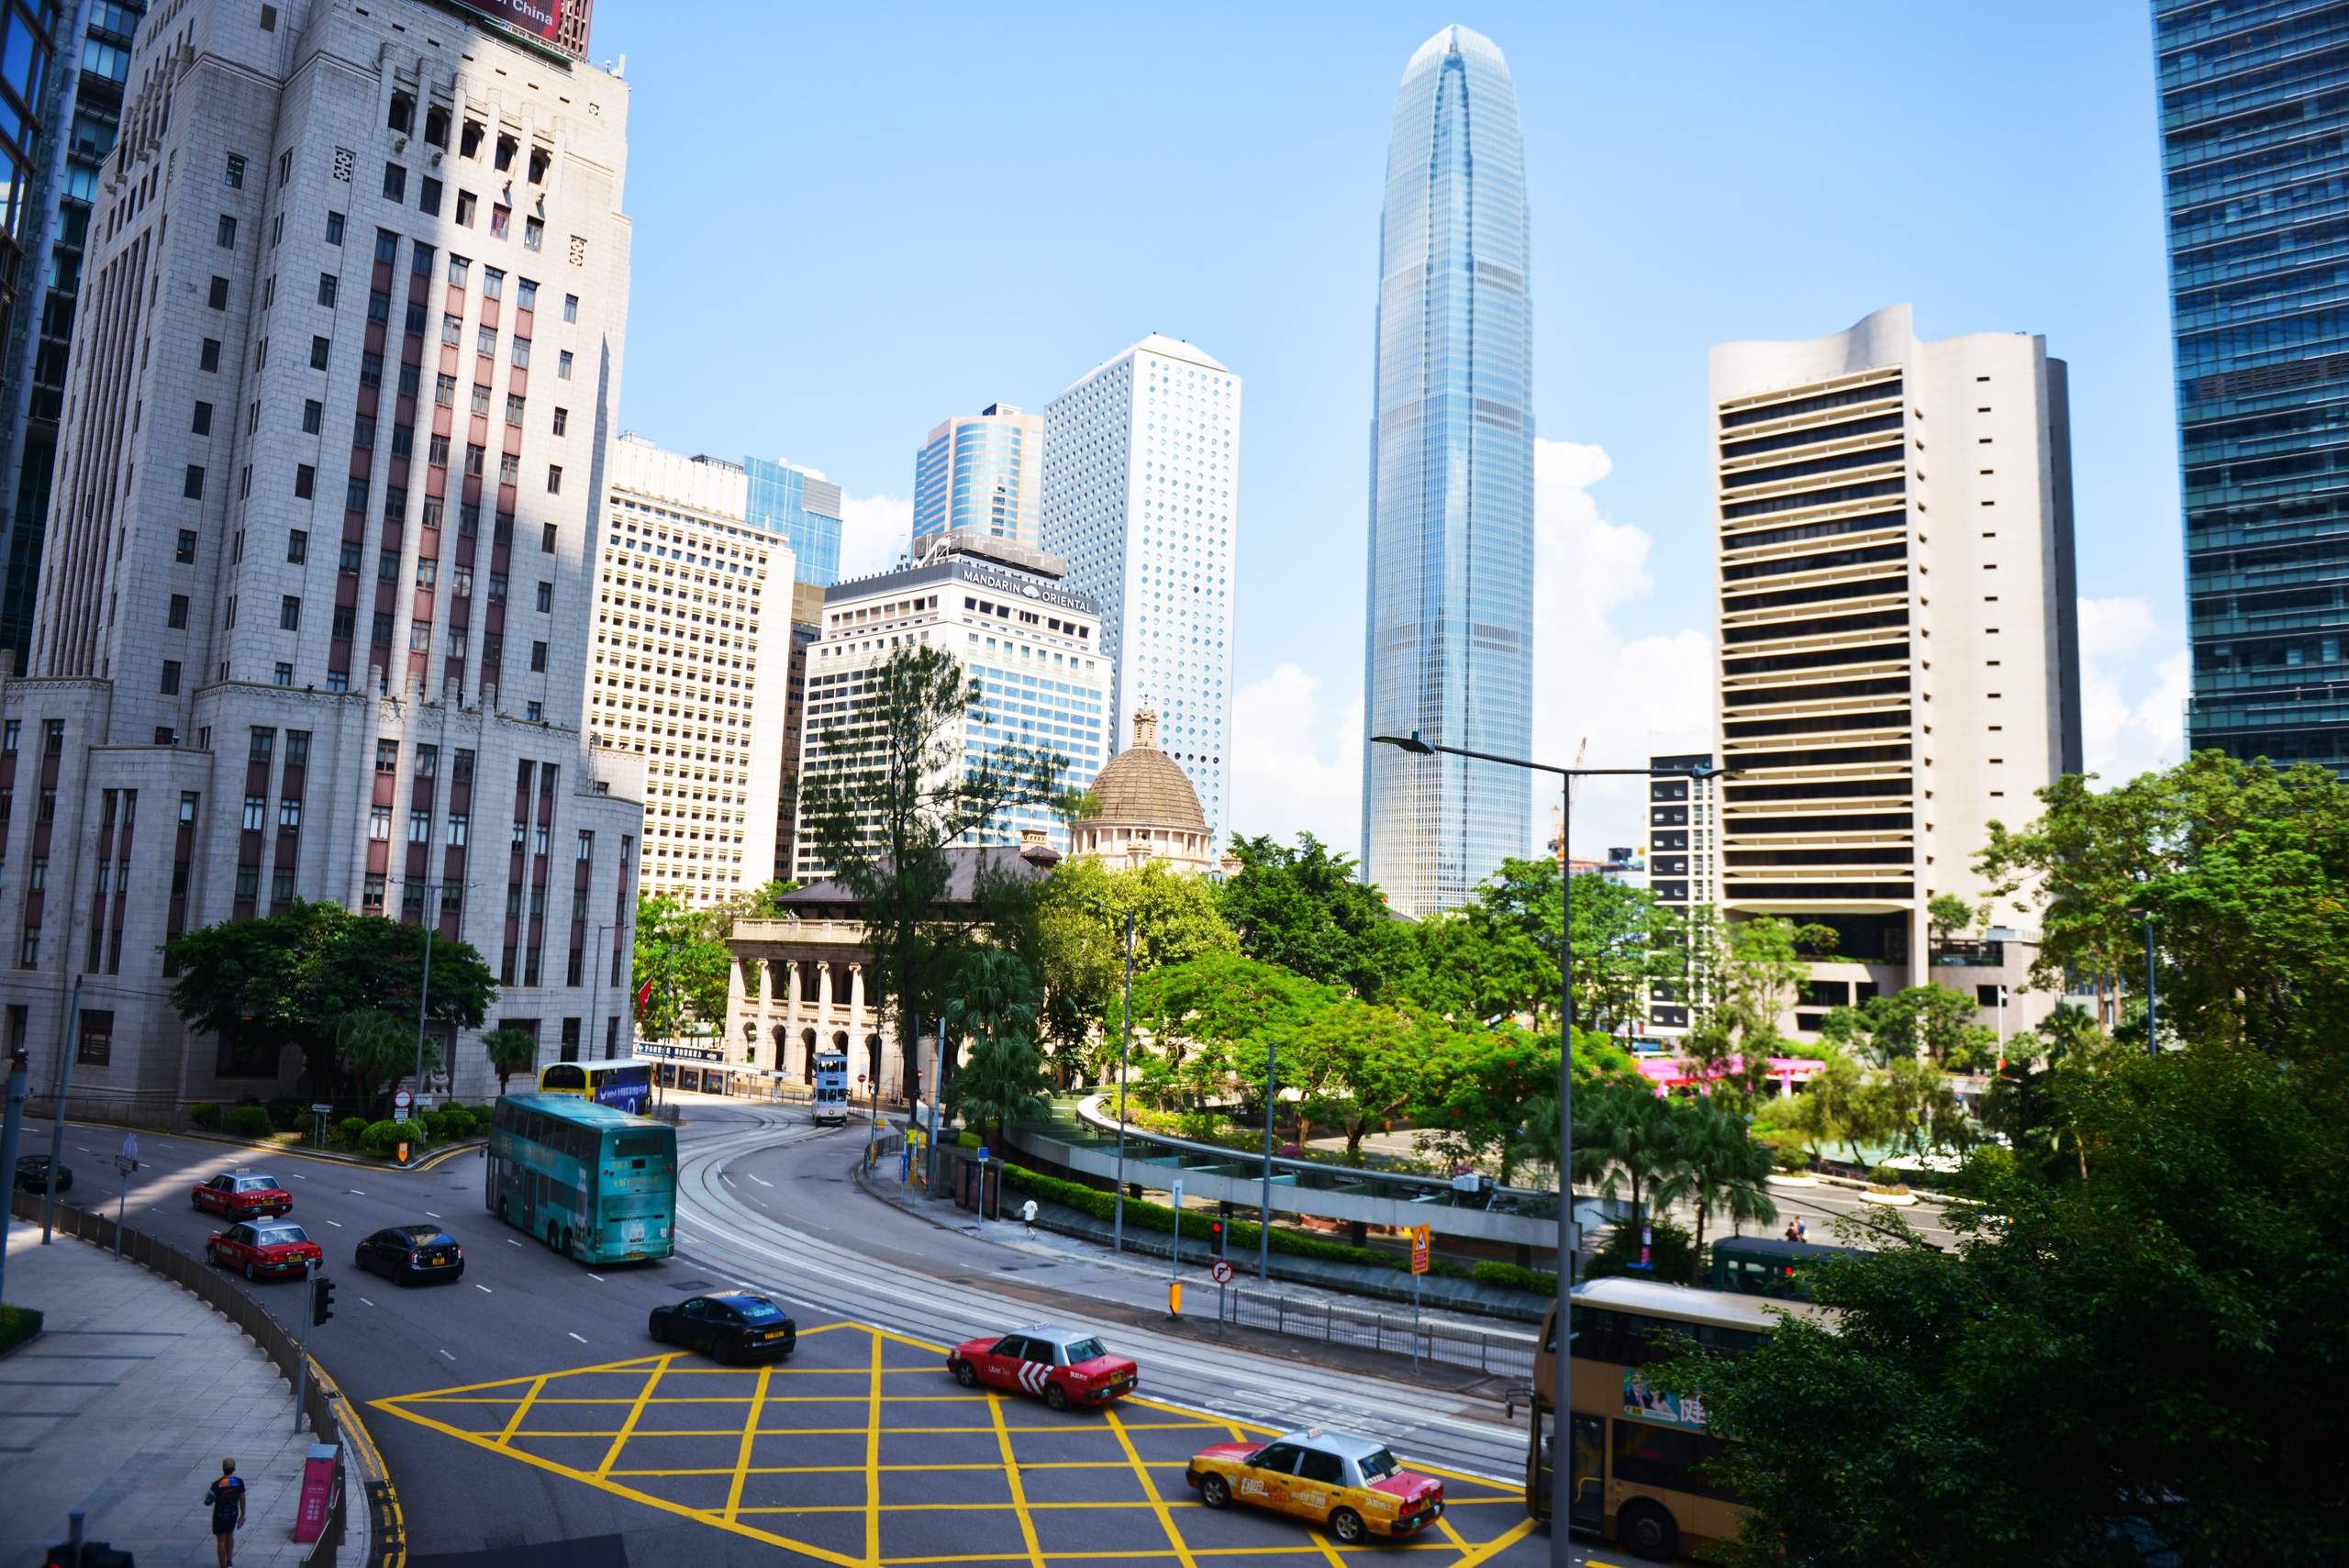
Asian equity benchmarks display noticeable divergence during the morning session on Monday, November 2, opening the trading week with selective regional risk appetite. Robust morning buying in Hong Kong, Seoul, and Mumbai stands in contrast to declines across mainland China, Tokyo, and Sydney. While the performance figures indicate distinct regional reallocation between markets, the supplied data does not pinpoint a single macroeconomic event or policy catalyst driving the morning moves.
Hong Kong, South Korea and India Lead Regional Advances
Hong Kong’s Hang Seng Index records the most pronounced upward momentum among major Asian benchmarks, jumping 1.46% to reach 23,294.42 during early Monday trade. The sharp advance in Hong Kong provides an anchor of positive sentiment across regional bourses, though the reported data does not confirm whether the momentum is concentrated in technology platforms, property developers, or international financial conglomerates. The figures also do not provide turnover levels or sector-specific data to determine whether the gain is driven by mainland capital flows or broad international buying.
South Korea’s KOSPI Composite Index also moves higher, advancing 0.51% to trade at 5,760.21. The steady rise in Seoul indicates positive participation in early trade, continuing to attract investor attention across key industrial and export-linked listings. However, the dataset lacks specific details on semiconductor, hardware, or automotive order flows that would explain the morning strength.
India’s S&P BSE Sensex joins the regional gainers, rising 0.42% to 74,459.53. The firm tone in Mumbai highlights ongoing domestic participation and constructive positioning across Indian banking, consumer, and industrial shares. Market participants will watch whether these three positive regional performers can maintain their trajectory through the midday break and afternoon trading.
Mainland China, Japan and Australia Encounter Morning Selling
In stark contrast to the strength in Hong Kong, mainland Chinese shares open the week under visible pressure. The Shanghai SSE Composite Index drops 1.44% to 3,599.02, recording the largest percentage loss among the reported equity benchmarks and falling below the 3,600 mark. This decline creates a sharp divergence with the Hang Seng, pointing to divergent intraday dynamics between onshore mainland shares and offshore listings. The data does not indicate whether state-backed financial firms, industrial manufacturing, or domestic retail counters are driving the pullback.
Japan’s Nikkei 225 also turns lower, retreating 0.33% to 63,082.01 in morning trade. The pullback in Tokyo indicates mild profit-taking or defensive positioning among participants in prime-market constituents. The figures do not state whether export conglomerates or domestic cyclicals are pacing the decline, leaving the exact sector distribution unconfirmed.
Australia’s S&P/ASX 200 declines in tandem with Tokyo, slipping 0.35% to 8,876.60. Weakness across Sydney trading floors suggests localized pressure on resource, energy, or financial shares during early hours. Investors will observe whether mainland China, Japan, and Australia find technical support as the session progresses or face extended selling into the afternoon.
Regional Currency Metrics, Alternative Assets and Holiday Closures
Outside primary equity benchmarks, currency and private asset indicators reflect muted and mixed price adjustments across the Asia-Pacific landscape. The PHLX Yen index edges up 0.06% to 63.46, indicating relative price stability in the Japanese currency alongside the modest decline in the Nikkei 225.
Conversely, the Australian Dollar Currency Index ticks down 0.03% to 70.30, reflecting flat to slightly defensive positioning that mirrors the minor drop in Australia’s equity index. In private markets, the APAC Private Equity index declines 0.27% to 6,913.93, highlighting cautious valuation trends across private alternative assets. Because these asset classes operate under varying liquidity structures and valuation frameworks, their movements should be viewed as separate indicators rather than coordinated cross-asset repositioning.
In regional exchange schedules, the Philippines Stock Exchange is closed on Monday, November 2, in observance of the All Souls’ Day public holiday. Trading activity in Manila is scheduled to resume following the holiday break, leaving Southeast Asian regional liquidity marginally thinner during the morning session.
Outlook: Key Factors and Market Drivers to Monitor
As Monday’s trading session advances across the Asia-Pacific basin, international and Israeli institutional investors will monitor whether Hong Kong’s strong rally can generate positive spillover into lagging markets or if mainland China’s decline will exert broader downward pressure. A primary focus will be tracking whether the KOSPI and the Sensex sustain their morning gains into the closing bell, alongside any potential stabilization in the SSE Composite Index. Market participants will also monitor fluctuations in the yen and Australian dollar, shifting global sovereign bond yields, and upcoming corporate earnings and economic releases scheduled throughout the first week of November. For global portfolio managers, the essential consideration is assessing whether the pronounced divergence between onshore Chinese shares and offshore regional leaders represents a short-term positioning mismatch or the beginning of a broader capital rotation.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- orshu
- •
- 7 Min Read
- •
- ago 13 minutes
SKN | Tel Aviv Stocks Post Broad Gains as TA-SME60 Rallies and Positive Breadth Lifts Major Indices
Trading across the Tel Aviv Stock Exchange reflects steady upward momentum during active market hours, with all eight headline equity
- ago 13 minutes
- •
- 7 Min Read
Trading across the Tel Aviv Stock Exchange reflects steady upward momentum during active market hours, with all eight headline equity
- orshu
- •
- 7 Min Read
- •
- ago 5 hours
SKN | Jobs Super-Week and Apple Earnings to Dictate Early-November Market Momentum
Global financial markets launch into the first full week of November 2026 facing a formidable intersection of corporate mega-cap results
- ago 5 hours
- •
- 7 Min Read
Global financial markets launch into the first full week of November 2026 facing a formidable intersection of corporate mega-cap results

- Lior mor
- •
- 6 Min Read
- •
- ago 15 hours
SKN | OPEC+ Holds December Oil Targets Steady as Tougher 2027 Quota Decisions Loom
OPEC+ oil-producing countries kept their December production targets unchanged on Sunday, reinforcing expectations that the group will avoid further
- ago 15 hours
- •
- 6 Min Read
OPEC+ oil-producing countries kept their December production targets unchanged on Sunday, reinforcing expectations that the group will avoid further
- omer bar
- •
- 7 Min Read
- •
- ago 24 hours
SKN | KOSPI Slides 3.48% to 5,730.74, Despite Retaining a 4.78% Weekly Gain
The KOSPI Composite Index (^KS11) experienced a significant setback on October 30, falling 3.48%, equivalent to 206.92 points, to
- ago 24 hours
- •
- 7 Min Read
The KOSPI Composite Index (^KS11) experienced a significant setback on October 30, falling 3.48%, equivalent to 206.92 points, to
