





- sagi habasov
- •
- 6 Min Read
- •
- 13 minutes ago


Key Points
- The TA-RealEstate Index gained 1.65% over the week, extending its short-term recovery and finishing the latest session at 1,405.26.
- The index remains under pressure over longer periods, down 3.28% over three months and 10.32% over six months.
- Interest rates, financing costs, property demand and the broader economic outlook will be important factors in determining whether the recovery can continue.
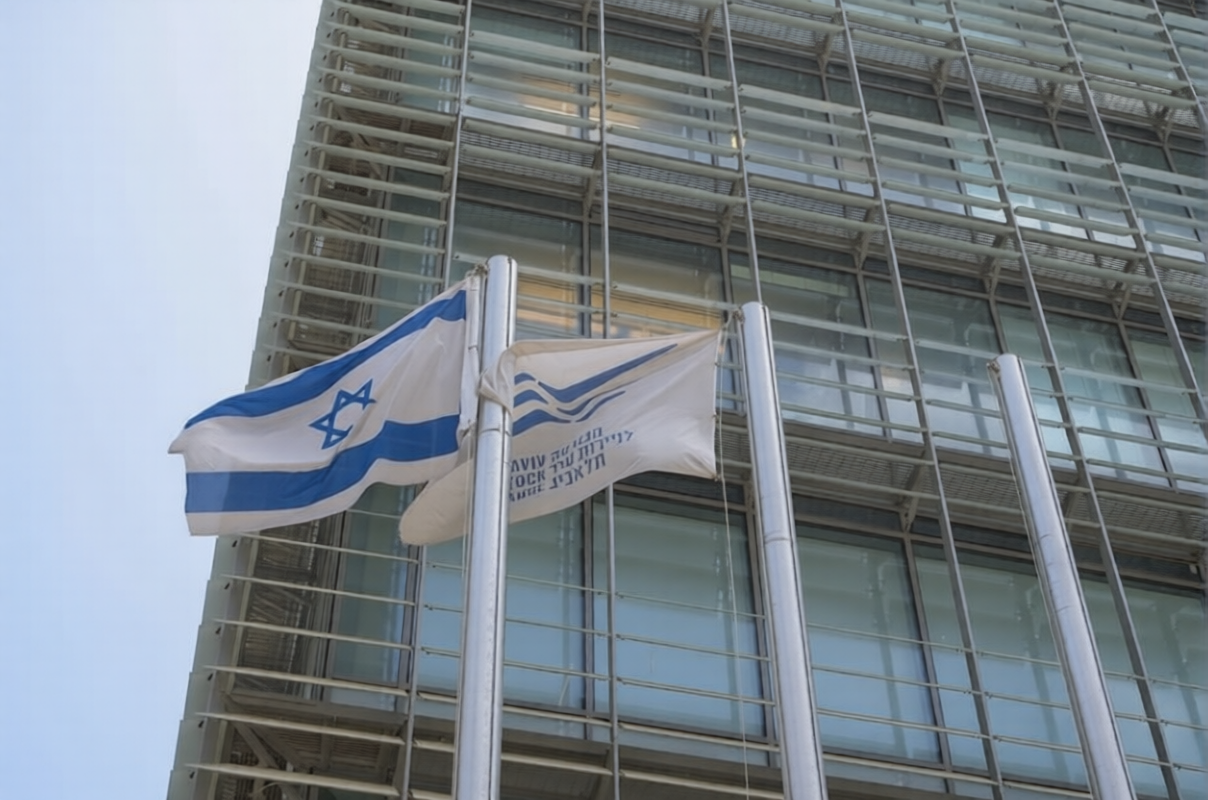
The Israeli real estate sector recorded a positive week, with the TA-RealEstate Index rising 1.65% to 1,405.26, according to the supplied market data. The advance offers a sign of near-term resilience after a difficult period for property-related shares, although the index’s weaker performance over longer timeframes suggests that a durable recovery has yet to be established.
Weekly Gains Signal a Potential Stabilization
The index rose 0.18% in the latest session, adding to its weekly advance and bringing its one-month gain to 3.28%. The recent improvement may indicate that investors are reassessing valuations and the sector’s sensitivity to financing conditions after an extended period of weakness. However, a short-term rebound does not necessarily signal a sustained change in market direction.
Trading activity reached approximately 8.03 million units, compared with a three-month average volume of around 12.28 million. The lower activity suggests that the advance occurred without a notable increase in trading volume relative to the recent average. That does not invalidate the gain, but it leaves open the question of whether stronger investor participation will emerge if prices continue to recover.
Longer-Term Performance Highlights Structural Challenges
Despite the weekly improvement, the index remains down 3.28% over three months and 10.32% over six months. Its one-year change stands at approximately negative 4.15%, underscoring the gap between the recent recovery and the sector’s broader performance. Over five years, however, the index has gained 30.68%, demonstrating that longer-term returns remain positive despite the more recent setback.
Israeli real estate companies are particularly sensitive to borrowing costs because property development and investment often require substantial financing. Interest rates influence developers’ funding expenses, buyers’ mortgage affordability and the yields investors demand from property-related assets. Elevated financing costs can delay projects, weaken transaction activity and put pressure on valuations, while improving credit conditions could gradually support demand. The pace of any improvement will depend on the wider economic environment and the financial position of individual companies.
Outlook Depends on Rates, Demand and Financing Conditions
The next phase for the TA-RealEstate Index will likely depend on whether the recent gains are accompanied by improving fundamentals. Investors will be watching interest-rate expectations, mortgage activity, property transactions, construction costs and company disclosures for evidence that sector conditions are stabilizing. A more supportive financing environment could improve sentiment, but any easing in rates may take time to translate into stronger demand and better earnings.
Risks remain, including persistent inflation, currency volatility, weaker-than-expected economic growth and geopolitical uncertainty affecting Israel’s risk premium and financing conditions. For international investors, exchange-rate movements may also influence returns when Israeli assets are measured in foreign currencies. The weekly advance is an encouraging near-term development, but confirmation of a broader recovery will require sustained performance alongside stronger market participation and measurable improvement in real estate fundamentals.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- orshu
- •
- 6 Min Read
- •
- ago 38 minutes
SKN | TA Banks 5 Weekly Review: Israeli Banking Stocks Pull Back as Investors Weigh Growth and Valuation Risks
The TA Banks 5 index ended the week ending October 23, 2026, under pressure, highlighting a pause in the
- ago 38 minutes
- •
- 6 Min Read
The TA Banks 5 index ended the week ending October 23, 2026, under pressure, highlighting a pause in the

- Ronny Mor
- •
- 6 Min Read
- •
- ago 1 hour
SKN | TA-SME60 Weekly Review: Israeli Small-Caps Remain Under Pressure as Medium-Term Returns Weaken
The TA-SME60 ended the week of October 19–23, 2026, at 1,272.44 points, down 2.06 points, or 0.16%, in the
- ago 1 hour
- •
- 6 Min Read
The TA-SME60 ended the week of October 19–23, 2026, at 1,272.44 points, down 2.06 points, or 0.16%, in the

- omer bar
- •
- 6 Min Read
- •
- ago 2 hours
SKN | KOSPI Recovers Late Losses as Tech Rebound Tempers a Volatile Week
South Korea’s benchmark KOSPI Composite Index finished the week ending October 23, 2026, on an uneven footing, posting a
- ago 2 hours
- •
- 6 Min Read
South Korea’s benchmark KOSPI Composite Index finished the week ending October 23, 2026, on an uneven footing, posting a

- Lior mor
- •
- 6 Min Read
- •
- ago 2 hours
SKN | Japanese Yen Index Firms on Monetary Shift Speculation Despite Late Consolidation
The Japanese Yen Currency Index finished the week ending October 23, 2026, on a firm footing, posting a five-day
- ago 2 hours
- •
- 6 Min Read
The Japanese Yen Currency Index finished the week ending October 23, 2026, on a firm footing, posting a five-day

