
- Arik Arkadi Sluzki
- •
- 9 Min Read
- •
- 50 seconds ago
Key Points
- U.S. equities recovered during the week, with the S&P 500 gaining 2.5%, while semiconductor stocks rebounded despite significant pressure on Nvidia.
- Jensen Huang’s departure as Nvidia CEO intensified uncertainty across the AI sector, while investors rotated toward other semiconductor companies.
- Persistent inflation pushed Treasury yields higher and strengthened expectations of a Federal Reserve rate increase in December.
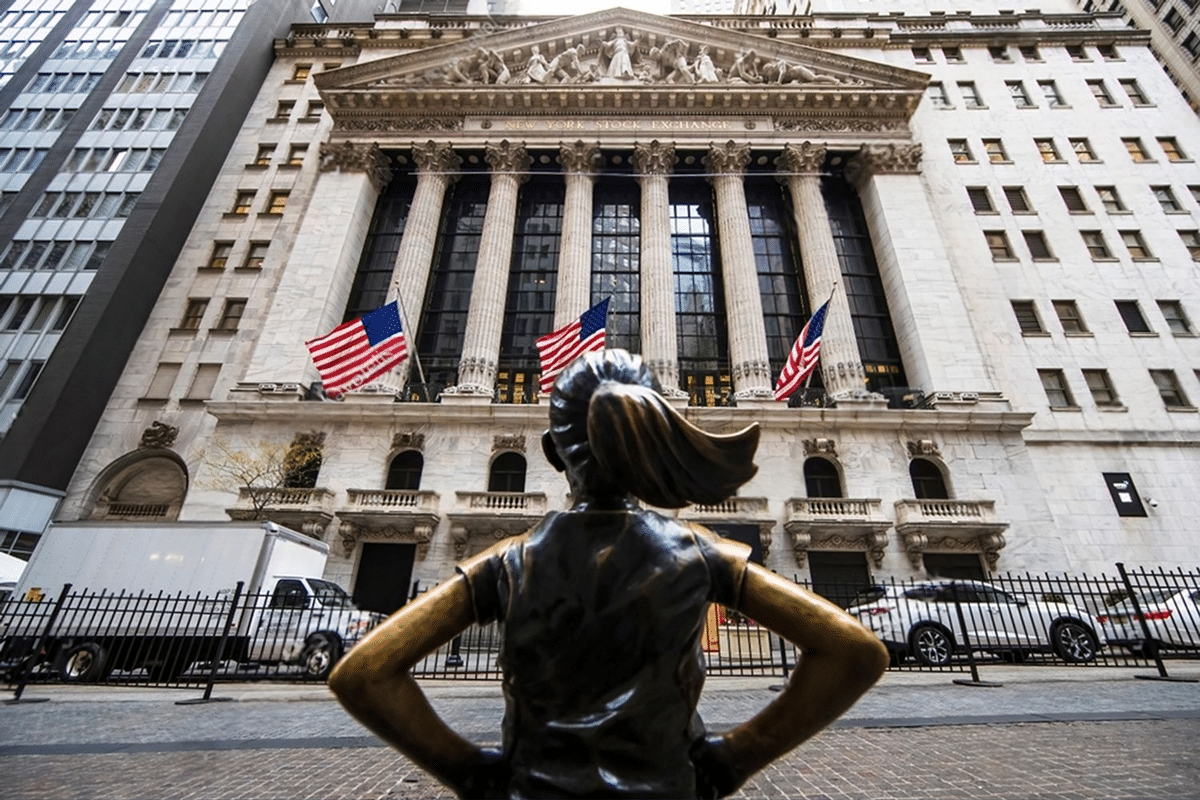
U.S. financial markets ended the week with a recovery in equities, but the gains concealed a significant shift in market leadership. Investors moved capital across technology stocks and other sectors as uncertainty surrounding the artificial intelligence industry coincided with renewed inflation concerns and rising Treasury yields.
Equity Markets Recover as Semiconductor Leadership Changes
The major U.S. equity benchmarks recorded weekly gains, with the S&P 500 rising 2.5%, the Nasdaq Composite gaining 2.3%, the Dow Jones Industrial Average advancing 2.1%, and the Russell 2000 increasing 1.4%. However, the recovery was accompanied by a notable rotation within the technology sector, suggesting that investors were becoming more selective about their exposure to the AI industry.
The semiconductor sector recorded particularly strong gains. The Philadelphia Semiconductor Index rose approximately 9%, while Advanced Micro Devices and Broadcom gained 19% and 18%, respectively, according to the supplied weekly market figures. Nvidia, by contrast, came under substantial pressure following the resignation of longtime chief executive Jensen Huang. The company’s leadership transition introduced uncertainty around the strategic direction of one of the most influential businesses in the global AI infrastructure market.
Nvidia’s chief financial officer, Colette Kress, assumed the role of interim CEO. The implications extend beyond Nvidia itself because the company is closely connected to semiconductor suppliers, cloud infrastructure providers, and businesses investing heavily in AI computing capacity. The Associated Press reported that the developments surrounding Huang’s departure erased nearly $600 billion in Nvidia market capitalization during the week. The episode also highlighted the concentration risk associated with major technology companies that have accounted for a substantial share of U.S. equity market performance.
Inflation and Rising Treasury Yields Complicate the Recovery
Despite the improvement in equity prices, the bond market reflected a more challenging macroeconomic environment. The supplied market recap showed the two-year Treasury yield rising approximately 35 basis points during the week, while the 10-year yield increased around 30 basis points, moving back above 5.15%. Higher yields can increase financing costs for companies and households while placing additional pressure on equity valuations, particularly for businesses whose expected earnings are concentrated further into the future.
October’s inflation figures reinforced concerns that price pressures remain persistent. The U.S. Bureau of Labor Statistics reported that headline consumer prices increased 0.4% month over month, while core CPI, which excludes food and energy, rose 0.3%. Core inflation recorded the same monthly increase in August and September, indicating that underlying price pressures had not yet demonstrated a clear moderation. The usual year-over-year comparison was unavailable because the federal government shutdown prevented the collection of October 2025 CPI data.
These figures have materially changed expectations for monetary policy. Reuters reported that market participants had moved to fully price in a 25-basis-point Federal Reserve rate increase in December, compared with a 74% probability the previous week. The prospect of tighter monetary policy contributed to the stronger U.S. dollar and added another source of uncertainty for global financial markets.
Global Asset Allocation Signals a More Selective Market
The movement across asset classes reflected the changing balance between risk appetite and monetary policy expectations. According to the supplied weekly figures, the U.S. Dollar Index gained 1.1%, while gold declined 4.8% and silver fell 6.2%. Bitcoin lost 9.6%, indicating that digital assets remained under pressure as financial conditions tightened. West Texas Intermediate crude oil declined 2.0%, although energy markets continued to experience volatility amid geopolitical uncertainty.
Equity fund flows, however, suggested that investors were not abandoning the stock market. The supplied market data showed approximately $51 billion in global equity fund inflows during the week ending November 11, representing the largest weekly intake since September. European equity funds accounted for approximately $35.1 billion, their strongest weekly inflow since June 2021. The same market recap indicated that the S&P 493 gained almost 4%, while the Magnificent Seven finished lower overall, pointing to broader participation beyond the largest technology companies.
This divergence is important because it suggests that the equity recovery was not solely dependent on renewed strength in the largest AI stocks. Nevertheless, strong fund inflows do not necessarily establish that investors have become more confident in the economic outlook. They may also reflect portfolio repositioning following recent volatility and a search for opportunities outside the most crowded technology positions.
Looking ahead, the sustainability of the recovery will depend on whether corporate earnings can justify current valuations while inflation and borrowing costs remain elevated. Nvidia’s upcoming earnings report and Anthropic’s anticipated public listing are expected to provide important tests of investor confidence in the AI sector. At the same time, further inflation readings, Federal Reserve communications, Treasury yields, and the breadth of equity market participation will remain central indicators. For globally diversified investors, including those managing international exposure from Israel, the interaction between U.S. interest rates, dollar strength, and technology-sector concentration will remain an important consideration in assessing portfolio risk.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- Ronny Mor
- •
- 8 Min Read
- •
- ago 41 seconds
SKN | US Layoff Announcements Fall 71% in October, but Economic Pressures Remain a Concern
U.S. employers announced substantially fewer job cuts in October, offering evidence that the pace of corporate workforce reductions has
- ago 41 seconds
- •
- 8 Min Read
U.S. employers announced substantially fewer job cuts in October, offering evidence that the pace of corporate workforce reductions has

- orshu
- •
- 6 Min Read
- •
- ago 1 hour
SKN | Americas Market Overview: Nasdaq Falls 0.91% as CBOE Volatility Index Rises 3.21%
U.S. Equities Show Diverging Performance U.S. equity benchmarks moved in different directions, with technology-oriented stocks experiencing the steepest decline among
- ago 1 hour
- •
- 6 Min Read
U.S. Equities Show Diverging Performance U.S. equity benchmarks moved in different directions, with technology-oriented stocks experiencing the steepest decline among

- Arik Arkadi Sluzki
- •
- 8 Min Read
- •
- ago 1 hour
SKN | Institutional Investors Build Near-Record Bullish Exposure to U.S. Equity Futures: Is the Market Becoming Overcrowded?
Institutional investors have accumulated substantial bullish exposure to U.S. equity-index futures, with reported net long positioning approaching historical extremes.
- ago 1 hour
- •
- 8 Min Read
Institutional investors have accumulated substantial bullish exposure to U.S. equity-index futures, with reported net long positioning approaching historical extremes.
- Ronny Mor
- •
- 8 Min Read
- •
- ago 1 hour
SKN | U.S. Household Debt Reaches $19.1 Trillion: Is Rising Borrowing Becoming a Consumer Credit Risk?
U.S. household borrowing continued to expand in the third quarter of 2026, pushing total outstanding debt to approximately $19.1
- ago 1 hour
- •
- 8 Min Read
U.S. household borrowing continued to expand in the third quarter of 2026, pushing total outstanding debt to approximately $19.1