
- omer bar
- •
- 7 Min Read
- •
- 22 seconds ago
Key Points
- USD/JPY ended the five-day period near 157.99, down approximately 0.14% on the chart’s selected timeframe.
- The exchange rate experienced sharp intraperiod swings, briefly moving above 158.80 before retreating toward 157.70.
- Interest-rate expectations, central-bank signals and potential intervention concerns remain important variables for the yen and broader currency markets.
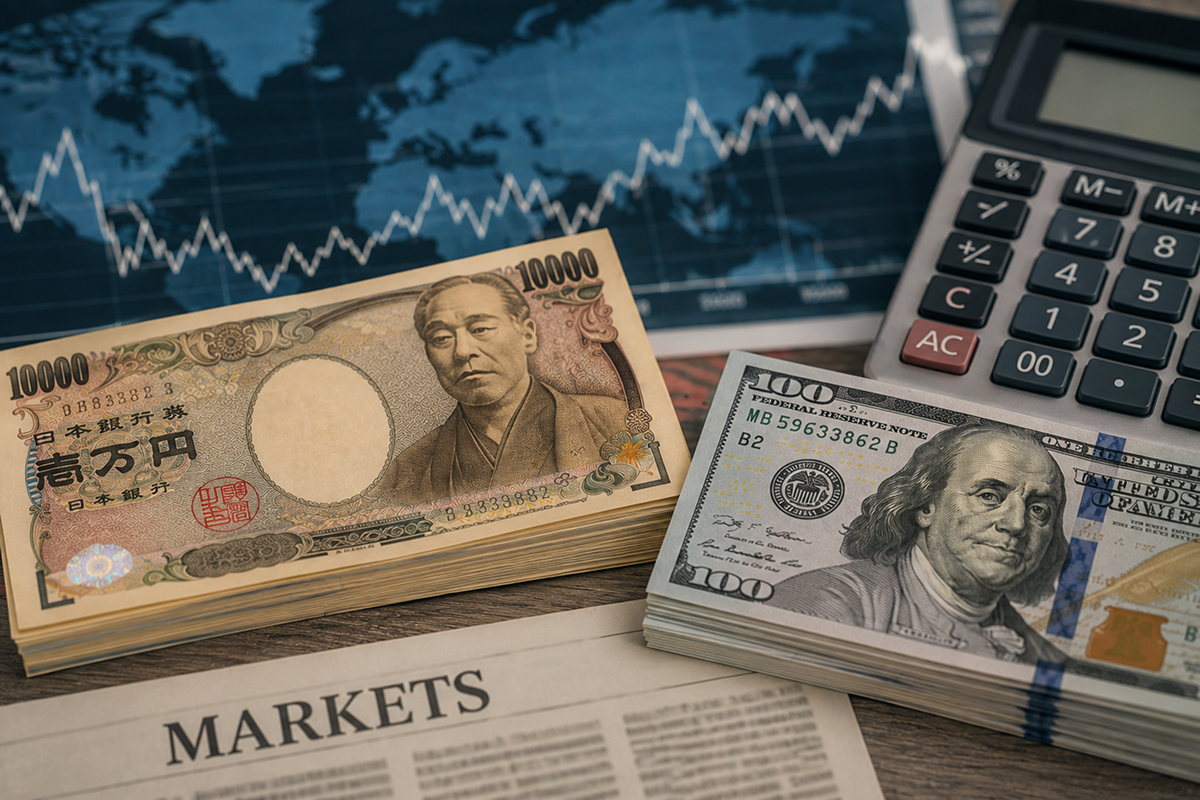
The U.S. dollar traded close to 158 yen at the end of the week of October 12–16, 2026, with the supplied chart showing a modest five-day decline despite substantial fluctuations during the period. The relatively small net move masks meaningful changes in momentum, highlighting how currency markets can remain sensitive to monetary-policy expectations and shifts in risk appetite even when the weekly result appears limited.
Sharp Fluctuations Define the Week
USD/JPY stood at 157.9870 in the latest reading shown on October 16, gaining 0.01% in the latest displayed session. However, the five-day performance indicator registered a decline of approximately 0.14%. The chart shows the pair moving around the 158.00 level before experiencing a pronounced drop, followed by uneven trading at lower levels. An earlier move toward approximately 158.90 was followed by a retreat, illustrating the difficulty of sustaining upward momentum throughout the period.
The displayed daily range on October 16 was 157.6870–158.3400, while the reported 52-week range extended from 150.2860 to 163.9790. These figures place the exchange rate within the upper portion of its annual range, although the latest weekly movement alone does not establish a durable directional trend. The distinction between intraday volatility and sustained appreciation remains important when interpreting short-term currency performance.
Monetary Policy Remains Central to the Outlook
The dollar-yen exchange rate is particularly sensitive to differences in expected monetary policy between the United States and Japan. Changes in Treasury yields, expectations for Federal Reserve decisions and the Bank of Japan’s policy trajectory can alter the relative attractiveness of dollar- and yen-denominated assets. If market participants anticipate a narrower interest-rate differential, the yen could receive support. Conversely, persistently higher U.S. yields relative to Japanese yields could help sustain demand for the dollar.
The chart does not independently establish which factor drove the weekly decline. Investors should therefore distinguish observed price movements from explanations that require confirmation through bond yields, central-bank communications and economic releases. Potential Japanese official intervention is another consideration when the yen weakens sharply, although the supplied data does not confirm any intervention during the period.
Implications for Global and Israeli Investors
For international investors, USD/JPY movements can affect currency-hedging costs, the translated value of overseas holdings and returns from Japanese assets when measured in another currency. Currency fluctuations can also influence the competitiveness of Japanese exporters and the performance of companies with substantial overseas revenues, although the impact varies by business model and hedging strategy.
For Israeli investors, the dollar-yen rate provides useful information about global currency conditions but should not be treated as a direct indicator of the shekel’s direction. USD/ILS and EUR/ILS respond to their own domestic, interest-rate and geopolitical drivers. Currency volatility can also complicate comparisons between local-currency returns and the underlying performance of international investments.
Looking ahead, the key indicators are the relative direction of U.S. and Japanese yields, upcoming central-bank signals, inflation and employment data, and any official comments concerning excessive yen volatility. A sustained move above 158 would suggest renewed dollar strength, while a break below the recent 157.70 area could indicate further near-term pressure on the pair. Neither outcome is assured, and the next week’s direction will depend on whether macroeconomic developments reinforce or reverse the latest trading pattern.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- Lior mor
- •
- 6 Min Read
- •
- ago 54 minutes
SKN | TA-35 Rallies 4.01% for the Week as Israeli Equities Extend Their Advance
The Tel Aviv equity market ended the week with a strong advance in large-cap stocks, as the TA-35 index
- ago 54 minutes
- •
- 6 Min Read

The Tel Aviv equity market ended the week with a strong advance in large-cap stocks, as the TA-35 index

- Arik Arkadi Sluzki
- •
- 6 Min Read
- •
- ago 1 hour
SKN | TA-125 Gains 4.22% in a Week as Israeli Equities Rebound, but Recovery Risks Remain
The Tel Aviv TA-125 index delivered a strong weekly recovery, gaining 4.22% between October 12 and October 16
- ago 1 hour
- •
- 6 Min Read

The Tel Aviv TA-125 index delivered a strong weekly recovery, gaining 4.22% between October 12 and October 16

- sagi habasov
- •
- 6 Min Read
- •
- ago 3 hours
SKN | TA-RealEstate Rallies 8.95% in a Week, but Longer-Term Weakness Keeps Israeli Property Stocks Under Pressure
The TA-RealEstate Index recorded a strong weekly recovery, rising 8.95% to 1,382.39, with the latest session adding 34.86 points,
- ago 3 hours
- •
- 6 Min Read
The TA-RealEstate Index recorded a strong weekly recovery, rising 8.95% to 1,382.39, with the latest session adding 34.86 points,

- orshu
- •
- 6 Min Read
- •
- ago 4 hours
SKN | TA Banks 5 Gains 5.13% on the Week as Israeli Bank Stocks Approach Key Resistance Levels
The TA Banks 5 index recorded a strong weekly advance, rising 5.13% to 8,908.43, according to the supplied
- ago 4 hours
- •
- 6 Min Read
The TA Banks 5 index recorded a strong weekly advance, rising 5.13% to 8,908.43, according to the supplied