




- orshu
- •
- 7 Min Read
- •
- 1 minute ago


Key Points
- The Hang Seng Index (^HSI) declined 1.27%, or 315.12 points, to close at 24,481.86 on November 6, 2026, while recording a 5.10% gain over the five-session period.
- The index opened at 24,404.62 and traded between 24,349.30 and 24,740.18, compared with the previous close of 24,797.00.
- Despite Friday's retreat, the benchmark remained within its 52-week range of 22,518.00–28,056.10, preserving most of its weekly advance.
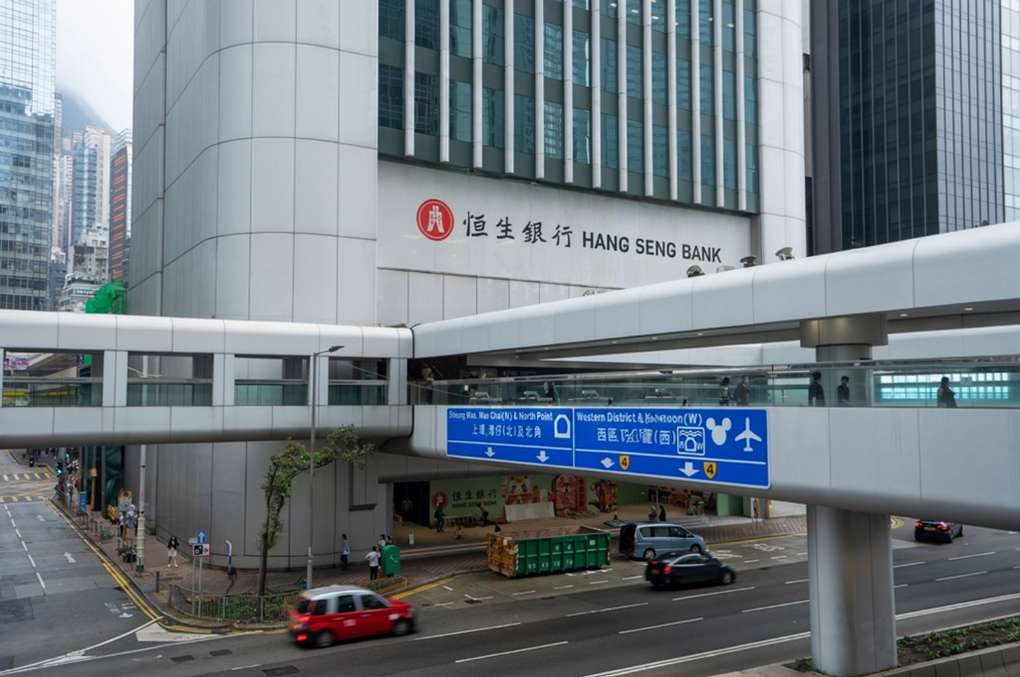
The Hang Seng Index ended Friday’s session lower, falling 1.27% to 24,481.86. However, the decline did little to erase the benchmark’s strong weekly performance, with the index still up 5.10% over five trading sessions. Its relative resilience contrasted with the sharper late-week weakness across several major international equity markets, although the available figures alone do not establish the specific factors behind that divergence.
For institutional investors in Israel and globally, the combination of a substantial weekly advance and a final-session pullback highlights the importance of distinguishing short-term profit-taking from a broader change in market direction when assessing Greater China exposure.
Friday Pullback Follows Strong Weekly Advance
The Hang Seng opened at 24,404.62 and moved within a range of 24,349.30–24,740.18 before settling at 24,481.86. The decline of 315.12 points from Thursday’s close of 24,797.00 represented a moderate retreat after the index’s recent advance.
Despite the daily loss, the benchmark retained a 5.10% five-session gain. Its closing level remained within the middle portion of its reported 52-week range of 22,518.00–28,056.10, indicating that the index had not approached its annual low despite Friday’s weakness.
The reported volume figures require qualification. The Hang Seng Index itself is a calculated benchmark rather than a directly traded security, meaning that zero index-level volume is not an indication of an absence of trading activity. The stated three-month average of 2,807,690,476 shares should therefore not be compared directly with the index’s volume reading.
Greater China Exposure and Technology Sentiment Remain in Focus
Investor positioning across Chinese technology companies, consumer platforms, electric vehicle manufacturers and financial institutions remains relevant to the Hang Seng’s broader performance. Expectations surrounding Beijing’s fiscal policy, liquidity conditions and corporate earnings can influence sentiment toward Hong Kong-listed companies and the wider Greater China market.
Mainland investment flows through the southbound Stock Connect channel are another factor that market participants may monitor when assessing demand for Hong Kong-listed shares. However, confirming that these flows or specific policy expectations drove the index’s weekly advance would require supporting flow data and contemporaneous market reporting.
The Hang Seng’s composition also means that changes in sentiment toward large technology and consumer companies can have a meaningful influence on its direction. This remains particularly relevant as global investors reassess growth valuations and exposure to Asian markets.
Monetary Policy and Currency Considerations for International Investors
Hong Kong’s monetary framework remains closely linked to U.S. interest-rate conditions through its Linked Exchange Rate System. Consequently, Federal Reserve policy expectations and Hong Kong Monetary Authority liquidity management can influence local financing conditions and market sentiment.
Developments in mainland China’s economy, property sector and policy environment also remain important considerations. For Israeli institutional investors, movements in USD/HKD and HKD/ILS can affect the shekel-denominated value of Hong Kong equity holdings, while currency-hedging costs may influence the overall return on international allocations.
The Hang Seng’s near-term direction will depend on whether its recent weekly strength can be sustained amid changing global risk appetite and developments in China’s domestic economy. The 24,349.30 intraday low represents an immediate reference point from Friday’s session, while the 22,518.00 52-week low provides a longer-term reference within the reported annual range. On the upside, a sustained recovery above the 24,797.00 previous close could indicate renewed short-term momentum. Further progress will likely depend on corporate earnings, policy implementation in Beijing and global liquidity conditions, while trade tensions and renewed weakness in international equities remain potential sources of volatility.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- Ronny Mor
- •
- 7 Min Read
- •
- ago 19 minutes
SKN | Nikkei 225 Plunges 5.96% to 57,434.77, Extending Weekly Loss to 9.25% Amid Technology Selloff
The Nikkei 225 ended the week on November 6, 2026, under significant pressure, falling 5.96% to 57,434.77. The decline
- ago 19 minutes
- •
- 7 Min Read
The Nikkei 225 ended the week on November 6, 2026, under significant pressure, falling 5.96% to 57,434.77. The decline
- omer bar
- •
- 7 Min Read
- •
- ago 39 minutes
SKN | Euro Currency Index Falls 0.59% to 111.53, Weekly Loss Reaches 0.12% as Support Nears
The Euro Currency Index ended the week lower, declining 0.59% to 111.53 on Friday, November 6. The retreat reversed
- ago 39 minutes
- •
- 7 Min Read
The Euro Currency Index ended the week lower, declining 0.59% to 111.53 on Friday, November 6. The retreat reversed

- Lior mor
- •
- 7 Min Read
- •
- ago 2 hours
SKN | British Pound Currency Index Falls 0.73% to 133.52, Extending Weekly Loss to 0.29%
The British Pound Currency Index ended the week lower, falling 0.73% to 133.52 on Friday, November 6. The decline
- ago 2 hours
- •
- 7 Min Read
The British Pound Currency Index ended the week lower, falling 0.73% to 133.52 on Friday, November 6. The decline

- Arik Arkadi Sluzki
- •
- 8 Min Read
- •
- ago 2 hours
SKN | CAC 40 Falls 0.81% to 8,139.00, but Retains 2.13% Weekly Gain
The CAC 40 ended Friday's session lower, declining 0.81% to 8,139.00, as a late-week pullback moderated gains accumulated during
- ago 2 hours
- •
- 8 Min Read
The CAC 40 ended Friday's session lower, declining 0.81% to 8,139.00, as a late-week pullback moderated gains accumulated during
