





- orshu
- •
- 8 Min Read
- •
- 5 minutes ago


Key Points
- U.S. markets delivered a mixed week, with the Nasdaq Composite gaining 2.06%, S&P 500 rising 1.21% and Dow Jones increasing 0.28%, while the Russell 2000 fell 0.80%.
- Asian equities posted some of the strongest gains, led by KOSPI rising 5.44% and Nikkei 225 gaining 3.82%, while Shanghai increased 0.33% and Hang Seng declined 0.97%.
- Israeli equities were more mixed, with TA-35 falling 1.12% while TA-125 gained 0.25%, as geopolitical and domestic factors continued to differentiate the Tel Aviv market from global technology-led gains.
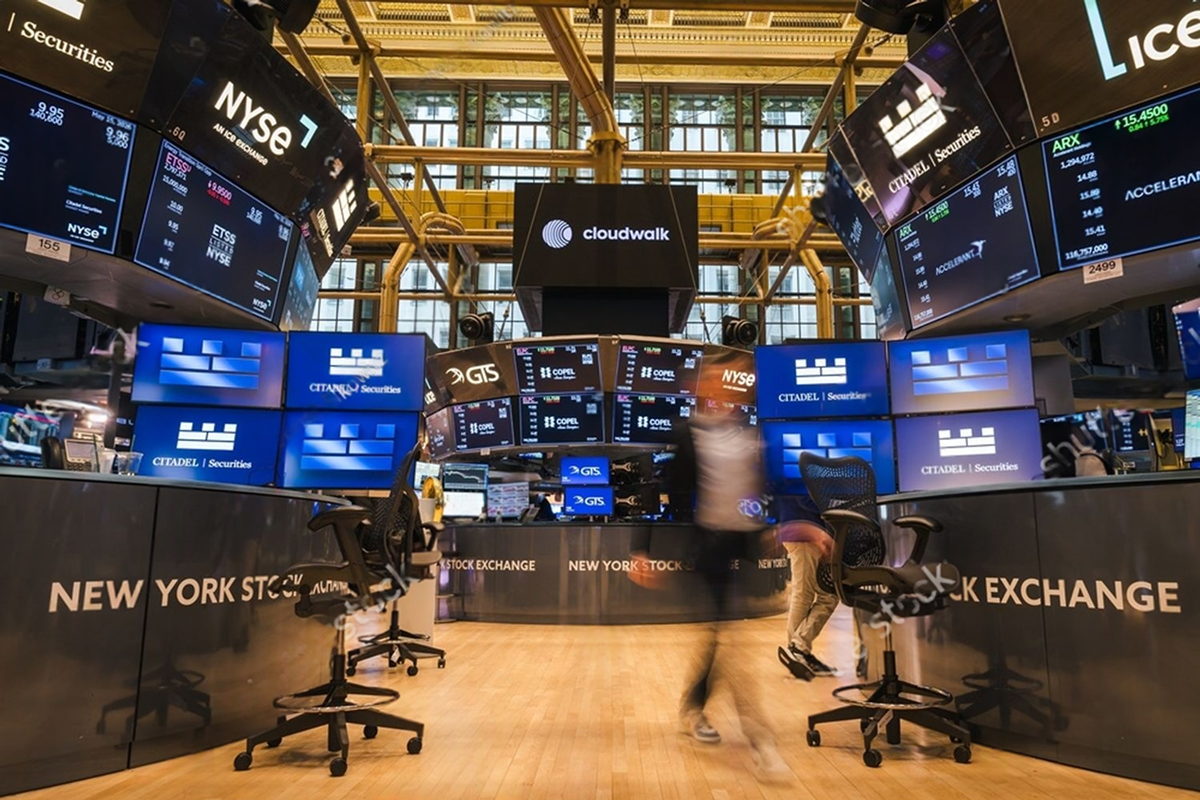
The defining feature of the September 21 to September 25 trading week was the widening gap between technology-led equity strength and broader market pressure. The Nasdaq Composite gained 2.06% and the S&P 500 rose 1.21%, even as Treasury yields climbed and oil remained a major inflation risk, while the Russell 2000 fell 0.80%. The result was a market increasingly willing to pay for AI-related growth while remaining cautious about interest-rate-sensitive parts of the economy.
AI Leadership Keeps U.S. Equities Resilient
U.S. markets finished the week with a clear technology bias. The Nasdaq Composite gained 2.06%, compared with a 1.21% rise in the S&P 500 and a 0.28% increase in the Dow Jones Industrial Average. The Russell 2000 moved in the opposite direction, falling 0.80%, highlighting the difference between demand for large-cap technology exposure and the more rate-sensitive smaller-company segment.
Reuters reported that enthusiasm around artificial intelligence remained a major driver, while falling oil prices temporarily eased some inflation concerns. Nasdaq also reached record levels during the week as investors responded to developments involving AI companies and semiconductor demand.
Higher Yields Challenge the Broader Market
The equity rally unfolded against a more difficult fixed-income backdrop. U.S. Treasury yields rose during the week, with the 10-year yield reaching its highest level since 2007 on September 23 after data showed U.S. business activity accelerating sharply. The flash U.S. Composite PMI rose to 58.4 in September, its highest reading since July 2021, reinforcing concerns that stronger economic activity could keep inflation pressures persistent.
The U.S. Dollar Index gained 0.60% in the supplied five-day data. This combination of firmer yields and a stronger dollar helps explain why the market’s gains were concentrated in particular sectors rather than spread evenly across equities. Reuters also reported that global equity funds attracted $44.1 billion during the week, the strongest weekly inflow since early July, as renewed AI optimism and lower oil prices outweighed concerns about rising bond yields.
Asia Outperforms as Semiconductor Momentum Returns
Asia delivered the strongest regional performance in the supplied data. The KOSPI gained 5.44%, while the Nikkei 225 rose 3.82%. The Shanghai Composite increased 0.33%, but the Hang Seng Index declined 0.97%. South Korea’s performance is particularly significant because semiconductor exports are a major transmission channel between global AI investment and the domestic equity market. Reuters reported that South Korean semiconductor shipments surged 259.4% year over year in early September, supporting the technology-led rally across the region.
Japan also benefited from renewed technology and growth-sector demand, although currency and monetary-policy considerations remained important. The divergence between the Hang Seng and mainland Chinese market suggests that regional performance was not simply a broad China-and-Asia rally, but reflected differences in sector composition and investor exposure.
Europe and Israel Reflect a More Uneven Risk Environment
European performance was modestly positive overall in the supplied five-day figures. MSCI Europe fell 1.04%, while the FTSE 100 gained 0.34%, CAC 40 rose 0.16% and DAX increased 0.41%. The mixed results came as European markets continued to balance higher borrowing costs, energy risks and renewed interest in technology shares. Reuters reported that European equities benefited early in the week from falling oil prices, while technology and banking shares helped lift the broader regional market.
In Israel, the TA-35 fell 1.12%, while the broader TA-125 gained 0.25% in the supplied five-day data. The divergence indicates that performance within the Tel Aviv market was uneven rather than reflecting a uniform move across Israeli equities. The supplied index data do not establish whether banks, defense companies, institutional flows or another specific sector drove the difference, so attributing the weekly result to one group would go beyond the available evidence.
The coming week brings a more direct test of the market’s ability to absorb strong growth without a renewed rate shock. U.S. employment data and inflation indicators are scheduled to provide fresh evidence on the Federal Reserve’s policy path, while European inflation data will shape expectations on the other side of the Atlantic. Reuters identified payrolls and U.S. and euro-zone inflation as the key events for the final week of September.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- orshu
- •
- 7 Min Read
- •
- ago 1 week
SKN | Global Markets Weekly Performance Review: September 14 to September 18, 2026
The week of September 14 to September 18 showed a sharp divergence between global markets. While the Dow Jones
- ago 1 week
- •
- 7 Min Read
The week of September 14 to September 18 showed a sharp divergence between global markets. While the Dow Jones
- orshu
- •
- 7 Min Read
- •
- ago 2 weeks
SKN | Global Markets Weekly Performance Review: September 07 to September 11, 2026
The week exposed a growing conflict between inflation, energy security and monetary policy. U.S. equities absorbed another rise in
- ago 2 weeks
- •
- 7 Min Read
The week exposed a growing conflict between inflation, energy security and monetary policy. U.S. equities absorbed another rise in
- orshu
- •
- 6 Min Read
- •
- ago 3 weeks
SKN | Global Markets Weekly Performance Review: August 31 to September 4, 2026
The week exposed a striking split in global markets: the macro backdrop became more difficult, but U.S. equities barely
- ago 3 weeks
- •
- 6 Min Read
The week exposed a striking split in global markets: the macro backdrop became more difficult, but U.S. equities barely
- orshu
- •
- 7 Min Read
- •
- ago 4 weeks
SKN | Global Markets Weekly Performance Review: August 24 to August 28, 2026
The central feature of the trading week from August 24 to August 28, 2026, was not a broad global
- ago 4 weeks
- •
- 7 Min Read
The central feature of the trading week from August 24 to August 28, 2026, was not a broad global

