





- orshu
- •
- 7 Min Read
- •
- 4 weeks ago


Key Points
- U.S. equities ended the week lower, with the Dow Jones falling 2.07%, S&P 500 declining 1.17%, Nasdaq Composite falling 0.94% and Russell 2000 dropping 2.17%.
- Asia recorded some of the sharpest declines, led by the Nikkei 225 falling 3.60% and Hang Seng Index declining 3.30%, while European markets also weakened broadly.
- Israeli equities were relatively resilient, with TA-35 falling 0.33% and TA-125 declining 1.40%, materially outperforming most major international benchmarks.
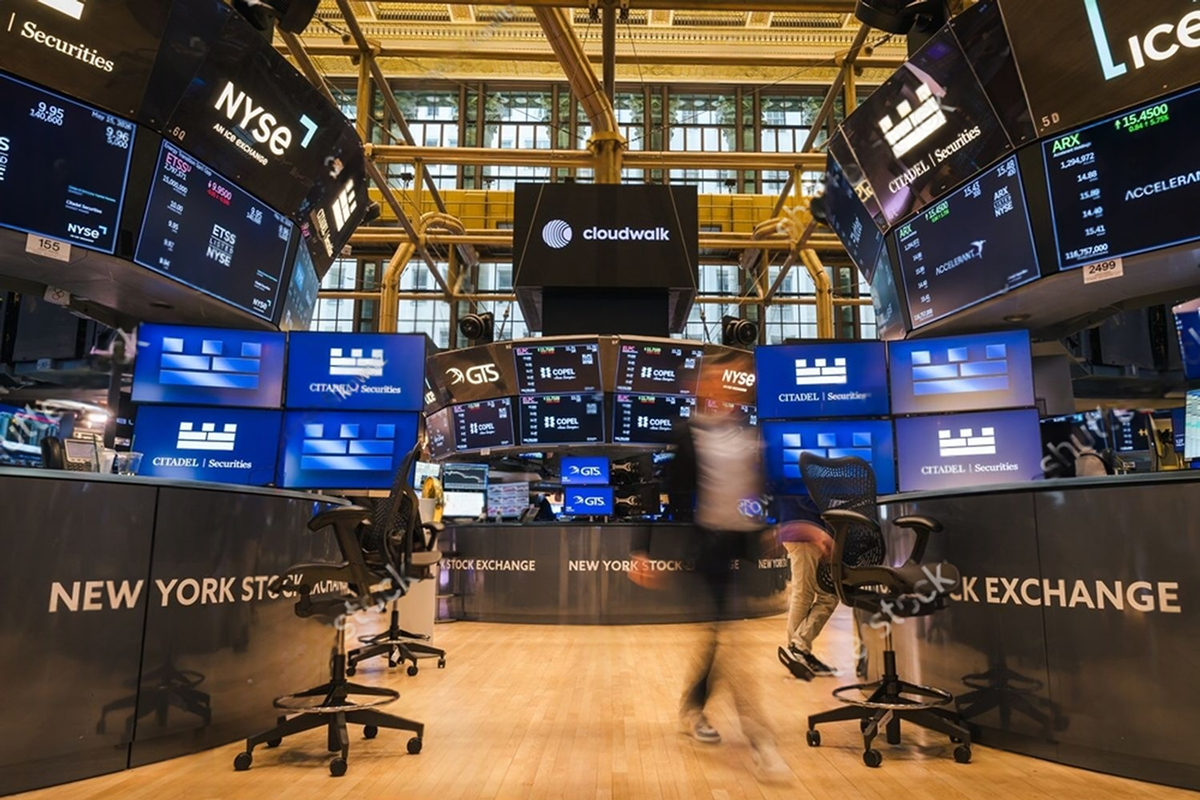
The week exposed a growing conflict between inflation, energy security and monetary policy. U.S. equities absorbed another rise in oil prices and higher Treasury yields, while Asian and European markets suffered larger losses; yet the relatively limited decline in Wall Street and Israeli equities showed that investors were not responding uniformly to the same macro shock.
U.S. Markets Absorb Inflation and Rate-Hike Pressure
All four U.S. benchmarks in the supplied data finished the five-day period lower. The Dow Jones Industrial Average fell 2.07%, the S&P 500 declined 1.17%, the Nasdaq Composite fell 0.94% and the Russell 2000 dropped 2.17%. The Russell’s larger decline is significant because smaller companies are generally more exposed to financing costs and domestic economic conditions. The week became increasingly difficult as oil moved above $100 a barrel and Treasury yields approached multi-year highs, increasing the market’s sensitivity to the Federal Reserve’s policy outlook. Reuters reported that August consumer inflation increased 0.4% and strengthened expectations for a possible rate increase at the following week’s Federal Reserve meeting.
Energy Shock Becomes the Global Market Transmission Channel
Oil was central to the week’s market repricing. Brent crude remained on track for a gain of more than 8% as attacks and disruptions around the Strait of Hormuz and other shipping routes raised concerns about the availability and cost of energy. That matters beyond the energy sector: higher crude and fuel prices feed into transportation, manufacturing and consumer prices, making it harder for central banks to ease monetary policy. The U.S. Dollar Index was comparatively stable, falling just 0.07%, suggesting that currency markets did not experience the same degree of weekly dislocation seen in equities.
Europe and Asia Bear the Heavier Equity Losses
European markets weakened across the board. The DAX fell 1.83%, CAC 40 declined 1.20%, FTSE 100 dropped 1.67% and MSCI Europe fell 1.78%. The deterioration reflected the combined effect of higher energy costs, rising bond yields and renewed inflation concerns. Reuters reported that European equities recorded their steepest weekly decline since early July after the European Central Bank raised interest rates and warned that inflation could remain elevated because of energy pressures. Asia was weaker still: the Nikkei 225 fell 3.60%, Hang Seng declined 3.30%, KOSPI fell 1.22% and Shanghai’s SSE Composite dropped 1.07%. Japan’s larger decline highlights the sensitivity of its market to global yields, currency movements and international risk appetite.
Israeli Equities Show Relative Resilience
Tel Aviv was comparatively defensive during the week. The TA-35 fell only 0.33%, while the TA-125 declined 1.40%, meaning both benchmarks outperformed the major European and Asian indexes shown in the data. The relative performance is notable given the broader regional energy and geopolitical risks. However, the supplied index data do not establish whether banks, defense companies, institutional flows or another specific sector was responsible for the resilience, so attributing the performance to a particular group would go beyond the evidence. The more defensible conclusion is that Israeli equities experienced a substantially smaller weekly drawdown than most major global markets.
The next week presents a direct test of whether inflation fears have become strong enough to alter monetary policy. The Federal Reserve’s decision and guidance will be the central event after August inflation data reinforced expectations for a possible rate increase. At the same time, oil prices above $100 and continued disruption around major shipping routes leave markets exposed to another inflation shock. The key question is therefore no longer simply whether equities can recover from this week’s losses, but whether central banks can contain inflation without creating a broader growth shock.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- orshu
- •
- 6 Min Read
- •
- ago 6 days
SKN | Global Markets Weekly Performance Review: September 28 to October 2, 2026
The week exposed a widening gap between technology resilience and broader market pressure. Nasdaq gained 0.45%, while the S&P
- ago 6 days
- •
- 6 Min Read
The week exposed a widening gap between technology resilience and broader market pressure. Nasdaq gained 0.45%, while the S&P
- orshu
- •
- 8 Min Read
- •
- ago 2 weeks
SKN | Global Markets Weekly Performance Review: September 21 to September 25, 2026
The defining feature of the September 21 to September 25 trading week was the widening gap between technology-led equity
- ago 2 weeks
- •
- 8 Min Read
The defining feature of the September 21 to September 25 trading week was the widening gap between technology-led equity
- orshu
- •
- 7 Min Read
- •
- ago 3 weeks
SKN | Global Markets Weekly Performance Review: September 14 to September 18, 2026
The week of September 14 to September 18 showed a sharp divergence between global markets. While the Dow Jones
- ago 3 weeks
- •
- 7 Min Read
The week of September 14 to September 18 showed a sharp divergence between global markets. While the Dow Jones
- orshu
- •
- 6 Min Read
- •
- ago 1 month
SKN | Global Markets Weekly Performance Review: August 31 to September 4, 2026
The week exposed a striking split in global markets: the macro backdrop became more difficult, but U.S. equities barely
- ago 1 month
- •
- 6 Min Read
The week exposed a striking split in global markets: the macro backdrop became more difficult, but U.S. equities barely

