





- orshu
- •
- 7 Min Read
- •
- 34 seconds ago


Key Points
- Mega-cap technology behemoths Meta Platforms, Tesla, and Netflix headline an intense third-quarter earnings schedule alongside aerospace and defense leaders.
- China reports stronger-than-expected third-quarter economic growth while preliminary October purchasing managers index readings and United Kingdom inflation anchor macro telemetry.
- Statutory holiday observances in Hong Kong, Jamaica, and India temporarily interrupt execution liquidity and cross-border settlement channels early in the week.
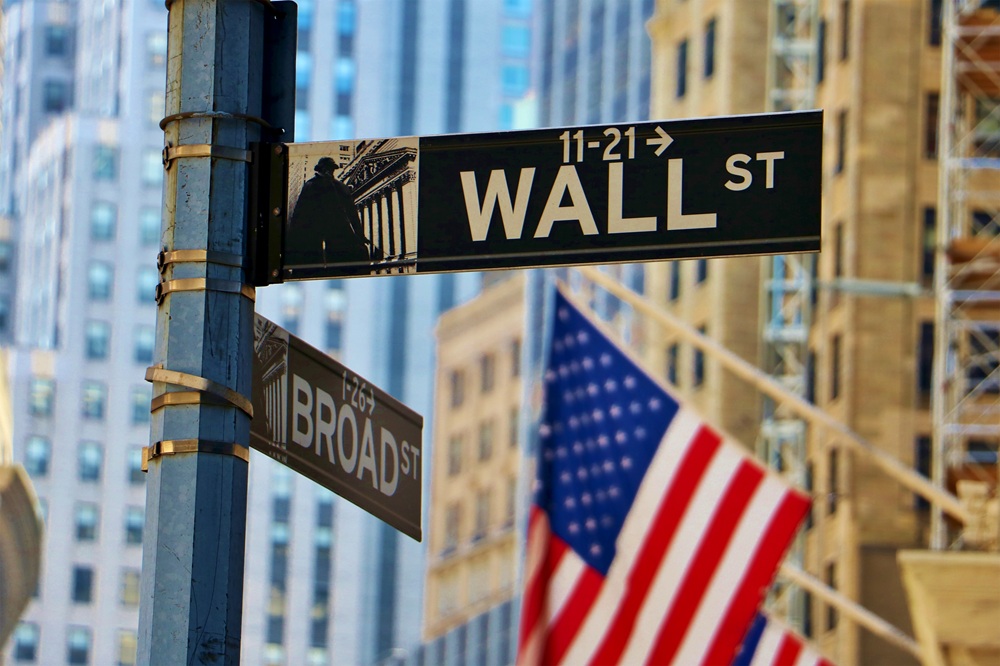
Global financial equity and debt markets enter the trading week of October 19, 2026, under heavy institutional focus as earnings season expands into core technology, aerospace, and defense sectors. Asset managers and cross-border investment desks are actively evaluating third-quarter operational margins against shifting central bank interest rate trajectories and fresh international growth metrics. For global allocators and Israeli investment houses navigating this high-velocity catalyst window, maintaining tactical liquidity buffers is essential as corporate forward guidance reshapes cross-asset valuations.
Macroeconomic Blueprint: Chinese GDP Expansion, UK Inflation, and Transatlantic Flash PMIs
The macroeconomic calendar delivers influential real-economy indicators that will shape global sovereign bond yields and foreign exchange trends throughout the week. Action opens on Monday with China publishing third-quarter annual GDP growth at 4.5 percent, beating forecast expectations of 4.4 percent and accelerating from the prior 4.3 percent reading. Mid-week momentum centers on European price trends with the United Kingdom September Consumer Price Index projected at 3.4 percent year-over-year, alongside US crude oil inventory metrics on Wednesday. Macro telemetry culminates late in the week with US Initial Jobless Claims forecasted at 200,000 files on Thursday, followed by Friday’s flash October US S&P Global PMI prints, where Services is modeled at 58.0 and Manufacturing is projected at 55.5.
Corporate Earnings Matrix: Tech Giants, Semiconductor Capital, and Defense Titans
The corporate reporting tape enters its most critical phase of the third-quarter balance sheet cycle, led by mega-cap digital platforms, electric vehicle manufacturers, and defense contractors. High-profile earnings begin Tuesday with GE Aerospace, General Motors, RTX, Northrop Grumman, 3M, and Halliburton before the open, followed by Netflix, Intuitive Surgical, Capital One, and Chubb after the close. Wednesday represents the week’s focal point as Tesla, Meta Platforms, IBM, Lam Research, Texas Instruments, Abbott Laboratories, NextEra Energy, and AT&T publish quarterly results. Heavy reporting continues Thursday with Lockheed Martin, Nokia, Comcast, Blackstone, and American Airlines in the morning, followed by Western Digital, VeriSign, and Bloom Energy after hours, before concluding Friday with American Express, Schlumberger, Autoliv, and Booz Allen Hamilton.
Statutory Trading Holidays and International Exchange Execution Profiles
Trading desks and execution managers must account for localized operational breaks and reduced liquidity windows across key Asian and Caribbean financial centers early in the week. Capital flows in Asia-Pacific will experience brief volume reductions on Monday as the Hong Kong Stock Exchange halts standard trading operations for Chung Yeung Day. In the Americas, execution paths adjust concurrently as the Jamaica Stock Exchange pauses trading in observance of National Heroes Day. Regional liquidity shifts extend further into Tuesday as Indian capital markets pause execution for the Dussehra holiday, requiring cross-border institutional managers to space order execution carefully to prevent bid-ask spread expansion.
The Forward Horizon: Navigating Post-Earnings Multiples and Policy Regimes
Looking ahead, global equity multiples will depend heavily on whether upcoming mega-cap technology earnings and preliminary purchasing managers index prints confirm robust enterprise spending and consumer elasticity. A primary systemic risk confronting balanced portfolios involves conservative forward guidance regarding artificial intelligence capital expenditure alongside persistent labor market strength, which could push sovereign treasury yields higher and weigh on growth equities. Conversely, attractive strategic opportunities continue to surface across defense contractors with expanding order backlogs, cash-generative technology hardware providers, and resilient consumer service platforms exhibiting strong pricing power. Tracking weekly jobless claims, sovereign yield curve slope shifts, and corporate capex commitments will remain essential for protecting portfolio capital through the remainder of October.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- omer bar
- •
- 6 Min Read
- •
- ago 2 hours
SKN | Asian Markets Mixed as SENSEX Gains 0.56% and Nikkei Falls 2.08%; Hong Kong Observes Chung Yeung Day
Asian market indicators show mixed performance on Monday morning, October 19, as gains in India, mainland China and Australia contrast
- ago 2 hours
- •
- 6 Min Read
Asian market indicators show mixed performance on Monday morning, October 19, as gains in India, mainland China and Australia contrast

- Lior mor
- •
- 6 Min Read
- •
- ago 13 hours
SKN | British Pound Under Pressure Against the Dollar: What the Weekly Currency Trend Signals
The U.S. dollar strengthened against the British pound over the five-day period shown in the chart, as USD/GBP fell
- ago 13 hours
- •
- 6 Min Read
The U.S. dollar strengthened against the British pound over the five-day period shown in the chart, as USD/GBP fell

- Arik Arkadi Sluzki
- •
- 6 Min Read
- •
- ago 14 hours
SKN | USD/HKD Holds Near Its Upper Trading Range as Hong Kong Dollar Stability Persists
The US dollar traded at 7.8479 Hong Kong dollars in the latest snapshot, reflecting a marginal 0.02% increase from
- ago 14 hours
- •
- 6 Min Read
The US dollar traded at 7.8479 Hong Kong dollars in the latest snapshot, reflecting a marginal 0.02% increase from

- sagi habasov
- •
- 7 Min Read
- •
- ago 14 hours
SKN | US Dollar Strengthens Against the Australian Dollar as Midweek Volatility Tests Currency Momentum
The Australian dollar experienced a volatile trading period during the week of October 12–16, as the USD/AUD exchange rate
- ago 14 hours
- •
- 7 Min Read
The Australian dollar experienced a volatile trading period during the week of October 12–16, as the USD/AUD exchange rate

