





- omer bar
- •
- 8 Min Read
- •
- 16 seconds ago


Key Points
- The U.S. Dollar Index held firm near a two-week peak of 102.40 as currency desks priced in a 91% probability that the Federal Reserve will maintain benchmark borrowing costs unchanged.
- G10 currencies showed muted trading, with the New Zealand dollar steady at $0.5682 ahead of an expected Reserve Bank of New Zealand policy hike, while the Australian dollar gained on stubborn domestic inflation.
- For international desks and Israeli institutional allocators, sustained dollar resilience reinforces import cost pressures and complicates the Bank of Israel's domestic monetary policy calculus.
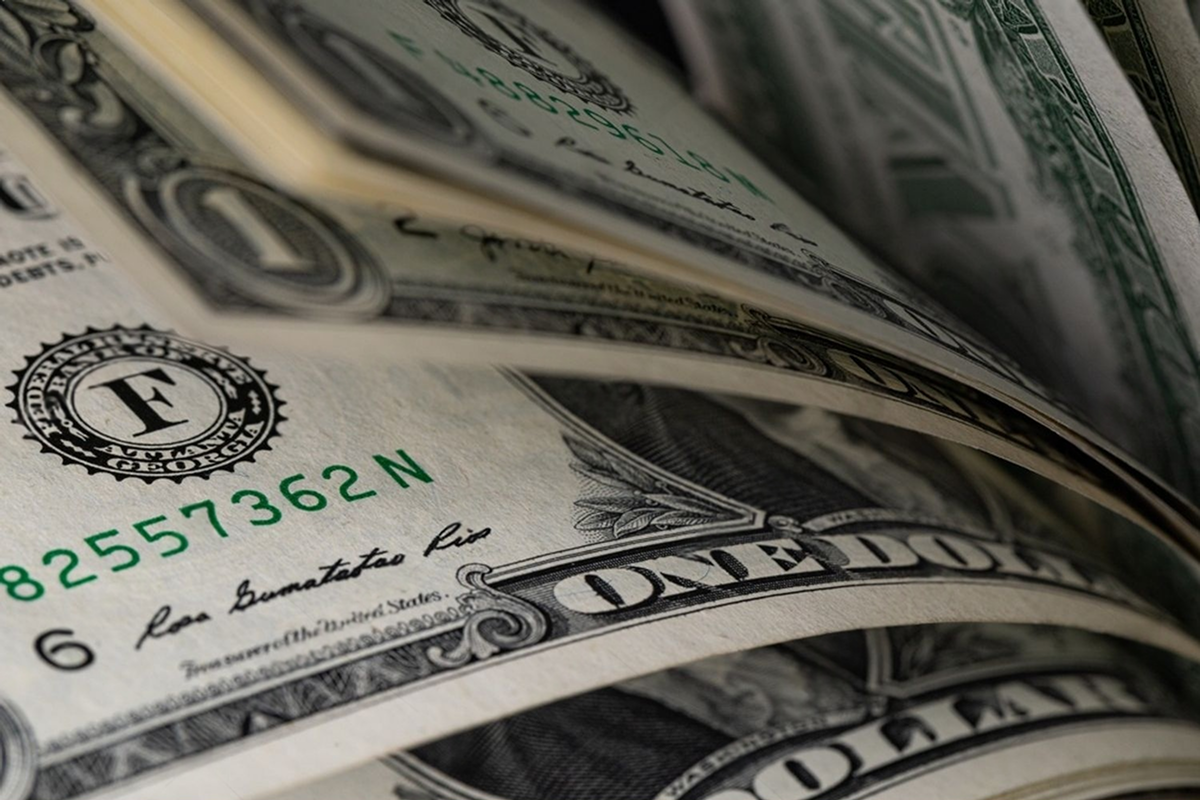
The U.S. dollar maintained its firm footing near multi-week highs on Wednesday, October 28, as global currency markets positioned for a consequential wave of central bank policy determinations. The U.S. Dollar Index, which evaluates the greenback against a basket of six major peers, traded around 102.40 after touching its strongest level since mid-October, supported by benchmark 10-year Treasury yields hovering near 4.99%. With macroeconomic indicators pointing to underlying resilience across the United States economy, market participants are scrutinizing forward guidance to ascertain whether central banks will prolong restrictive terminal rates into the final quarter of the year.
Federal Reserve Guidance Anchors Greenback Strength
The greenback’s sustained performance is underpinned by widespread market consensus that the Federal Open Market Committee will keep policy rates steady at the conclusion of its current meeting. Pricing across fed funds futures indicates an implied 91% probability of an unchanged rate decision, according to the CME FedWatch tool. Consequently, market attention has pivoted away from the immediate policy rate toward Chairman Jerome Powell’s tone and forward projections, particularly the perceived likelihood of a policy adjustment in December.
Major currency pairs reflected this wait-and-see posture across early trading sessions. The euro held flat at $1.1129, while the British pound traded largely unchanged at $1.3307. Against the Japanese yen, the dollar fluctuated tightly near 158.00, demonstrating limited institutional appetite for aggressive foreign exchange positioning prior to the release of the Fed’s formal policy statement.
Antipodean Rate Divergence: RBNZ Tightening and Australian Price Pressures
In the Asia-Pacific corridor, monetary policy paths are displaying visible divergence from the Fed’s wait-and-see stance. The New Zealand dollar traded evenly at $0.5682 ahead of a critical rate announcement from the Reserve Bank of New Zealand, where economists broadly anticipate an interest rate hike to rein in persistent non-tradable price pressures. The policy outcome will serve as an indicator of whether smaller open economies are being forced into additional tightening cycles despite slowing global consumption.
Concurrently, the Australian dollar advanced 0.3% to $0.7047 following the release of third-quarter inflation data. Australian headline consumer price index growth accelerated to 1.3% from 0.6% in the prior quarter, while the core trimmed mean gauge printed at 1.0%, keeping annualized core inflation elevated at 3.6%. The data prompted Reserve Bank of Australia Governor Michele Bullock to reiterate that policymakers will evaluate whether further rate increases are required at next week’s policy review, fueling regional currency volatility.
Cross-Border Implications for Israeli Allocators and the Shekel
The persistence of elevated U.S. yields and a robust dollar index carries direct transmission effects for Israel’s capital markets and the New Israeli Shekel (NIS). A resilient dollar creates persistent upward pressure on the USD/ILS exchange rate, elevating the landed cost of dollar-denominated imports, industrial raw materials, and energy commodities. This foreign exchange dynamic maintains upward pressure on domestic consumer price metrics, thereby narrowing the Bank of Israel Monetary Committee’s operational latitude to implement interest rate cuts.
For Israeli institutional investors, particularly pension funds and sovereign wealth allocations with significant overseas holdings, the dollar’s performance requires active duration and currency hedging recalibrations. High-yielding U.S. short-term paper continues to attract defensive capital flows, raising the opportunity cost of allocating into domestic fixed-income assets and growth equities listed on the Tel Aviv Stock Exchange.
Outlook: Terminal Yield Paths, Policy Tone, and Risk Appetite
Moving into subsequent trading sessions, currency markets will key in on whether central bank communications confirm an extended plateau in borrowing costs or reopen the door to late-cycle tightening. Investors should track whether the Federal Reserve’s updated rhetoric acknowledges easing labor cost pressures or emphasizes upside inflation risks stemming from global supply adjustments. A hawkish delivery that pushes Treasury yields decisively above 5.0% would likely trigger a secondary dollar breakout, exacerbating capital flight pressures across emerging market currencies and testing the resilience of global equity valuations.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- Lior mor
- •
- 6 Min Read
- •
- ago 4 hours
SKN | High Treasury Yields Force U.S. Banks to Rethink Bond Portfolios
A sharp rise in U.S. Treasury yields is forcing banks to reassess large bond portfolios accumulated when interest rates
- ago 4 hours
- •
- 6 Min Read

A sharp rise in U.S. Treasury yields is forcing banks to reassess large bond portfolios accumulated when interest rates

- orshu
- •
- 6 Min Read
- •
- ago 12 hours
SKN | Bond Markets Look Beyond the Fed as AI Financing Risks and U.S. Deficits Reshape the Outlook
U.S. bond markets are entering a period in which the Federal Reserve is no longer the only dominant
- ago 12 hours
- •
- 6 Min Read
U.S. bond markets are entering a period in which the Federal Reserve is no longer the only dominant

- Ronny Mor
- •
- 7 Min Read
- •
- ago 2 days
SKN | Chinese Yuan Hits Four-Year High as Markets Anticipate Key Policy Meetings
Yuan Strengthens Ahead of Policy Meetings China's yuan reached a fresh four-year high against the US dollar on Monday, extending
- ago 2 days
- •
- 7 Min Read
Yuan Strengthens Ahead of Policy Meetings China's yuan reached a fresh four-year high against the US dollar on Monday, extending
- Ronny Mor
- •
- 6 Min Read
- •
- ago 3 days
SKN | Global Stocks Slip as Oil Hits Six-Month High While Technology Shares Stabilize
Global equity markets ended a volatile week on Friday with major stock indexes lower, while technology shares showed signs
- ago 3 days
- •
- 6 Min Read
Global equity markets ended a volatile week on Friday with major stock indexes lower, while technology shares showed signs

