
- omer bar
- •
- 6 Min Read
- •
- 1 minute ago
Key Points
- The S&P 500 PEG ratio has reached a 30-year low, suggesting that equity valuations look less stretched when measured against expected earnings growth.
- FactSet expects 29.5% S&P 500 earnings growth in Q3 2026, followed by 27.6% growth in Q4 and 32.4% for the full year.
- Strong earnings expectations provide support, but higher volatility, interest rates, geopolitical premiums and currency risks remain important constraints for global asset allocators.
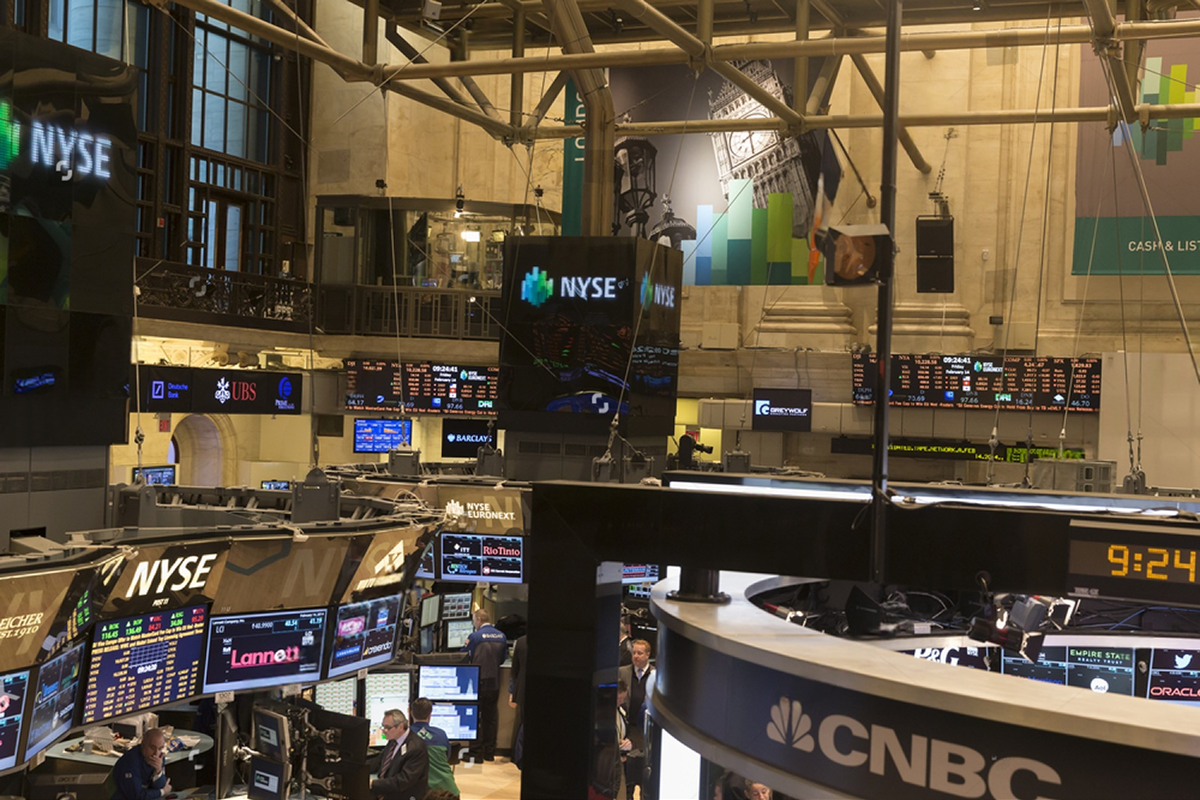
The debate over whether U.S. stocks have become excessively expensive is becoming more nuanced as strong corporate earnings expectations begin to offset elevated headline valuations. The S&P 500’s PEG ratio—a valuation measure that incorporates expected earnings growth—has fallen to its lowest level in roughly 30 years, according to Yardeni Research, offering a different perspective on the market’s valuation backdrop.
Growth Is Changing the Valuation Equation
The significance of the PEG ratio is that it places valuation alongside the expected pace of earnings expansion. A lower PEG ratio can indicate that investors are paying less for each unit of anticipated earnings growth, although it does not by itself establish that equities are cheap. The latest FactSet data show why the growth component has become increasingly important: analysts expect 29.5% year-over-year earnings growth for the S&P 500 in the third quarter. If realized, it would represent the third consecutive quarter of earnings growth above 25% and the eighth consecutive quarter of double-digit growth.
Earnings Momentum Is Providing Fundamental Support
The earnings outlook extends beyond the current quarter. Analysts currently expect 27.6% earnings growth in Q4 and 32.4% growth for calendar 2026. Revenue growth is also projected at 12.3% for Q3, while S&P 500 companies have continued to raise rather than reduce earnings expectations during the quarter. FactSet notes that Q3 EPS estimates increased 1.4% between June 30 and September 30, compared with the historical tendency for estimates to decline during a quarter.
This backdrop helps explain why the market can continue to command relatively elevated absolute valuations without necessarily appearing excessively priced on every measure. The forward 12-month P/E ratio stands at 19.0, below its five-year average of 19.8 and close to, but below, its 10-year average of 19.1.
Why the 30-Year Signal Is Not a Free Pass
The supplied market snapshots nevertheless point to a more cautious risk environment. The Dow’s five-day performance was approximately 0.32%, while the Nasdaq Composite was around 0.12%, even as the VIX showed a sharp increase of roughly 40.40% over the five-day period. That divergence highlights an important distinction: valuations may look more reasonable relative to earnings growth while market risk remains elevated.
For Israeli investors, the distinction is particularly relevant because U.S. equity exposure is often combined with shekel-based liabilities and diversified global allocations. Changes in the dollar, U.S. Treasury yields, geopolitical risk premiums and domestic currency volatility can materially influence returns even when underlying corporate earnings remain strong.
The next stage of the market will therefore depend less on the PEG statistic alone and more on whether companies can deliver the earnings growth already embedded in expectations. The Q3 reporting season, forward guidance, AI-related capital spending, interest-rate expectations and movements in the dollar will be important signals. A continued earnings expansion could support the current valuation framework, but weaker guidance, higher bond yields, fiscal concerns or renewed geopolitical stress could quickly challenge the market’s growth-adjusted valuation advantage.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- omer bar
- •
- 7 Min Read
- •
- ago 19 hours
SKN | Could SpaceX’s AI Ambitions and Starship Progress Unlock Further Stock Upside?
Morgan Stanley Sees a Narrow Window for Investors SpaceX shares moved sharply higher after Morgan Stanley analyst Adam Jonas renewed
- ago 19 hours
- •
- 7 Min Read

Morgan Stanley Sees a Narrow Window for Investors SpaceX shares moved sharply higher after Morgan Stanley analyst Adam Jonas renewed

- Lior mor
- •
- 6 Min Read
- •
- ago 1 day
SKN | A 1993 stock option mistake may have cost a former Nvidia advisor more than $1 billion.
A more than three-decade-old dispute over Nvidia stock options highlights how equity compensation at a young technology company can accumulate
- ago 1 day
- •
- 6 Min Read
A more than three-decade-old dispute over Nvidia stock options highlights how equity compensation at a young technology company can accumulate
- omer bar
- •
- 6 Min Read
- •
- ago 1 day
SKN | Amazon Stock Outlook: Can AMZN Beat the AI Shopping Agent Threat?
Amazon.com is facing a growing disconnect between its operating performance and investor concerns about the future of online shopping. While
- ago 1 day
- •
- 6 Min Read
Amazon.com is facing a growing disconnect between its operating performance and investor concerns about the future of online shopping. While
- Lior mor
- •
- 8 Min Read
- •
- ago 2 days
SKN | Is the S&P 500 Becoming Too Dependent on a Small Group of Winning Stocks?
The U.S. equity market is increasingly being driven by a narrow group of companies, while a large majority of
- ago 2 days
- •
- 8 Min Read
The U.S. equity market is increasingly being driven by a narrow group of companies, while a large majority of