
- sagi habasov
- •
- 6 Min Read
- •
- 1 minute ago
Key Points
- U.S. Consumer Staples, Healthcare, and Utilities sectors have outperformed the Nasdaq 100 by a combined 22.8 percentage points across October and November 2026—marking the largest two-month rolling spread since 2001.
- Following a 17.1 percentage-point relative gain in October, defensive equities have added another 5.8 percentage points in November as the Nasdaq 100 fell 4.9% month-to-date toward its worst November since 2008.
- For international allocators and Israeli institutional desks, capital is rotating out of capital-intensive AI technology into cash-generative staples and healthcare—pushing defensive forward P/E multiples above tech.
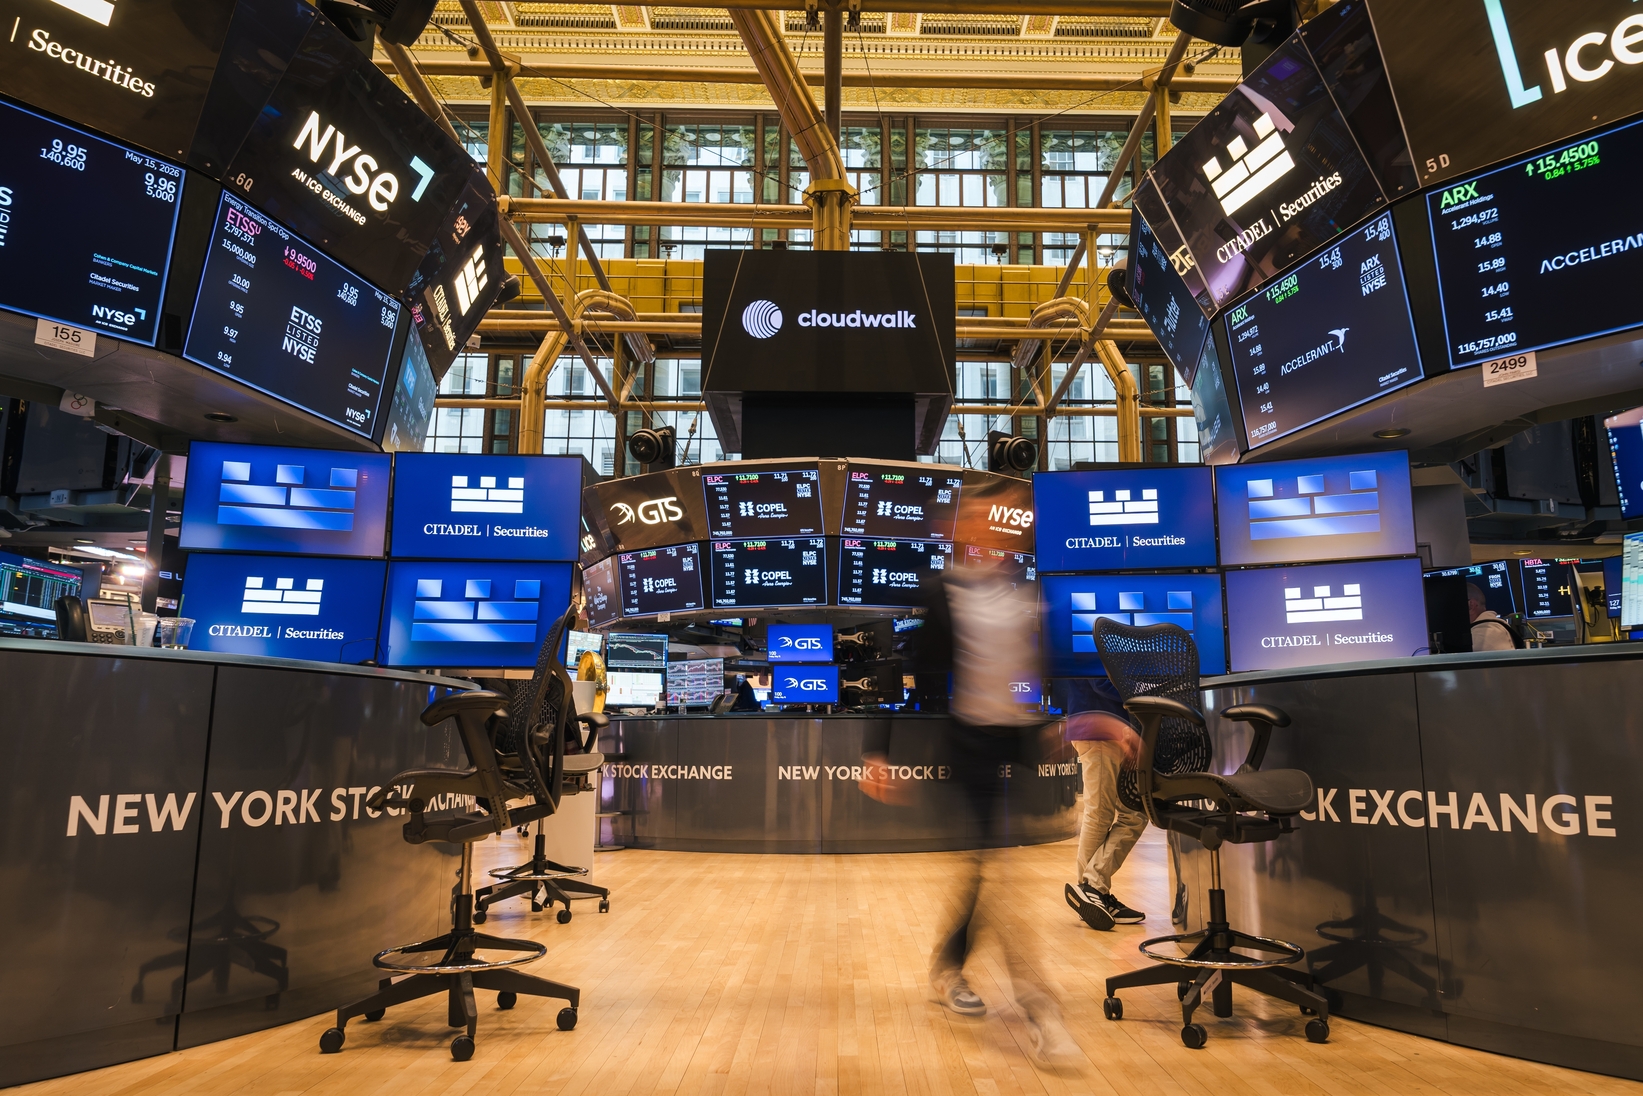
Institutional investors are rotating out of mega-cap technology and into defensive equities at the fastest pace in a quarter-century, with U.S. Consumer Staples, Healthcare, and Utilities outperforming the Nasdaq 100 by 22.8 percentage points across October and November 2026. Tracked through mid-November, the two-month rolling performance gap represents the widest defensive outperformance since the 2001 dot-com unwind—surpassed historically only by the 40.9 percentage-point spread recorded in 2000—as elevated interest rates and scrutiny over artificial intelligence capital expenditures prompt portfolio de-risking.
Record Two-Month Spread Driven by Tech Drawdown and Staple Resilience
The rotation accelerated sharply in October, when defensive sectors outpaced the Nasdaq 100 by 17.1 percentage points—their strongest single-month relative gain since February 2001—propelled by double-digit advances in S&P 500 Consumer Staples (+11.6%), Utilities (+10.2%), and Healthcare (+9.9%) alongside steep declines in Information Technology and Communication Services. That divergence has extended into November with an additional 5.8 percentage-point relative lead: while the Nasdaq 100 has fallen 4.9% month-to-date—putting the tech-heavy benchmark on track for its weakest November since the 2008 Global Financial Crisis—Consumer Staples have gained 2.9%, Healthcare has edged up 0.1%, and Utilities have dipped just 0.3%.
Beneath the surface, the shift reflects both macro tightening and valuation discipline. Sticky U.S. inflation readings and benchmark 10-year Treasury yields above 5% have compressed duration-sensitive growth multiples, while U.S. midterm election results and Nvidia’s executive shakeup added political and governance uncertainty to high-flying semiconductor names. Simultaneously, equal-weight equity indexes have posted their widest monthly outperformance over market-cap-weighted benchmarks since 2009, signaling broad institutional reallocation away from concentrated mega-cap leadership.
Valuation Inversion and Transmission Channels for Israeli Desks
The magnitude of the fourth-quarter rotation has inverted longstanding Wall Street valuation norms. Following two months of sustained inflows into non-cyclical equities and profit-taking across software and chipmakers, forward price-to-earnings ratios for S&P 500 Consumer Staples and Healthcare now trade at a premium to the Information Technology sector. Institutional managers have prioritized earnings visibility and pricing power over capital-intensive AI infrastructure commitments, even as defensive multiples become increasingly stretched.
For Israeli institutional pension managers and equity allocators on the Tel Aviv Stock Exchange (TASE), this global factor rotation carries direct asset-allocation consequences. Domestic institutional funds—which maintain substantial benchmark exposure to U.S. technology and Nasdaq-linked index products alongside local banking, insurance, and pharmaceutical leaders—face heightened tracking risk from concentrated U.S. tech drawdowns. Concurrently, with the New Israeli Shekel (NIS) consolidating steadily near 3.17 per dollar, local multi-asset desks are evaluating global healthcare and domestic defensive cash flows alongside high-yielding Israeli sovereign bonds (Shahar) to dampen portfolio volatility.
Outlook: Anthropic’s Nasdaq Debut, December FOMC, and Valuation Mean Reversion
Moving into the final weeks of 2026, market participants will watch whether Nvidia’s strong third-quarter revenue beat and Anthropic’s record $81.3 billion Nasdaq debut stabilize sentiment across growth equities or trigger further profit-taking. Key macro catalysts include the Federal Reserve’s December interest-rate decision and fourth-quarter corporate margin guidance. Historically, extreme two-month defensive outperformance episodes exceeding 15 percentage points have coincided with elevated cross-asset volatility—suggesting that while near-term macro uncertainty favors balance-sheet resilience, stretched defensive valuations could set the stage for sharp mean-reversion rallies once Treasury yields peak.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- Ronny Mor
- •
- 7 Min Read
- •
- ago 4 hours
SKN | Treasury Yields and Crude Oil Show Diverging Correlations With the S&P 500
Treasury Yields and Equities Return to Positive Correlation The latest rolling-correlation data show that the relationship between the U.S. 10-year
- ago 4 hours
- •
- 7 Min Read
Treasury Yields and Equities Return to Positive Correlation The latest rolling-correlation data show that the relationship between the U.S. 10-year

- Lior mor
- •
- 6 Min Read
- •
- ago 5 hours
SKN | U.S. Markets Trade Near Flat as Investors Assess Direction Across Major Benchmarks
U.S. Equities Show Diverging Performance U.S. equity benchmarks moved in different directions, reflecting an uneven session across market segments. The
- ago 5 hours
- •
- 6 Min Read
U.S. Equities Show Diverging Performance U.S. equity benchmarks moved in different directions, reflecting an uneven session across market segments. The

- orshu
- •
- 8 Min Read
- •
- ago 6 hours
SKN | Global Fund Managers Make Historic Retreat From Technology Stocks as AI Investment Concerns Intensify
Global institutional investors are making a significant adjustment to their technology allocations, signaling growing caution toward a sector that
- ago 6 hours
- •
- 8 Min Read
Global institutional investors are making a significant adjustment to their technology allocations, signaling growing caution toward a sector that

- sagi habasov
- •
- 8 Min Read
- •
- ago 6 hours
SKN | Is the AI Investment Boom Approaching a Turning Point? Fund Managers Increasingly Expect Big Tech to Cut Capital Spending
Institutional investors are increasingly questioning whether the extraordinary investment cycle supporting artificial intelligence can continue at its current pace.
- ago 6 hours
- •
- 8 Min Read
Institutional investors are increasingly questioning whether the extraordinary investment cycle supporting artificial intelligence can continue at its current pace.