
- orshu
- •
- 9 Min Read
- •
- 4 minutes ago
Key Points
- The U.S. Treasury purchased 79.4 billion yen on July 31, 2026, through a transaction executed by the Federal Reserve Bank of New York on the Treasury's behalf.
- The Federal Reserve confirmed that it did not independently intervene in foreign exchange markets during Q3 2026.
- The dollar declined 3.2% against the yen during the quarter, as U.S. and Japanese currency operations, Bank of Japan policy expectations and market positioning supported the Japanese currency.
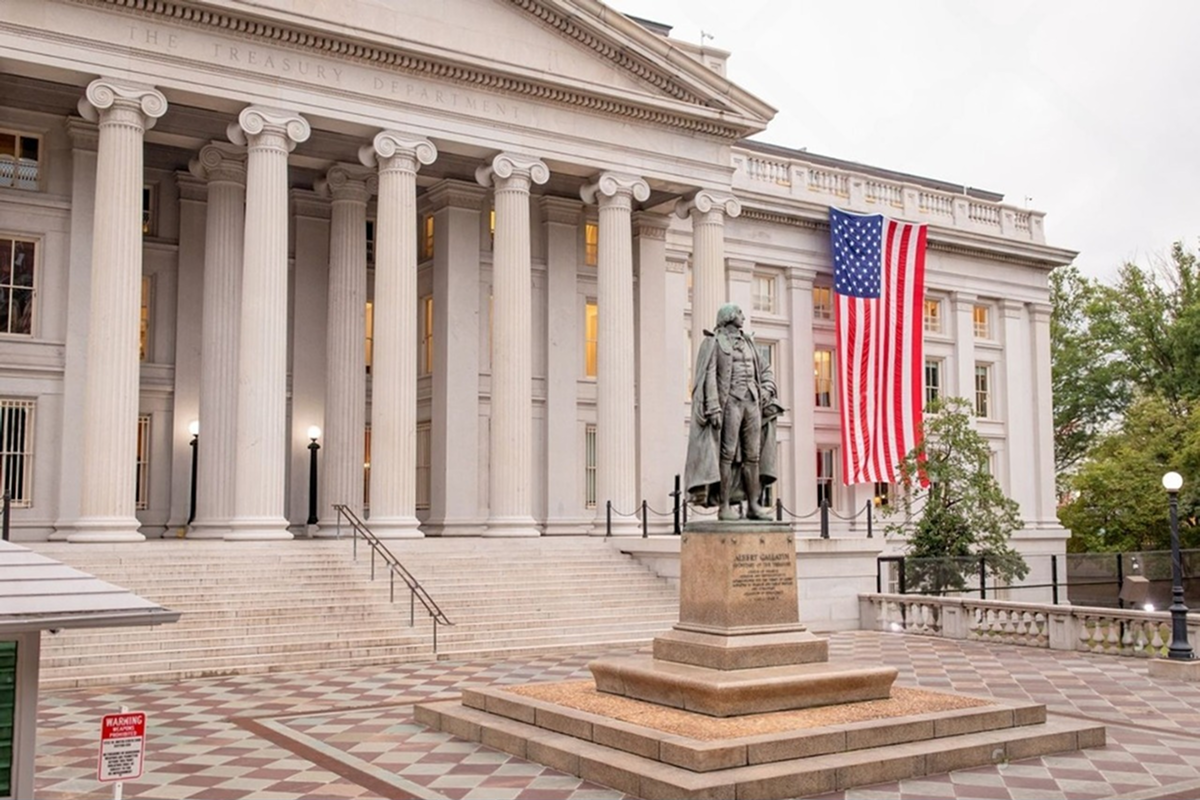
The U.S. Treasury’s latest foreign exchange report confirms an unusual intervention in support of the Japanese yen during the third quarter of 2026, highlighting Washington’s willingness to participate in currency-market stabilization when exchange-rate movements become disorderly. The operation also underscores an important institutional distinction: although the Federal Reserve Bank of New York executed the transaction, it did so on behalf of the Treasury rather than under an independent Federal Reserve monetary-policy decision.
A Rare U.S. Treasury Intervention in the Yen Market
According to the Federal Reserve Bank of New York’s quarterly report released on November 12, the U.S. Treasury purchased 79.4 billion yen in the spot foreign exchange market on July 31. The transaction was conducted through the New York Fed, which sold euros from the U.S. Treasury’s Exchange Stabilization Fund (ESF) to acquire yen. The operation was intended to counter what the Treasury considered disorderly movements in the Japanese currency.
The intervention followed market attention on July 30, when reports emerged that the New York Fed had requested indicative quotes for the dollar-yen exchange rate, commonly known as a rate check. The yen appreciated 2.3% against the dollar that day as those reports circulated. Rate checks do not themselves constitute currency intervention, but they can signal that authorities are assessing market conditions and considering possible action.
The U.S. operation took place alongside intervention by Japan’s Ministry of Finance, which conducted currency purchases totaling approximately 15.4 trillion yen during the third quarter. The coordinated actions formed part of a broader effort to address excessive volatility and pressure on the yen. The New York Fed’s official announcement confirms both the Treasury’s intervention and the Federal Reserve’s separate decision not to intervene.
Why the Federal Reserve Was Not Considered an Intervening Party
The distinction between the Treasury and the Federal Reserve is central to understanding the operation. The New York Fed is authorized to execute foreign exchange transactions under two different mandates: on behalf of the Federal Open Market Committee (FOMC) through the System Open Market Account, or on behalf of the U.S. Treasury as fiscal agent for the Exchange Stabilization Fund.
In this case, the transaction was directed by the Treasury. The New York Fed acted as the operational intermediary, but the purchase was not an independent intervention by the Federal Reserve or an FOMC-directed operation. The quarterly report therefore explicitly states that the Federal Reserve did not intervene in foreign exchange markets during Q3.
This distinction matters for financial markets because currency intervention and monetary policy serve different purposes. The Treasury’s operation targeted exchange-rate conditions, while the Federal Reserve’s monetary-policy decisions remained focused on domestic economic objectives, including inflation and employment. The episode demonstrates how U.S. authorities can participate in international currency operations without changing the central bank’s monetary-policy stance.
Yen Recovery Reflects Policy Expectations and Market Positioning
The intervention occurred as the yen was trading near multi-decade lows, with the dollar-yen exchange rate approaching 164 yen per dollar in July. Between July 30 and August 3, the exchange rate moved toward approximately 155 yen per dollar, reflecting a sharp strengthening of the Japanese currency. Across the full third quarter, the dollar declined 3.2% against the yen.
However, the New York Fed report attributes the yen’s recovery to several interacting factors rather than intervention alone. These included purchases by U.S. and Japanese authorities, rising expectations for a faster pace of Bank of Japan interest-rate increases and speculation about potential changes in the investment allocation of Japan’s Government Pension Investment Fund. The unwinding of speculative short-yen positions also amplified the currency’s appreciation.
The longer-term challenge remains whether official intervention can produce lasting currency stability without support from underlying economic conditions. On November 12, Reuters reported that the yen had weakened toward 160 per dollar again, while Japanese officials renewed warnings about excessive currency movements. This suggests that the July intervention did not eliminate the pressures affecting the exchange rate.
Going forward, investors will be monitoring the interest-rate differential between the United States and Japan, the Bank of Japan’s policy decisions and the willingness of Japanese and U.S. authorities to coordinate further action. For international portfolios and cross-border businesses, the episode reinforces the importance of currency exposure as a source of market risk. The effectiveness of future interventions will depend not only on the scale of official purchases but also on whether monetary-policy conditions and investor positioning become more supportive of a sustained yen recovery.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- Lior mor
- •
- 6 Min Read
- •
- ago 12 hours
Alphabet’s First Hong Kong and Singapore Bond Sales Attract $5 Billion in Orders
Alphabet Draws Strong Demand for Asian Bond Debut Alphabet, Google's parent company, attracted approximately $5 billion in combined orders for
- ago 12 hours
- •
- 6 Min Read
Alphabet Draws Strong Demand for Asian Bond Debut Alphabet, Google's parent company, attracted approximately $5 billion in combined orders for

- orshu
- •
- 7 Min Read
- •
- ago 14 hours
SKN | Tel Aviv Stocks Trade Mixed as TA-35 Edges Higher While Small-Cap and Mid-Cap Gauges Slip
Trading on the Tel Aviv Stock Exchange displays a restrained and mixed tone during open market hours, with select large-cap
- ago 14 hours
- •
- 7 Min Read
Trading on the Tel Aviv Stock Exchange displays a restrained and mixed tone during open market hours, with select large-cap
- orshu
- •
- 9 Min Read
- •
- ago 18 hours
SKN | Global Markets Wrap: November 11, 2026 Broad Rally Sweeps Wall Street, Europe, and Asia as Tel Aviv Slips Ahead of November 12 US Inflation Watch
Global financial markets staged a synchronized advance on Wednesday, November 11, 2026, with risk appetite strengthening across North American, European,
- ago 18 hours
- •
- 9 Min Read
Global financial markets staged a synchronized advance on Wednesday, November 11, 2026, with risk appetite strengthening across North American, European,

- sagi habasov
- •
- 6 Min Read
- •
- ago 19 hours
SKN | Dollar Holds Near One-Month High as Yen Edges Toward 160: Will Rate Divergence Force Tokyo’s Hand?
The U.S. dollar held steady near a one-month high against a basket of major currencies on Thursday, November 12, 2026,
- ago 19 hours
- •
- 6 Min Read
The U.S. dollar held steady near a one-month high against a basket of major currencies on Thursday, November 12, 2026,