




- orshu
- •
- 6 Min Read
- •
- 4 minutes ago


Key Points
- The S&P 500 (^GSPC) advanced 0.31%, or 23.13 points, to close at 7,376.86, partially recovering from a 2.68% weekly decline.
- The index traded between 7,369.55 and 7,444.20, after opening at 7,377.65, indicating a relatively narrow session range.
- Trading volume reached approximately 3.41 billion shares, below the reported three-month average of 5.16 billion, while the benchmark remained within its 52-week range of 6,316.91–7,844.52.
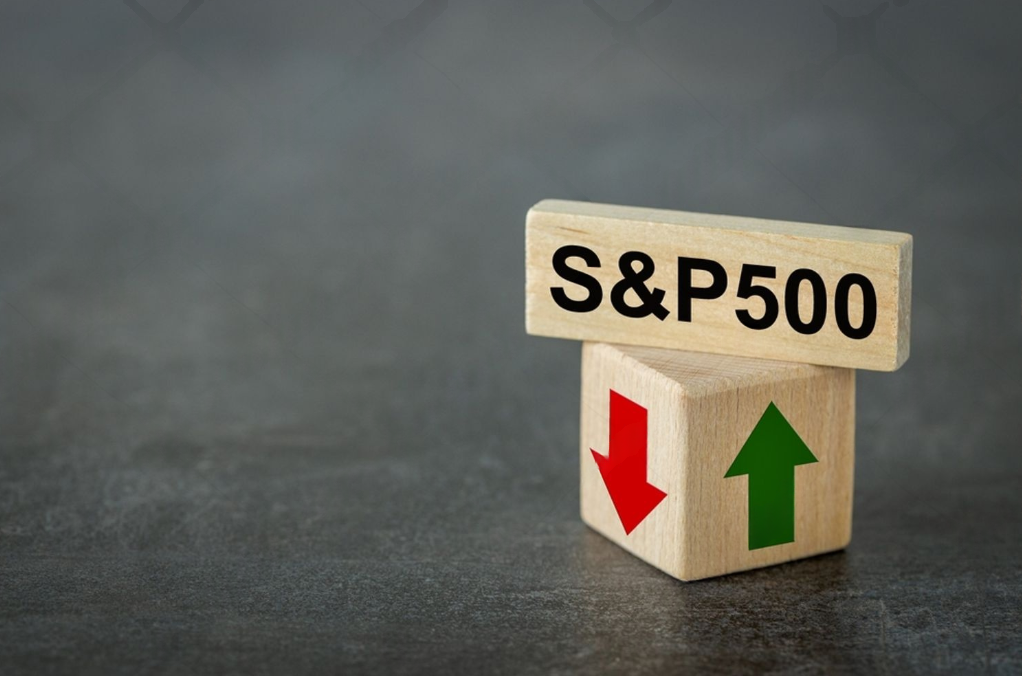
The S&P 500 ended the latest session higher, gaining 0.31% to settle at 7,376.86. The advance offered a modest recovery after a difficult five-day period in which the benchmark lost 2.68%. The contrast between the daily rebound and the broader weekly decline highlights the continuing uncertainty surrounding U.S. equities, as investors assess economic indicators, corporate earnings expectations and changes in government bond yields.
Intraday Trading and Below-Average Volume
The index opened at 7,377.65 and moved within a range of 7,369.55–7,444.20 during the session. It ultimately added 23.13 points from its previous close of 7,353.73. The limited advance suggests that buyers regained some ground, although the session did not produce a decisive recovery from the week’s losses.
Reported trading volume stood at approximately 3.41 billion shares, compared with a three-month average of approximately 5.16 billion. This below-average activity may indicate relatively restrained participation, although volume alone does not establish the strength or direction of institutional positioning. A sustained recovery would require broader participation alongside improving market breadth and stronger price momentum.
Weekly Decline and Position Within the Annual Range
Despite the latest gain, the S&P 500 remained down 2.68% over the five-day period. The weekly contraction points to continued pressure on equity valuations and suggests that the session’s positive performance was not yet sufficient to reverse the broader trend.
The benchmark remained within its reported 52-week range of 6,316.91–7,844.52, placing the latest close below the upper boundary but well above the annual low. The distance from the recent high-water mark leaves room for further volatility as investors reassess earnings growth, sector valuations and expectations for monetary policy. Performance among large technology companies and more defensive sectors will remain important in determining the index’s direction.
Monetary Policy and International Market Exposure
For international investors, including Israeli institutional funds with exposure to U.S. equities, the S&P 500’s performance must also be considered alongside currency and interest-rate developments. Federal Reserve policy expectations, movements in U.S. Treasury yields and fluctuations in the USD/ILS exchange rate can all influence the returns and risk profile of multi-currency portfolios.
Geopolitical developments and potential changes in fiscal policy add further uncertainty. These factors may affect corporate earnings expectations, cross-border capital flows and the valuation of U.S. assets, reinforcing the importance of monitoring both equity-market conditions and broader financial indicators.
The near-term outlook remains dependent on whether the latest advance develops into a more sustained recovery or proves to be a temporary pause within the weekly decline. A move toward the 7,500 level would likely require stronger earnings momentum, supportive liquidity conditions and greater investor participation. Conversely, renewed inflationary pressure, higher borrowing costs or weaker corporate guidance could extend the recent pullback. The next sessions may therefore provide a clearer indication of whether buyers are regaining control or whether the market remains vulnerable to further consolidation.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- Ronny Mor
- •
- 6 Min Read
- •
- ago 38 minutes
SKN | Russell 2000 Falls 2.05% on the Week Despite Friday Recovery as U.S. Small-Cap Stocks Face Renewed Pressure
The Russell 2000 Index ended the week ending November 6, 2026, with a partial recovery following a significant midweek
- ago 38 minutes
- •
- 6 Min Read
The Russell 2000 Index ended the week ending November 6, 2026, with a partial recovery following a significant midweek
- omer bar
- •
- 6 Min Read
- •
- ago 1 hour
SKN | Nasdaq Composite Falls 3.37% on the Week Despite Friday Rebound as Technology Stocks Face Renewed Pressure
The Nasdaq Composite ended the trading week on November 6 with a modest recovery, although the rebound was insufficient to
- ago 1 hour
- •
- 6 Min Read
The Nasdaq Composite ended the trading week on November 6 with a modest recovery, although the rebound was insufficient to

- sagi habasov
- •
- 8 Min Read
- •
- ago 14 hours
SKN | CME Delays Nvidia GPU Rental Futures Again: Regulatory Scrutiny Pushes AI Compute Derivatives Into 2027
The development of financial products linked to artificial intelligence infrastructure has encountered another regulatory obstacle, after CME Group agreed
- ago 14 hours
- •
- 8 Min Read
The development of financial products linked to artificial intelligence infrastructure has encountered another regulatory obstacle, after CME Group agreed
- sagi habasov
- •
- 7 Min Read
- •
- ago 18 hours
SKN | Soaring Tanker Rates Give U.S. Gulf Refiners an Edge as Crude Discounts Widen
Surging tanker rates following the Iran conflict are reshaping crude-oil economics, giving U.S. Gulf Coast refiners a growing cost
- ago 18 hours
- •
- 7 Min Read
Surging tanker rates following the Iran conflict are reshaping crude-oil economics, giving U.S. Gulf Coast refiners a growing cost
