
- Lior mor
- •
- 9 Min Read
- •
- 1 minute ago
Key Points
- The U.S. 30-year fixed mortgage rate reached approximately 7.60% on September 30, according to Mortgage News Daily, materially increasing the cost of new borrowing.
- Federal Reserve data show the top 1% held approximately $60.32 trillion in household wealth in the second quarter of 2026, compared with $4.28 trillion for the bottom 50%.
- The divergence highlights how asset ownership, financing costs and exposure to financial markets can produce very different outcomes across U.S. households.
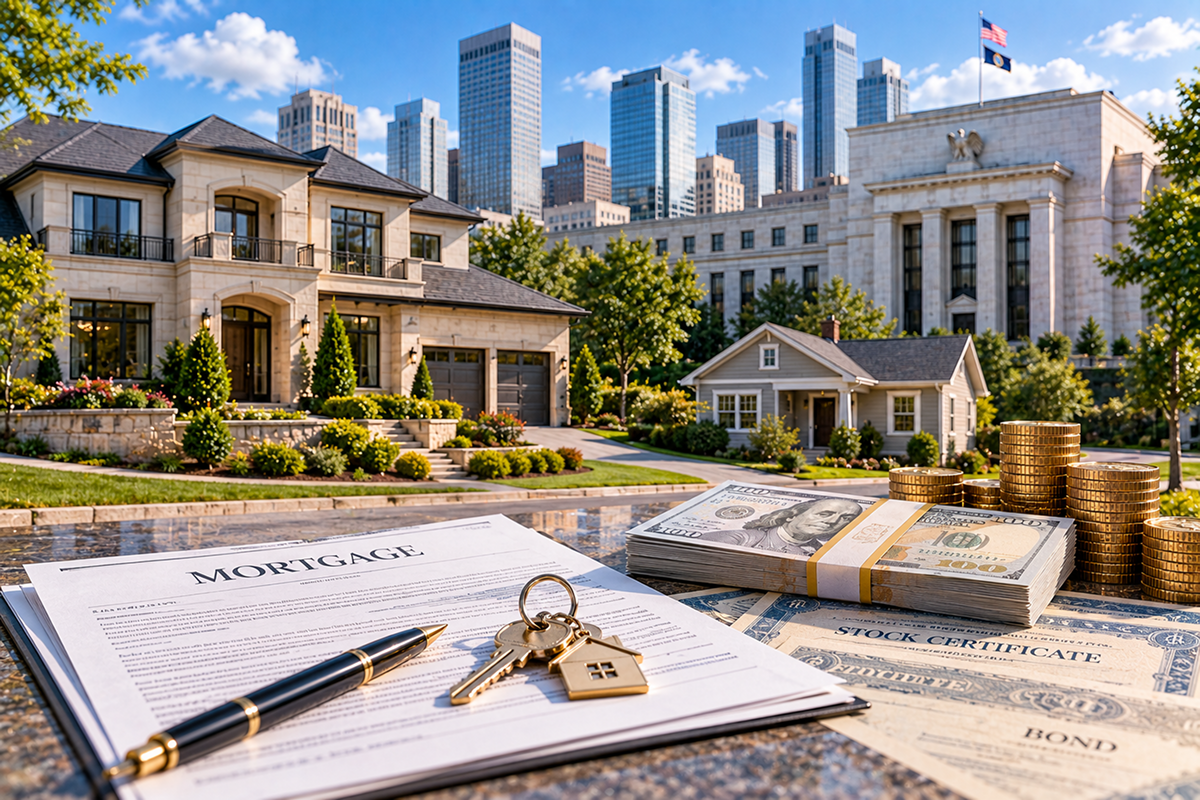
The U.S. economy is facing a notable combination of elevated borrowing costs and highly concentrated wealth. The latest data show the 30-year mortgage rate reaching 7.60% at the end of September, while Federal Reserve figures indicate that the top 1% of households held roughly $60.32 trillion in wealth in the second quarter of 2026, compared with $4.28 trillion for the bottom 50%.
The figures do not establish that rising interest rates directly caused the wealth concentration, nor do they mean that every asset owner benefits when borrowing costs rise. Instead, they highlight the different financial exposures of households: those with substantial financial and real-estate assets have a different balance sheet from households that depend more heavily on wages and credit.
Mortgage Rates Are Moving Sharply Higher
Mortgage News Daily’s daily index showed the average U.S. 30-year fixed mortgage rate at 7.60% on September 30, 2026, up from 6.37% a year earlier. The rate subsequently remained elevated, reaching 7.57% on October 2. The increase is significant for prospective homebuyers because mortgage rates directly affect monthly payments and the amount of housing that a household can finance.
The rise also demonstrates that mortgage costs do not simply follow the Federal Reserve’s policy rate. Long-term Treasury yields, inflation expectations, bond-market demand and mortgage-market conditions all influence the pricing of 30-year mortgages. Recent reporting has linked the renewed rise in mortgage rates to higher long-term Treasury yields, while housing demand has remained constrained by affordability.
For households entering the housing market, higher rates can therefore reduce purchasing power even when home prices are not rising rapidly. Existing homeowners with older fixed-rate mortgages, by contrast, can remain insulated from higher rates on their existing loans, creating a meaningful difference between households that already own property and those attempting to enter the market.
Wealth Concentration Has Increased Dramatically
The Federal Reserve’s Distributional Financial Accounts show that the top 1% of U.S. households held approximately $60.32 trillion in net wealth in 2026’s second quarter. That figure is calculated from $27.87 trillion held by the top 0.1% and $32.45 trillion held by the remainder of the top 1%. The bottom 50% held approximately $4.28 trillion.
Using the Federal Reserve’s aggregate figures, the top 1% accounted for roughly 32.5% of total household wealth in the second quarter, while the bottom half held approximately 2.3%. The distribution has also changed substantially since the beginning of the pandemic. In the first quarter of 2020, the top 1% held about $29.51 trillion, compared with approximately $1.93 trillion for the bottom 50%. By the second quarter of 2026, those figures had increased to $60.32 trillion and $4.28 trillion, respectively.
The comparison is important, but it should not be interpreted as a simple transfer of wealth from one group to another. The Federal Reserve’s measure captures changes in the value of financial assets, real estate, businesses and other household holdings. Asset-price appreciation can therefore increase measured wealth without representing an equivalent amount of new cash income.
Why Asset Ownership Matters in a High-Rate Environment
The composition of wealth helps explain why households can experience the same macroeconomic environment very differently. Federal Reserve data for the second quarter of 2026 show that the top wealth groups held substantial amounts of corporate equities and mutual fund shares. The top 0.1% alone held approximately $16.15 trillion in those assets, while the bottom 50% held about $370 billion.
Real estate is more broadly distributed, but the ownership structure is still uneven. The Federal Reserve estimates that the bottom 50% held approximately $4.82 trillion in real estate assets in the second quarter, compared with $23.21 trillion for the 50th-to-90th percentile group and $1.97 trillion for the top 0.1%. These figures reinforce that household wealth is built from different combinations of housing, equities, businesses, pensions and other assets.
Higher mortgage rates can therefore create a financial divide between existing owners and prospective buyers. Existing owners with substantial equity may face fewer immediate financing pressures, while younger households or first-time buyers can face higher monthly payments and larger barriers to purchasing property. At the same time, higher rates can eventually pressure asset valuations, meaning wealthy households are not completely insulated from tighter financial conditions.
Looking ahead, the interaction between long-term Treasury yields, mortgage rates, asset prices and household balance sheets will remain critical. If borrowing costs remain near current levels, housing affordability could stay constrained even if home-price growth moderates. At the same time, another sustained period of equity and real-estate appreciation could further increase measured wealth among households with large asset holdings. The key issue for policymakers and investors will be whether financial conditions eventually broaden wealth creation through stronger income and productivity growth, or whether asset-price gains continue to accrue disproportionately to households that already own substantial financial and real assets.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- omer bar
- •
- 9 Min Read
- •
- ago 1 minute
SKN | U.S. Data Center Construction Spending Surges to $85 Billion as AI Reshapes Capital Investment
The latest U.S. construction data illustrate a major shift in where corporate capital is being deployed. Data center construction
- ago 1 minute
- •
- 9 Min Read
The latest U.S. construction data illustrate a major shift in where corporate capital is being deployed. Data center construction

- Ronny Mor
- •
- 8 Min Read
- •
- ago 30 minutes
SKN | US and China Money Supply Reaches Record Levels: Is Global Liquidity Entering a New Expansion Cycle?
U.S. and Chinese money supply has reached unprecedented nominal levels, reinforcing the importance of liquidity conditions for global financial
- ago 30 minutes
- •
- 8 Min Read
U.S. and Chinese money supply has reached unprecedented nominal levels, reinforcing the importance of liquidity conditions for global financial

- Arik Arkadi Sluzki
- •
- 7 Min Read
- •
- ago 30 minutes
SKN | Nike’s 33-Year Market Edge Fades as the S&P 500 Pulls Ahead
Nike’s long-term stock performance is beginning to look markedly different from its historic reputation as one of the world’s
- ago 30 minutes
- •
- 7 Min Read
Nike’s long-term stock performance is beginning to look markedly different from its historic reputation as one of the world’s
- omer bar
- •
- 7 Min Read
- •
- ago 6 hours
SKN | Fed’s Hammack Signals More Time to Weigh the Next Interest Rate Move
Federal Reserve Bank of Cleveland President Beth Hammack said the U.S. central bank still has time to evaluate incoming
- ago 6 hours
- •
- 7 Min Read
Federal Reserve Bank of Cleveland President Beth Hammack said the U.S. central bank still has time to evaluate incoming