




- orshu
- •
- 7 Min Read
- •
- 15 hours ago


Key Points
- Global equities delivered a mixed week as U.S. technology stocks recovered, with Nasdaq Composite gaining 0.72%, while the Dow Jones fell 1.69% and the S&P 500 declined 0.08%.
- Asian markets showed renewed strength, led by KOSPI rising 3.14% and Nikkei 225 gaining 2.40%, while China’s Shanghai Composite increased 0.61%.
- Israeli equities remained resilient, with TA-35 rising 1.62%, while TA-125 recorded a smaller decline of 0.50% during the five-day period.
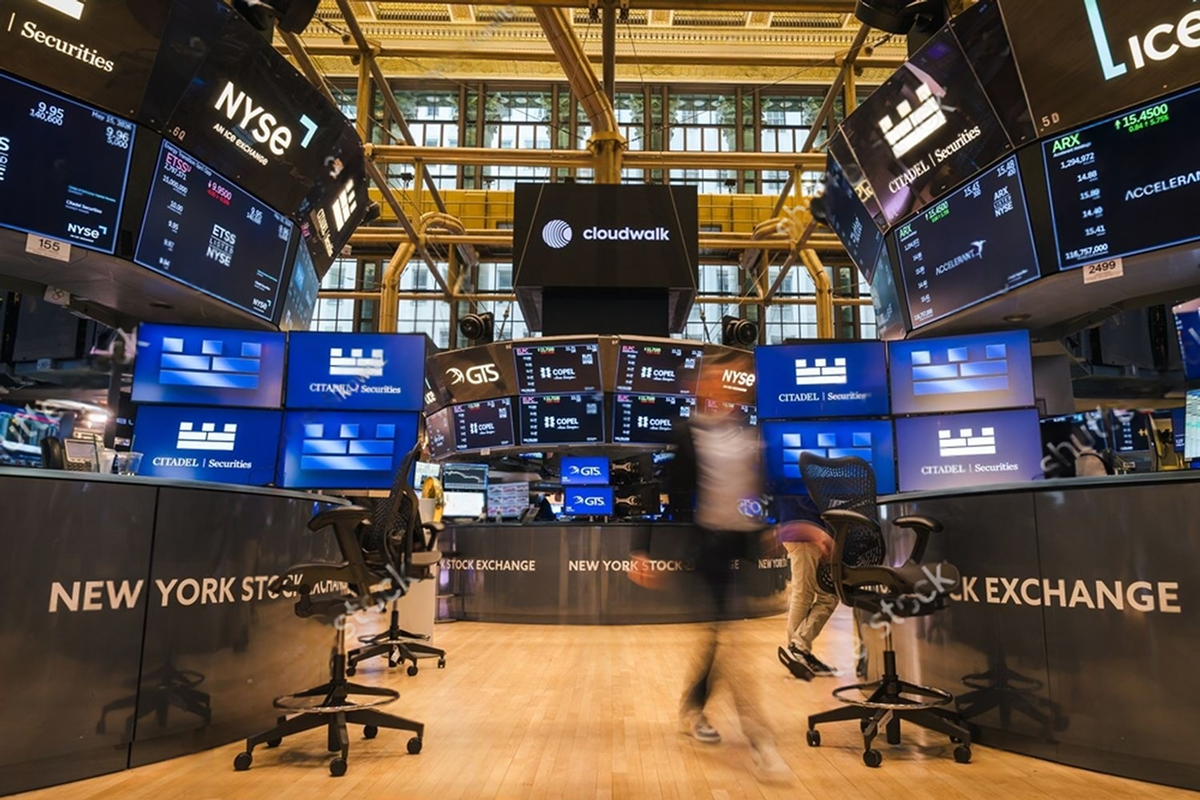
The week of September 14 to September 18 showed a sharp divergence between global markets. While the Dow Jones Industrial Average fell 1.69% and European equities remained under pressure, technology-focused markets regained momentum, with the Nasdaq Composite advancing 0.72%. The contrast reflected changing investor expectations around interest rates, artificial intelligence-related sectors and regional economic conditions.
U.S. Markets Split Between Technology Strength and Industrial Weakness
U.S. equity performance was uneven during the week. The Nasdaq Composite gained 0.72%, supported by continued investor interest in technology companies and sectors linked to artificial intelligence infrastructure. The S&P 500 was nearly unchanged, falling only 0.08%, suggesting that gains in large technology companies offset weakness elsewhere in the index. Meanwhile, the Dow Jones declined 1.69%, reflecting greater pressure on traditional industrial and economically sensitive companies. The Russell 2000, which tracks smaller U.S. companies, also fell 1.50%, indicating that smaller businesses remained more exposed to concerns around financing costs and economic uncertainty.
The U.S. Dollar Index gained 0.76% during the period, reflecting continued demand for dollar exposure as investors monitored monetary policy expectations. Currency movements remained closely linked to expectations surrounding the Federal Reserve’s interest-rate path and the timing of potential policy adjustments.
Asia Rebounds as Semiconductor and Growth Sentiment Improves
Asian markets recorded stronger weekly performance compared with the previous period. South Korea’s KOSPI rose 3.14%, supported by renewed strength in technology-related shares and investor focus on semiconductor demand. South Korea’s market remains highly sensitive to global technology cycles because major export companies are closely connected to memory chips, electronics and artificial intelligence-related supply chains.
Japan’s Nikkei 225 gained 2.40%, recovering from recent volatility as investors continued to assess corporate earnings trends, currency movements and domestic economic conditions. China’s Shanghai Composite increased 0.61%, while Hong Kong’s Hang Seng Index declined slightly by 0.22%, showing a more cautious response toward Chinese growth expectations and property-sector concerns.
European Markets Face Growth and Policy Challenges
European equities remained mixed but generally weaker. The DAX declined 1.03%, CAC 40 fell 1.40%, and MSCI Europe dropped 0.81%. The FTSE 100 was comparatively stable, gaining 0.08%. European markets continued to balance several competing forces, including inflation concerns, monetary policy expectations and uneven economic growth across the region.
The decline in major European indexes highlights investor sensitivity toward companies with significant exposure to industrial activity, exports and consumer demand. Germany’s market, in particular, remains closely linked to manufacturing performance and global trade conditions, while France continues to navigate political and fiscal uncertainty.
Israeli Market Shows Relative Strength Amid Global Volatility
Israeli equities displayed relative resilience during the week. The TA-35 index gained 1.62%, while the TA-125 declined 0.50%. The mixed performance suggests that large-cap companies provided support even as broader market participation remained cautious.
The Israeli market continues to operate within a complex environment influenced by domestic economic conditions, regional geopolitical developments and global investor sentiment. Based on the supplied index data alone, it is not possible to determine whether banks, defense companies or institutional flows were the primary drivers of the weekly movement. However, the limited decline in the broader TA-125 compared with several global markets indicates that local equities were not exposed to the same level of selling pressure seen in parts of Europe and the United States.
Looking ahead, markets will continue to focus on the interaction between central-bank policy expectations, economic data releases and corporate earnings guidance. The next major question for investors will be whether technology leadership can continue supporting broader equity valuations while industrial and smaller companies face higher sensitivity to economic conditions. Currency movements, inflation trends and upcoming monetary-policy signals will remain important factors shaping global market direction.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- orshu
- •
- 7 Min Read
- •
- ago 1 week
SKN | Global Markets Weekly Performance Review: September 07 to September 11, 2026
The week exposed a growing conflict between inflation, energy security and monetary policy. U.S. equities absorbed another rise in
- ago 1 week
- •
- 7 Min Read
The week exposed a growing conflict between inflation, energy security and monetary policy. U.S. equities absorbed another rise in
- orshu
- •
- 6 Min Read
- •
- ago 2 weeks
SKN | Global Markets Weekly Performance Review: August 31 to September 4, 2026
The week exposed a striking split in global markets: the macro backdrop became more difficult, but U.S. equities barely
- ago 2 weeks
- •
- 6 Min Read
The week exposed a striking split in global markets: the macro backdrop became more difficult, but U.S. equities barely
- orshu
- •
- 7 Min Read
- •
- ago 3 weeks
SKN | Global Markets Weekly Performance Review: August 24 to August 28, 2026
The central feature of the trading week from August 24 to August 28, 2026, was not a broad global
- ago 3 weeks
- •
- 7 Min Read
The central feature of the trading week from August 24 to August 28, 2026, was not a broad global
- orshu
- •
- 7 Min Read
- •
- ago 4 weeks
SKN | Weekly Market Performance Review, August 17 to August 21, 2026: U.S. Stocks Slip as Global Markets Diverge
The week of August 17–21 exposed a sharp split across global markets: U.S. equities recovered on Friday but still
- ago 4 weeks
- •
- 7 Min Read
The week of August 17–21 exposed a sharp split across global markets: U.S. equities recovered on Friday but still
