
- Lior mor
- •
- 7 Min Read
- •
- 39 minutes ago
Key Points
- Japan’s Nikkei 225 leads the major actively trading Asian equity indices, gaining 2.27% to 69,858.99, while Australia’s S&P/ASX 200 advances 0.41% to 8,717.40.
- Hong Kong’s Hang Seng Index drops 2.60% to 23,972.29, while India’s S&P BSE SENSEX declines 0.79% to 71,909.70.
- Mainland China’s Shanghai and Shenzhen stock exchanges are closed for National Day, while South Korea’s Seoul Stock Exchange and KOSDAQ are closed for National Foundation Day of Korea.
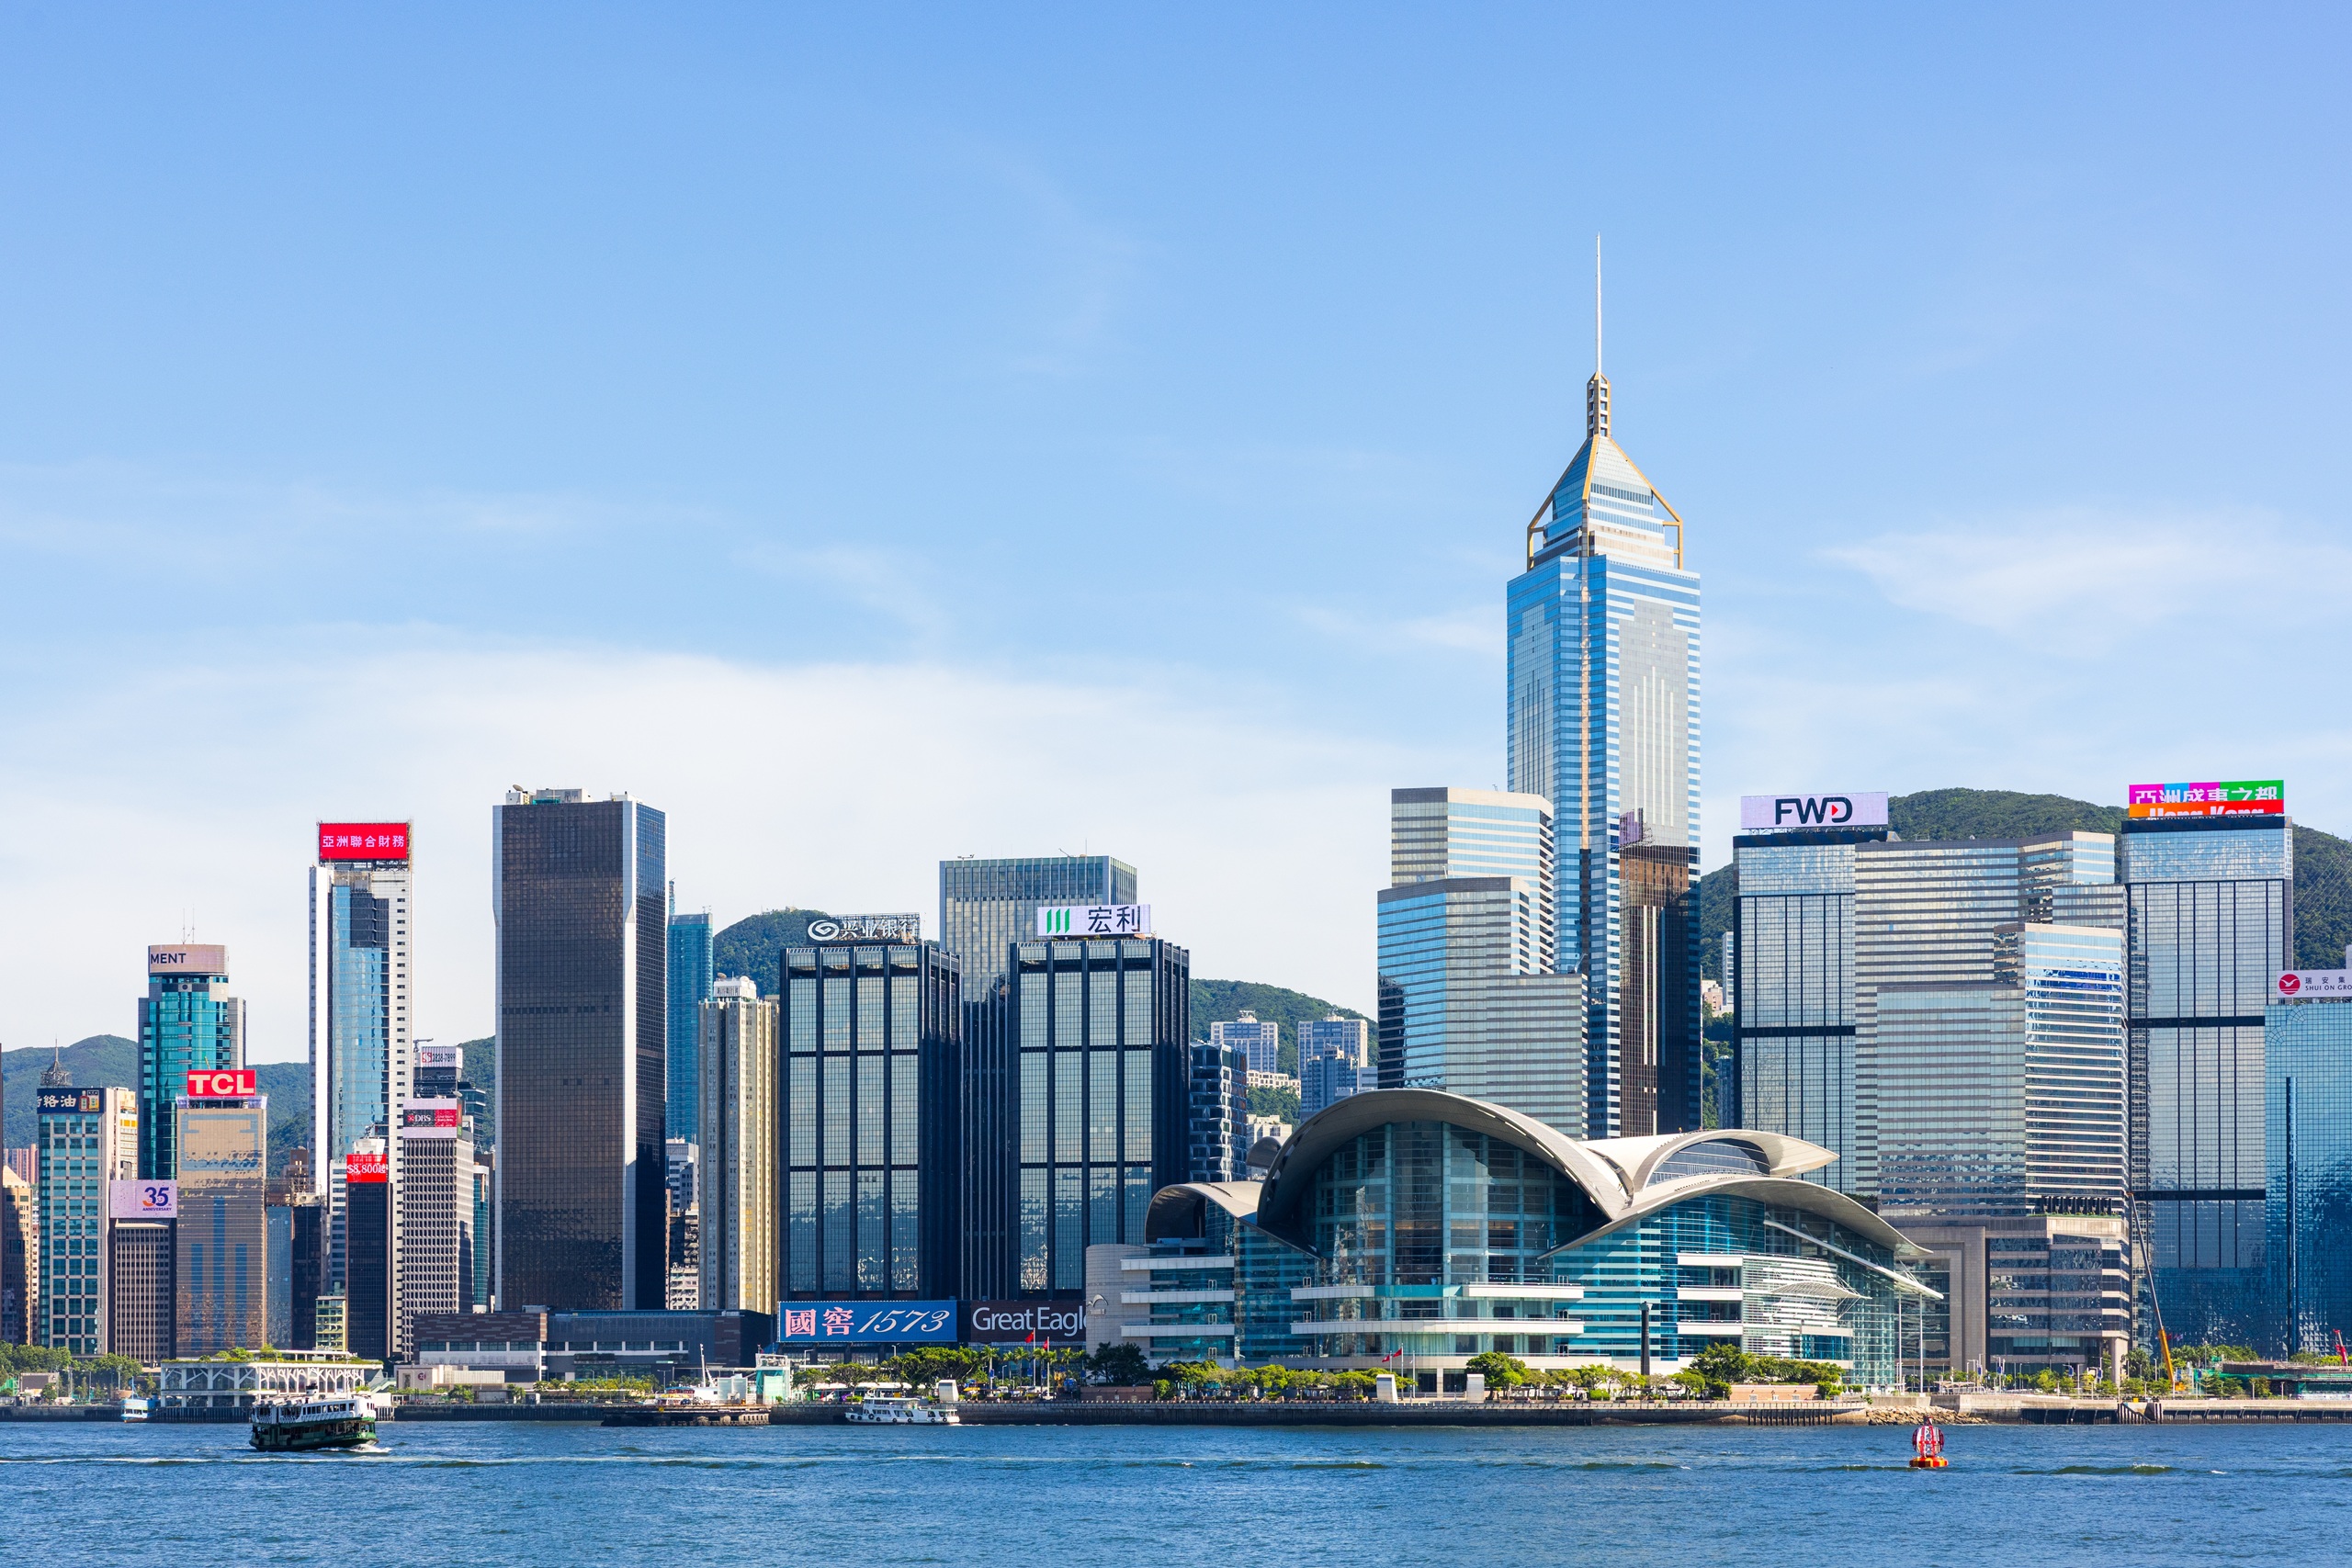
Asian markets presented a mixed picture on Monday morning, October 5, as Japan and Australia recorded gains while Hong Kong and India traded lower. The divergence among the major regional indices highlights the uneven direction of equity performance, with the Nikkei 225 posting the strongest advance and the Hang Seng recording the steepest decline among the listed equity benchmarks. Holidays in mainland China and South Korea also leave several major markets closed during the session.
Japan Leads Major Asian Indices as Nikkei 225 Advances
Japan’s Nikkei 225 climbed 2.27% to 69,858.99, leading the listed equity benchmarks in the morning session. The advance contrasts with losses elsewhere in the region, making Japan the strongest performer in the supplied market data. The figures, however, do not identify the sectors or individual stocks responsible for the increase, so the scale of the index gain does not establish that the broader Japanese market is advancing uniformly.
Australia’s S&P/ASX 200 also moved higher, rising 0.41% to 8,717.40. The Australian Dollar Index gained 0.36% to 69.56, while the Japanese Yen Index advanced 0.15% to 63.35. These currency indicators provide additional context for regional financial markets, although the reported movements alone do not establish a direct connection between exchange-rate changes and equity performance.
Hang Seng Declines as India’s SENSEX Also Moves Lower
Hong Kong’s Hang Seng Index fell 2.60% to 23,972.29, marking the weakest performance among the listed equity indices. The decline significantly exceeded the 0.79% loss recorded by India’s S&P BSE SENSEX, which stood at 71,909.70. The contrasting performance of these benchmarks illustrates the differences in market direction across Asia during the morning session.
The available data do not specify the catalysts behind the declines in Hong Kong and India. Without additional information on sector performance, company announcements or economic releases, attributing the losses to particular developments would be premature. For investors monitoring regional markets, the immediate signal is the divergence between the strong advance in Japan and the weaker readings in Hong Kong and India.
China and South Korea Exchanges Closed for National Holidays
Mainland China’s Shanghai Stock Exchange and Shenzhen Stock Exchange are closed on Monday for National Day. South Korea’s Seoul Stock Exchange and KOSDAQ are also closed for National Foundation Day of Korea, limiting live equity-market participation from two significant Asian economies.
The supplied table lists the Shanghai SSE Composite Index at 3,842.19, up 0.31%, and South Korea’s KOSPI Composite Index at 7,003.74, up 0.46%. However, these figures should not be interpreted as live gains during Monday’s morning session because the respective exchanges are closed. The reported readings provide reference points but do not represent new price discovery during the current trading period.
Outlook: Regional Performance and Market Reopening in Focus
As the Asian trading session continues, investors will be watching whether the Nikkei 225 maintains its advance, whether selling pressure in the Hang Seng persists and whether the S&P BSE SENSEX stabilizes. The reopening of mainland Chinese and South Korean exchanges will provide updated market signals and a broader view of regional equity performance. For now, the supplied figures point to a divided Asian market rather than a region-wide rally or sell-off, with the next movements in major indices and currency indicators likely to shape the near-term assessment.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- omer bar
- •
- 6 Min Read
- •
- ago 11 hours
SKN | Platinum Jan 27 (PL=F) Softens 1.32% Daily to 1,700.00 as 4.21% Weekly Pullback Holds Above 1,688 Support
The Platinum Jan 27 Futures Contract (PL=F) finished the trading session on October 2, 2026, lower, dropping 1.32% (22.80
- ago 11 hours
- •
- 6 Min Read
The Platinum Jan 27 Futures Contract (PL=F) finished the trading session on October 2, 2026, lower, dropping 1.32% (22.80

- Lior mor
- •
- 6 Min Read
- •
- ago 11 hours
SKN | Silver Dec 26 (SI=F) Softens 1.24% Daily to 60.415 as 5.96% Weekly Pullback Holds Above 59.98 Support
The Silver Dec 26 Futures Contract (SI=F) finished the trading session on October 2, 2026, lower, dropping 1.24% (0.760
- ago 11 hours
- •
- 6 Min Read
The Silver Dec 26 Futures Contract (SI=F) finished the trading session on October 2, 2026, lower, dropping 1.24% (0.760

- Arik Arkadi Sluzki
- •
- 6 Min Read
- •
- ago 11 hours
SKN | Gold Dec 26 (GC=F) Softens -0.95% Daily to 4,162.30 as 3.68% Weekly Pullback Holds Above 4,153 Support
The Gold Dec 26 Futures Contract (GC=F) finished the trading session on October 2, 2026, lower, dropping 0.95% (40.00
- ago 11 hours
- •
- 6 Min Read
The Gold Dec 26 Futures Contract (GC=F) finished the trading session on October 2, 2026, lower, dropping 0.95% (40.00

- sagi habasov
- •
- 6 Min Read
- •
- ago 11 hours
SKN | Crude Oil Nov 26 (CL=F) Softens 1.90% Daily to 91.11 as 1.41% Weekly Pullback Holds Above 88.06 Support
The Crude Oil Nov 26 Futures Contract (CL=F) finished the trading session on October 2, 2026, lower, dropping 1.90%
- ago 11 hours
- •
- 6 Min Read
The Crude Oil Nov 26 Futures Contract (CL=F) finished the trading session on October 2, 2026, lower, dropping 1.90%