
- sagi habasov
- •
- 6 Min Read
- •
- 4 hours ago
Key Points
- The dollar is trading near a 17-month high, while the euro slipped to $1.1246, close to its lowest level since May 2025.
- Concerns over France’s debt burden and political uncertainty ahead of next year’s elections have weighed on the euro, which has posted four consecutive weekly declines.
- Markets now see a 78% probability that the Fed will leave rates unchanged in October, while elevated bond yields and global debt-market volatility continue to support the dollar.
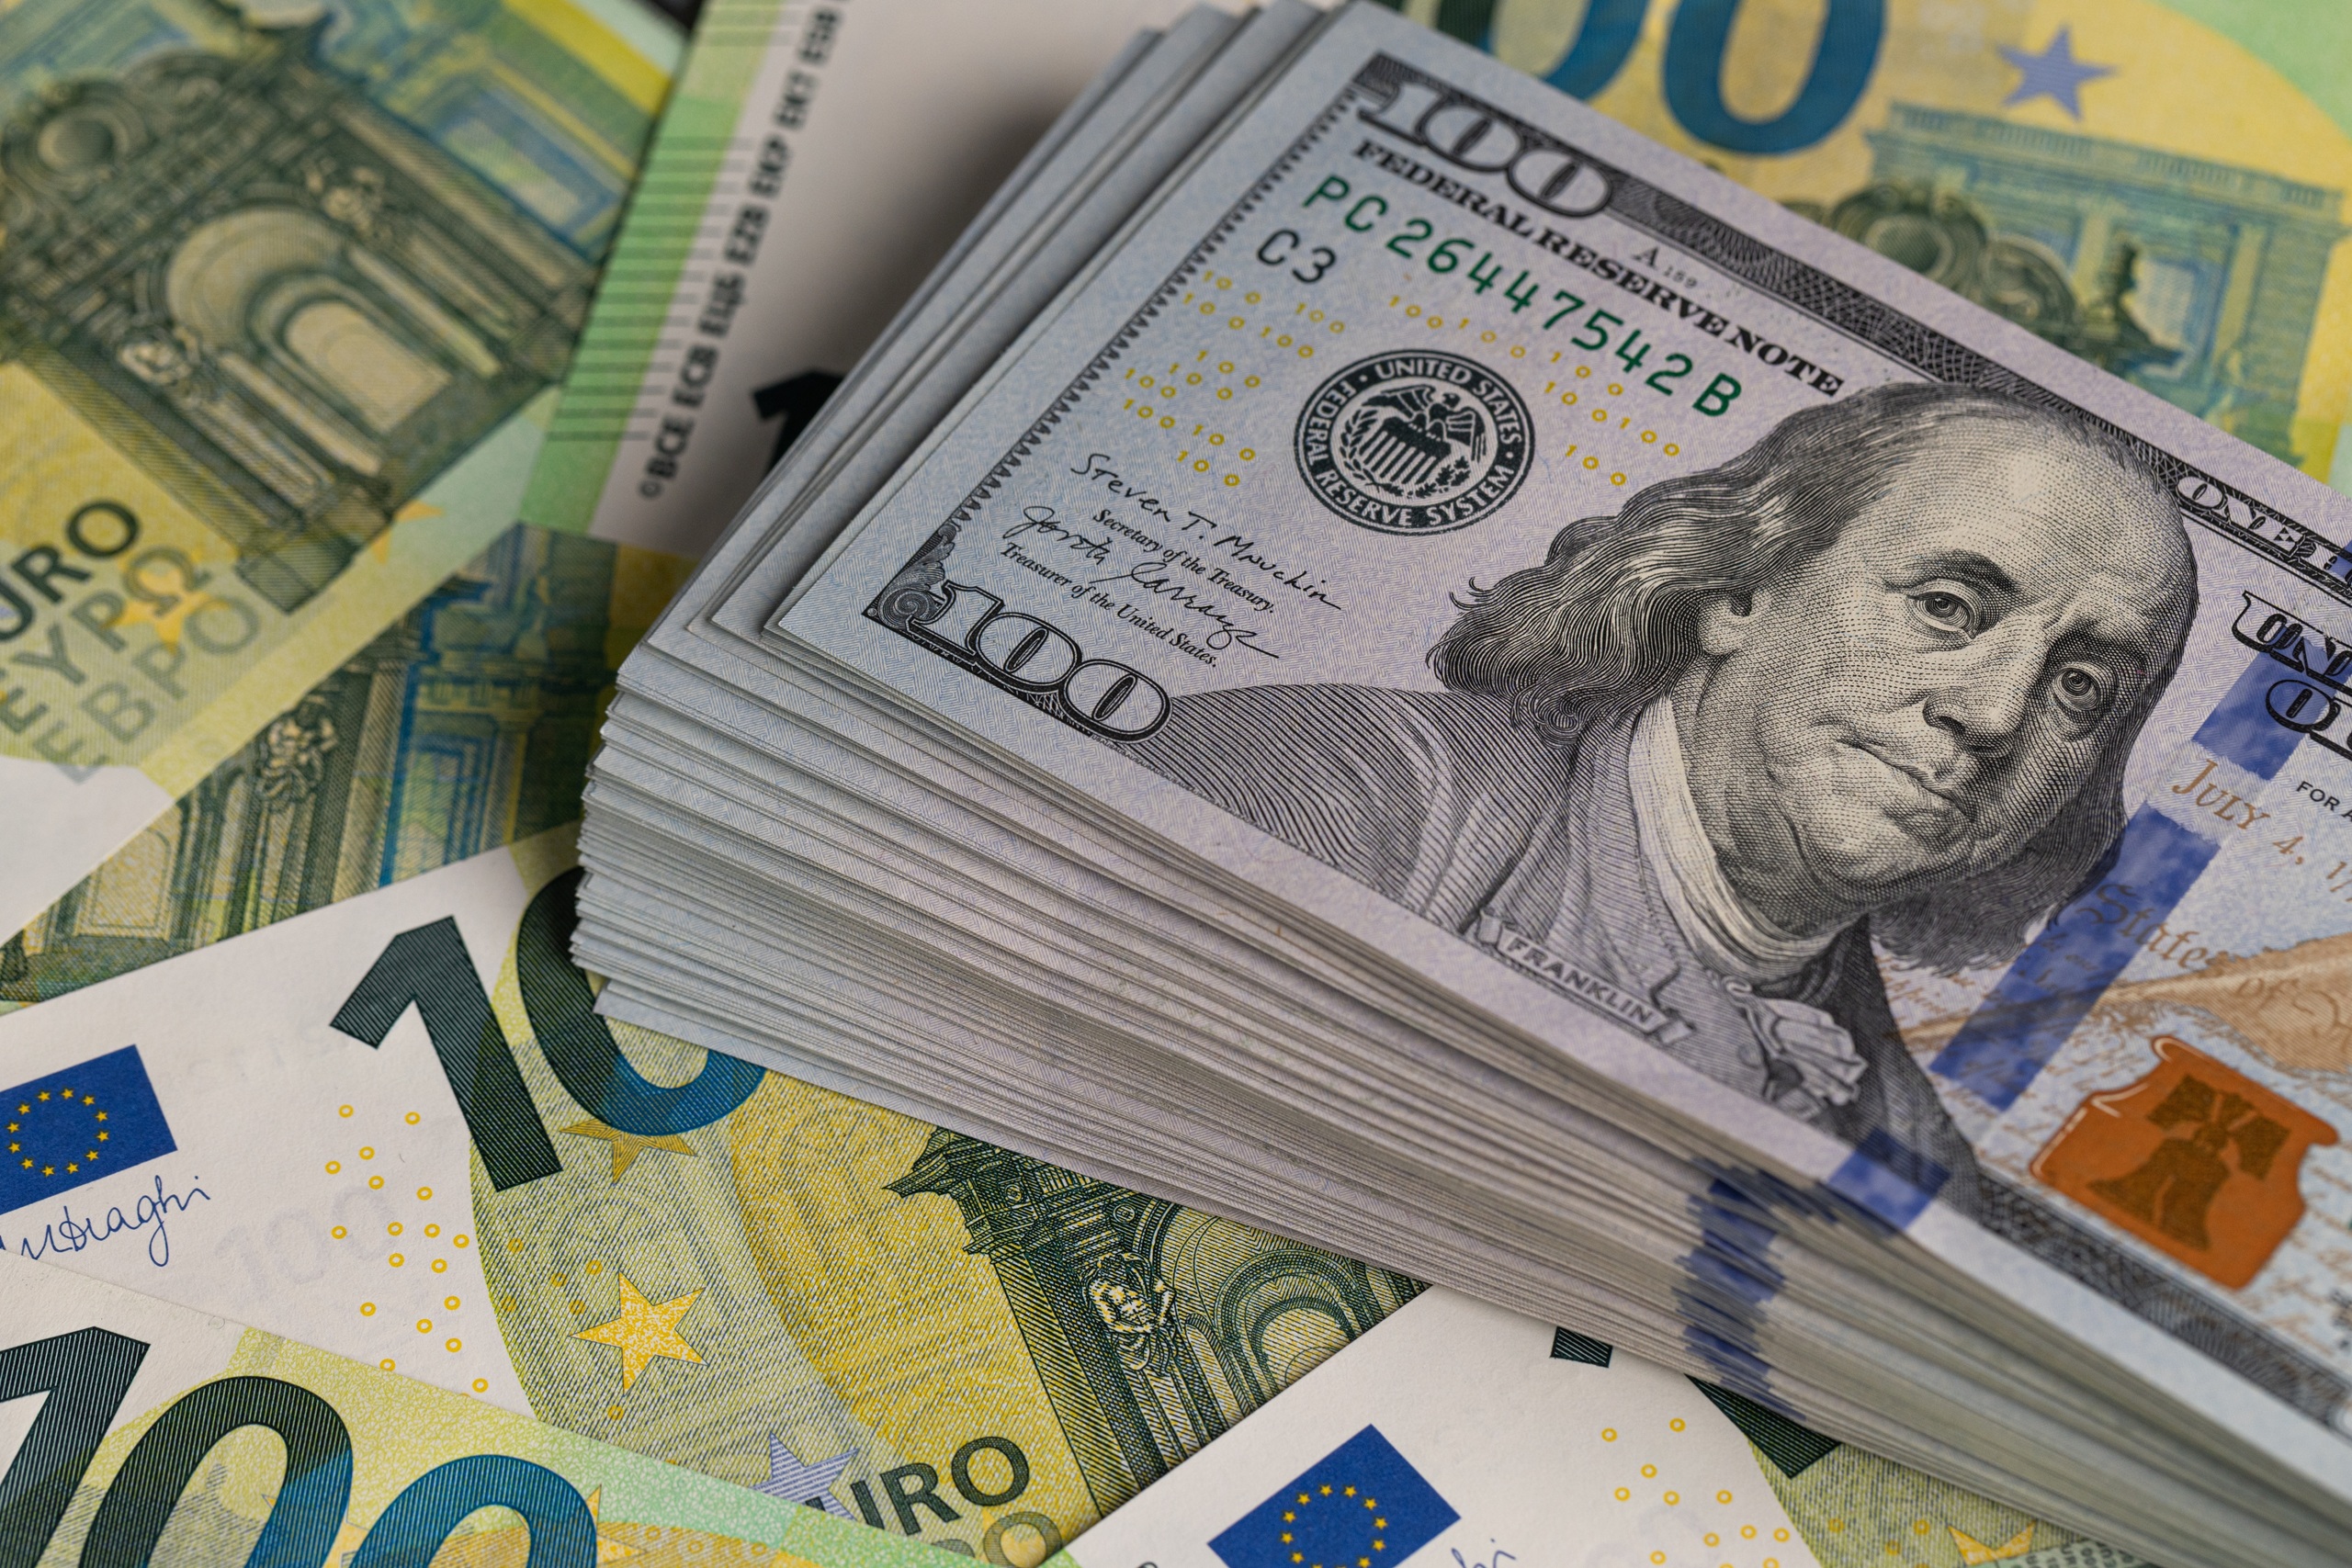
The dollar opened the week trading near a 17-month high, despite weaker U.S. labor-market data reducing expectations for an interest-rate increase by the Fed this month. At the same time, France’s fiscal difficulties and political uncertainty are weighing on the euro, strengthening demand for the dollar and other traditional safe-haven assets.
French Fiscal Concerns Keep Pressure on the Euro
The euro traded around $1.1246, close to its lowest level since May 2025, after posting four consecutive weekly declines. France’s rising debt burden and concerns over political deadlock ahead of next year’s elections have added pressure to the common currency.
The concerns extend beyond foreign exchange markets. A global bond selloff last week pushed borrowing costs to levels not seen in years, while French government bonds came under significant pressure. Investors are also increasingly focused on the inflationary risks from higher oil prices, which could further complicate fiscal and monetary policy across Europe.
Bond Yields Continue to Support the Dollar
The dollar index, which measures the U.S. currency against six major currencies, stood at 101.97. The yield on the 10-year U.S. Treasury was 5.262%, below the 24-year high reached last week that sent a fresh shock through global markets.
Higher U.S. Treasury yields increase the relative appeal of dollar-denominated assets, while global bond-market stress can encourage capital flows toward the U.S. currency as a traditional safe haven. If volatility across interest-rate markets remains elevated, cyclical currencies and carry-trade positions, along with the euro, could remain under pressure.
Fed Expectations Reshape the Interest-Rate Outlook
A significant part of the dollar’s recent strength has been driven by expectations that the Fed could raise interest rates in the coming months. However, employment data released Friday showed U.S. job growth slowed more than expected in September, prompting markets to sharply reduce the probability of an October rate increase.
Markets now price a 78% probability that the U.S. central bank will leave rates unchanged in October, compared with just 36% a week earlier. Investors still expect a rate increase in December and two additional increases during the first half of 2027. Some analysts, however, argue that current pricing may be too aggressive, particularly if oil prices decline or global growth weakens.
The next phase for the dollar and euro will depend on a combination of Fed policy, U.S. Treasury yields, energy prices and political and fiscal developments in France. Investors will also monitor U.S. inflation and employment data, alongside France’s ability to stabilize its public finances. Further deterioration in debt markets or renewed interest-rate volatility could continue to favor the dollar, while greater political stability in France and easing inflationary pressures could give the euro room to recover.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- sagi habasov
- •
- 7 Min Read
- •
- ago 15 hours
SKN | Retail Investors Are Betting Big on Long-Term Treasuries After a Historic Bond Selloff
Retail investors are increasingly moving into long-duration U.S. Treasury exposure despite one of the most difficult periods for the
- ago 15 hours
- •
- 7 Min Read
Retail investors are increasingly moving into long-duration U.S. Treasury exposure despite one of the most difficult periods for the
- sagi habasov
- •
- 8 Min Read
- •
- ago 20 hours
SKN | Hedge Funds Turn Bearish on the Yen Again as Japan’s Rate Advantage Remains Outmatched
The Japanese yen is once again becoming a focal point in global currency markets as hedge funds reverse recent
- ago 20 hours
- •
- 8 Min Read
The Japanese yen is once again becoming a focal point in global currency markets as hedge funds reverse recent

- Ronny Mor
- •
- 7 Min Read
- •
- ago 2 days
SKN | Stocks Gain After Weak US Jobs Data, but Bond Market Selloff Continues
Global financial markets reacted to a weaker-than-expected US employment report on Friday, with stocks gaining and the dollar declining
- ago 2 days
- •
- 7 Min Read
Global financial markets reacted to a weaker-than-expected US employment report on Friday, with stocks gaining and the dollar declining
- omer bar
- •
- 7 Min Read
- •
- ago 2 days
SKN | Dollar Strengthens as Treasury Yields Support Fourth Weekly Gain Against Euro
Dollar Benefits From High U.S. Yields and Fed Expectations The dollar index remained supported near multi-month highs as U.S. Treasury
- ago 2 days
- •
- 7 Min Read
Dollar Benefits From High U.S. Yields and Fed Expectations The dollar index remained supported near multi-month highs as U.S. Treasury