
- Lior mor
- •
- 8 Min Read
- •
- 27 seconds ago
Key Points
- Only about 23% of the largest 500 U.S. stocks outperformed the S&P 500 over the past decade, according to Trivariate Research data through the end of August 2026.
- The figure is similarly weak across the broader universe of the top 2,000 U.S. stocks, with only about 22% beating the index over the same period.
- The decline points to increasing market concentration, potentially leaving the broader index more dependent on a relatively small number of dominant winners.
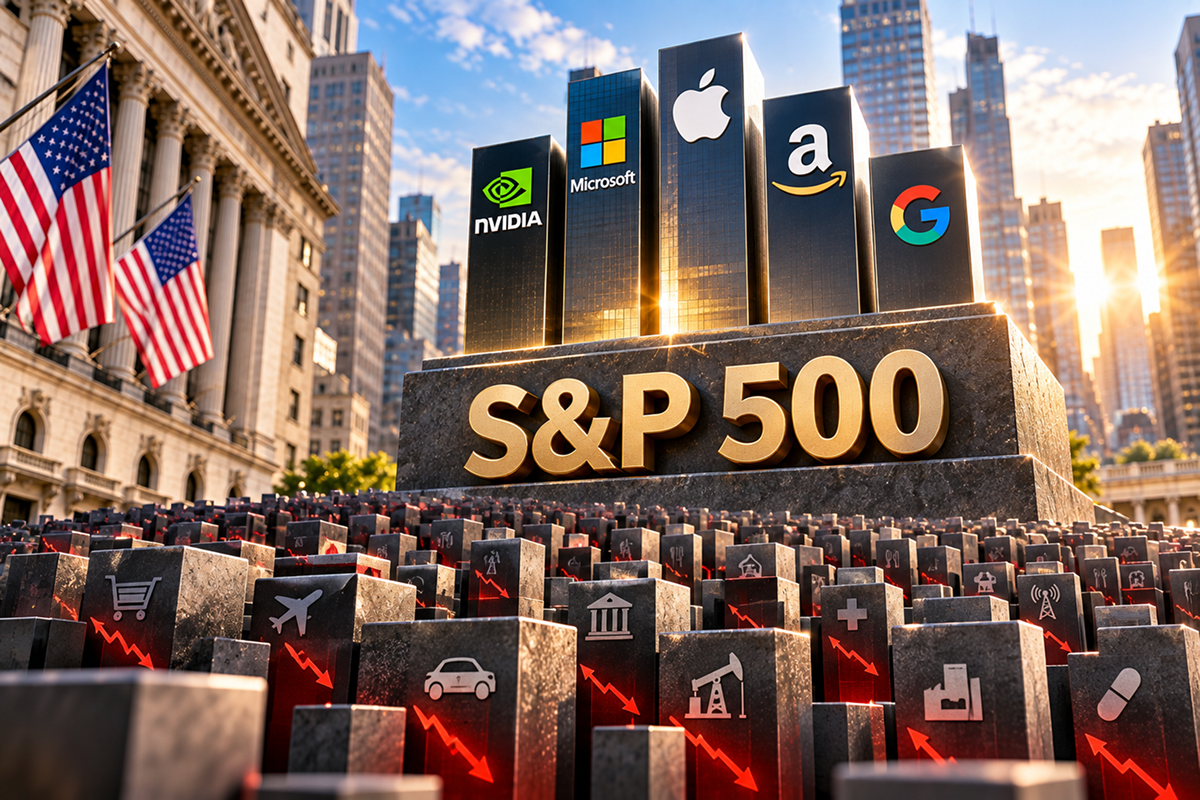
The U.S. equity market is increasingly being driven by a narrow group of companies, while a large majority of individual stocks have failed to keep pace with the S&P 500 over the long term. Data from Trivariate Research show that only about 23% of the largest 500 U.S. equities outperformed the benchmark over the 10 years through August 2026, highlighting how unusually concentrated long-term market leadership has become.
Long-Term Outperformance Has Narrowed Sharply
The latest data point to a significant deterioration in the breadth of long-term equity-market performance. Among the top 500 U.S. stocks, only approximately 23% outperformed the S&P 500 over the past decade. The figure has fallen steadily from levels seen during earlier market cycles, when a substantially larger share of individual companies was able to outperform the benchmark.
The trend is not confined to the largest companies. Across the top 2,000 U.S. equities, only about 22% outperformed the S&P 500 over the same 10-year period. According to the source data, both measures have more than halved over the past decade, indicating that the challenge is broader than simply the performance of a handful of mega-cap stocks.
Index Performance Is Becoming More Concentrated
The significance of the data lies in the widening gap between index performance and the experience of the average stock. When only roughly one-quarter of companies outperform the benchmark, the index’s long-term gains become increasingly dependent on a relatively small number of successful businesses. This dynamic can occur even when the overall index continues to produce strong returns, because the market capitalization weighting of the S&P 500 gives its largest constituents a disproportionate influence over aggregate performance.
The current environment has been reinforced by the strong performance of large technology and artificial-intelligence-related companies. A relatively small group of market leaders has generated substantial earnings growth and market-capitalization gains, while many other companies have struggled to match those results. As a result, market breadth and index returns have increasingly diverged, making the headline performance of the S&P 500 a less representative measure of the performance of individual stocks.
Why Concentration Can Increase Market Sensitivity
Concentration creates a different risk profile from a market in which leadership is broadly distributed. If a large number of companies are outperforming, weakness in individual market leaders can potentially be absorbed by gains elsewhere. But when leadership is concentrated, a deterioration in the earnings outlook, valuations or investor sentiment surrounding the dominant winners can have a greater influence on the broader benchmark.
This does not mean that a concentrated market must immediately reverse. Dominant companies can remain dominant for extended periods when they continue to deliver superior revenue growth, margins, cash generation and returns on capital. The data instead highlight a structural vulnerability: if the relatively small group of market leaders begins to weaken while the broader universe of stocks remains unable to compensate, index-level declines could become more pronounced.
The historical comparison is also notable. The source data indicate that following the Great Financial Crisis, more than half of the largest U.S. stocks were outperforming the S&P 500 over comparable periods. The current figure near 23% therefore represents a substantial change in the breadth of long-term market leadership rather than a short-term fluctuation.
Going forward, investors and policymakers will be watching whether market leadership begins to broaden or whether the concentration trend continues. A sustained improvement in corporate earnings across sectors could gradually increase participation, while renewed weakness among major index constituents could expose how dependent the benchmark has become on a limited number of winners. For global investors, including those allocating capital from Israel, the key issue is therefore not simply whether the S&P 500 rises or falls, but how broadly that performance is being generated and whether the market’s underlying breadth can improve from its current historically narrow level.
Comparison, examination, and analysis between investment houses
Leave your details, and an expert from our team will get back to you as soon as possible
* This article, in whole or in part, does not contain any promise of investment returns, nor does it constitute professional advice to make investments in any particular field.
To read more about the full disclaimer, click here
- omer bar
- •
- 7 Min Read
- •
- ago 26 minutes
SKN | US and China Money Supply Hits Record Levels: Is Global Liquidity Entering a New Expansion Cycle?
The money supply of the world’s two largest economies has reached unprecedented nominal levels, putting global liquidity back at
- ago 26 minutes
- •
- 7 Min Read
The money supply of the world’s two largest economies has reached unprecedented nominal levels, putting global liquidity back at

- sagi habasov
- •
- 8 Min Read
- •
- ago 3 hours
SKN | Hedge Funds Turn Bearish on the Yen Again as Japan’s Rate Advantage Remains Outmatched
The Japanese yen is once again becoming a focal point in global currency markets as hedge funds reverse recent
- ago 3 hours
- •
- 8 Min Read
The Japanese yen is once again becoming a focal point in global currency markets as hedge funds reverse recent

- Lior mor
- •
- 9 Min Read
- •
- ago 16 hours
SKN | Rising Mortgage Rates and Record Wealth Concentration Reshape the U.S. Financial Landscape
The U.S. economy is facing a notable combination of elevated borrowing costs and highly concentrated wealth. The latest data
- ago 16 hours
- •
- 9 Min Read
The U.S. economy is facing a notable combination of elevated borrowing costs and highly concentrated wealth. The latest data

- Ronny Mor
- •
- 8 Min Read
- •
- ago 17 hours
SKN | US and China Money Supply Reaches Record Levels: Is Global Liquidity Entering a New Expansion Cycle?
U.S. and Chinese money supply has reached unprecedented nominal levels, reinforcing the importance of liquidity conditions for global financial
- ago 17 hours
- •
- 8 Min Read
U.S. and Chinese money supply has reached unprecedented nominal levels, reinforcing the importance of liquidity conditions for global financial